Free bond yield calculator

Yield to Maturity Calculator

Yield to maturity is the yearly return you lock in when you buy a bond at today's price, collect every coupon and hold it until it's repaid. A $1,000 bond bought for $950, paying a 5% coupon twice a year with 10 years left, yields 5.66% to maturity. Its current yield is only 5.26%, because that leaves out the extra $50 you get back at the end.

Quoted and effective YTM Yield to call and yield to worst Real dates with accrued interest

Your bond

What the bond repays at maturity
Brokers quote 95.00 for this, meaning 95% of face value
Yearly interest as a % of face value. 0 for a zero-coupon bond.
US Treasuries and most US and UK bonds pay twice a year
Time to maturity
Fractions work too, like 7.5
The day you pay. Accrued interest is added to the price.
% of face value, often 100
Yield to maturity
5.66%
a year, compounded twice a year, the way brokers and Excel quote it
Bought at a discount. The $50.00 you get back above the price adds to the coupons.
Current yield5.26%Coupons for a year divided by the price
Effective annual5.74%Compounded once a year, as AllInvestView's bond report shows YTM
Yield to call-If it's called on the first call date
Yield to worst-The lower of the two

Price at other yields

If its yield rose by 1 point, the price would fall to $880.09, down 7.4%.

What you pay and get back

Held to maturity, with every coupon paid.

How yield to maturity is calculated

The same bond as the calculator's default: $1,000 face value, bought for $950, 5% coupon paid twice a year, 10 years left.

The exact equation

Find the yield that makes the cash flows worth the price

Price = C/(1+y/f)1 + C/(1+y/f)2 + … + (C+F)/(1+y/f)n
C = coupon per period, F = face value, f = coupons a year, n = periods left, y = YTM

There's no way to rearrange that for y, so you try yields until the price comes out right. Here that's 20 coupons of $25 and $1,000 at the end:

  • Try 5.50%, price comes out at $961.93
  • Try 5.70%, price comes out at $947.20
  • 5.66% gives the $950 you paid YTM 5.66%
The shortcut

Approximate YTM by hand

YTM ≈ [C + (F − P) / n] / [(F + P) / 2]
C = coupons a year, P = price, n = years left

For our bond: ($50 + $50 / 10) / $975 = 5.64%, close to the exact 5.66%.

It drifts on long bonds bought far below face value. A 30-year bond with a 3% coupon bought for $600 comes out at 5.42% with the shortcut, against an exact 5.84%.

Coupon rate, current yield and YTM side by side

Three 10-year bonds with the same 5% coupon, paid twice a year. Only the price differs.

PriceCoupon rateCurrent yieldYield to maturityWhat's going on
$900 Discount5.00%5.56%6.37%The $100 you gain at maturity lifts YTM above both
$1,000 Par5.00%5.00%5.00%At face value all three are the same
$1,100 Premium5.00%4.55%3.79%The $100 you lose at maturity eats into the coupons

Yield to call and yield to worst

A callable bond can be repaid early, at the issuer's choice. That changes the yield you can count on.

Example

A 6% bond bought at $1,080, callable at $1,000 in 3 years

To maturity4.97%
To call3.18%
To worst3.18%

Ten years of 6% coupons make the $80 premium easy to earn back. Three years don't. Issuers call when rates have dropped enough to borrow for less, which is exactly when you'd want to keep the bond, so the 3.18% is the number to plan on.

How each one is worked out

Yield to call is the same calculation as YTM, with the call date in place of the maturity date and the call price in place of face value. FINRA's guidance is to use the first date the issuer can call.

Yield to worst is the lowest of the yield to maturity and the yield to each call date. Brokers show it for callable corporate and municipal bonds because it's the lowest return you can get if the issuer pays as promised.

Tick "The issuer can call it early" in the calculator to get both for your bond.

Yield to maturity in Excel or Google Sheets

Both have the same two functions. YIELD takes real dates; RATE works in whole periods.

With dates: YIELD

A US Treasury, 4.625% maturing 15 June 2033, quoted at 99.75

=YIELD(DATE(2026,10,22), DATE(2033,6,15), 4.625%, 99.75, 100, 2, 1)

Returns 4.67%. The arguments are settlement date, maturity date, coupon rate, price per 100, redemption per 100, coupons a year and day count (1 is actual/actual, the Treasury convention).

Accrued interest is handled for you: settling on 22 October 2026, you'd also pay 1.63 per 100 for the 129 days since the June coupon. Put the same dates into the calculator above and you get 4.67% too.

Whole periods: RATE

The $950 bond from the example

=RATE(20, 25, -950, 1000) * 2

Returns 5.66%. RATE gives the yield per period, so multiply by the number of coupons a year.

The arguments are periods left, coupon per period, the price as a negative number (money going out) and face value. It only fits when settlement falls on a coupon date.

What a 1-point move in rates does to the price

Three bonds with a 5% coupon, all bought at $1,000 to yield 5%. Then market yields move to 4% or 6%.

BondRise to 6%Fall to 4%
2 years$981 / $1,019
-1.9%
+1.9%
10 years$926 / $1,082
-7.4%
+8.2%
30 years$862 / $1,174
-13.8%
+17.4%

The longer the bond, the bigger the swing, and prices rise more on a fall than they drop on a rise. That sensitivity is duration. Hold to maturity and none of it touches your YTM; sell early and it decides your return. The yield curve calculator shows where today's rates sit by maturity, and the bond spread calculator shows how much extra a corporate bond pays over government debt.

For the bonds you own

Every bond in your portfolio, with its yield worked out

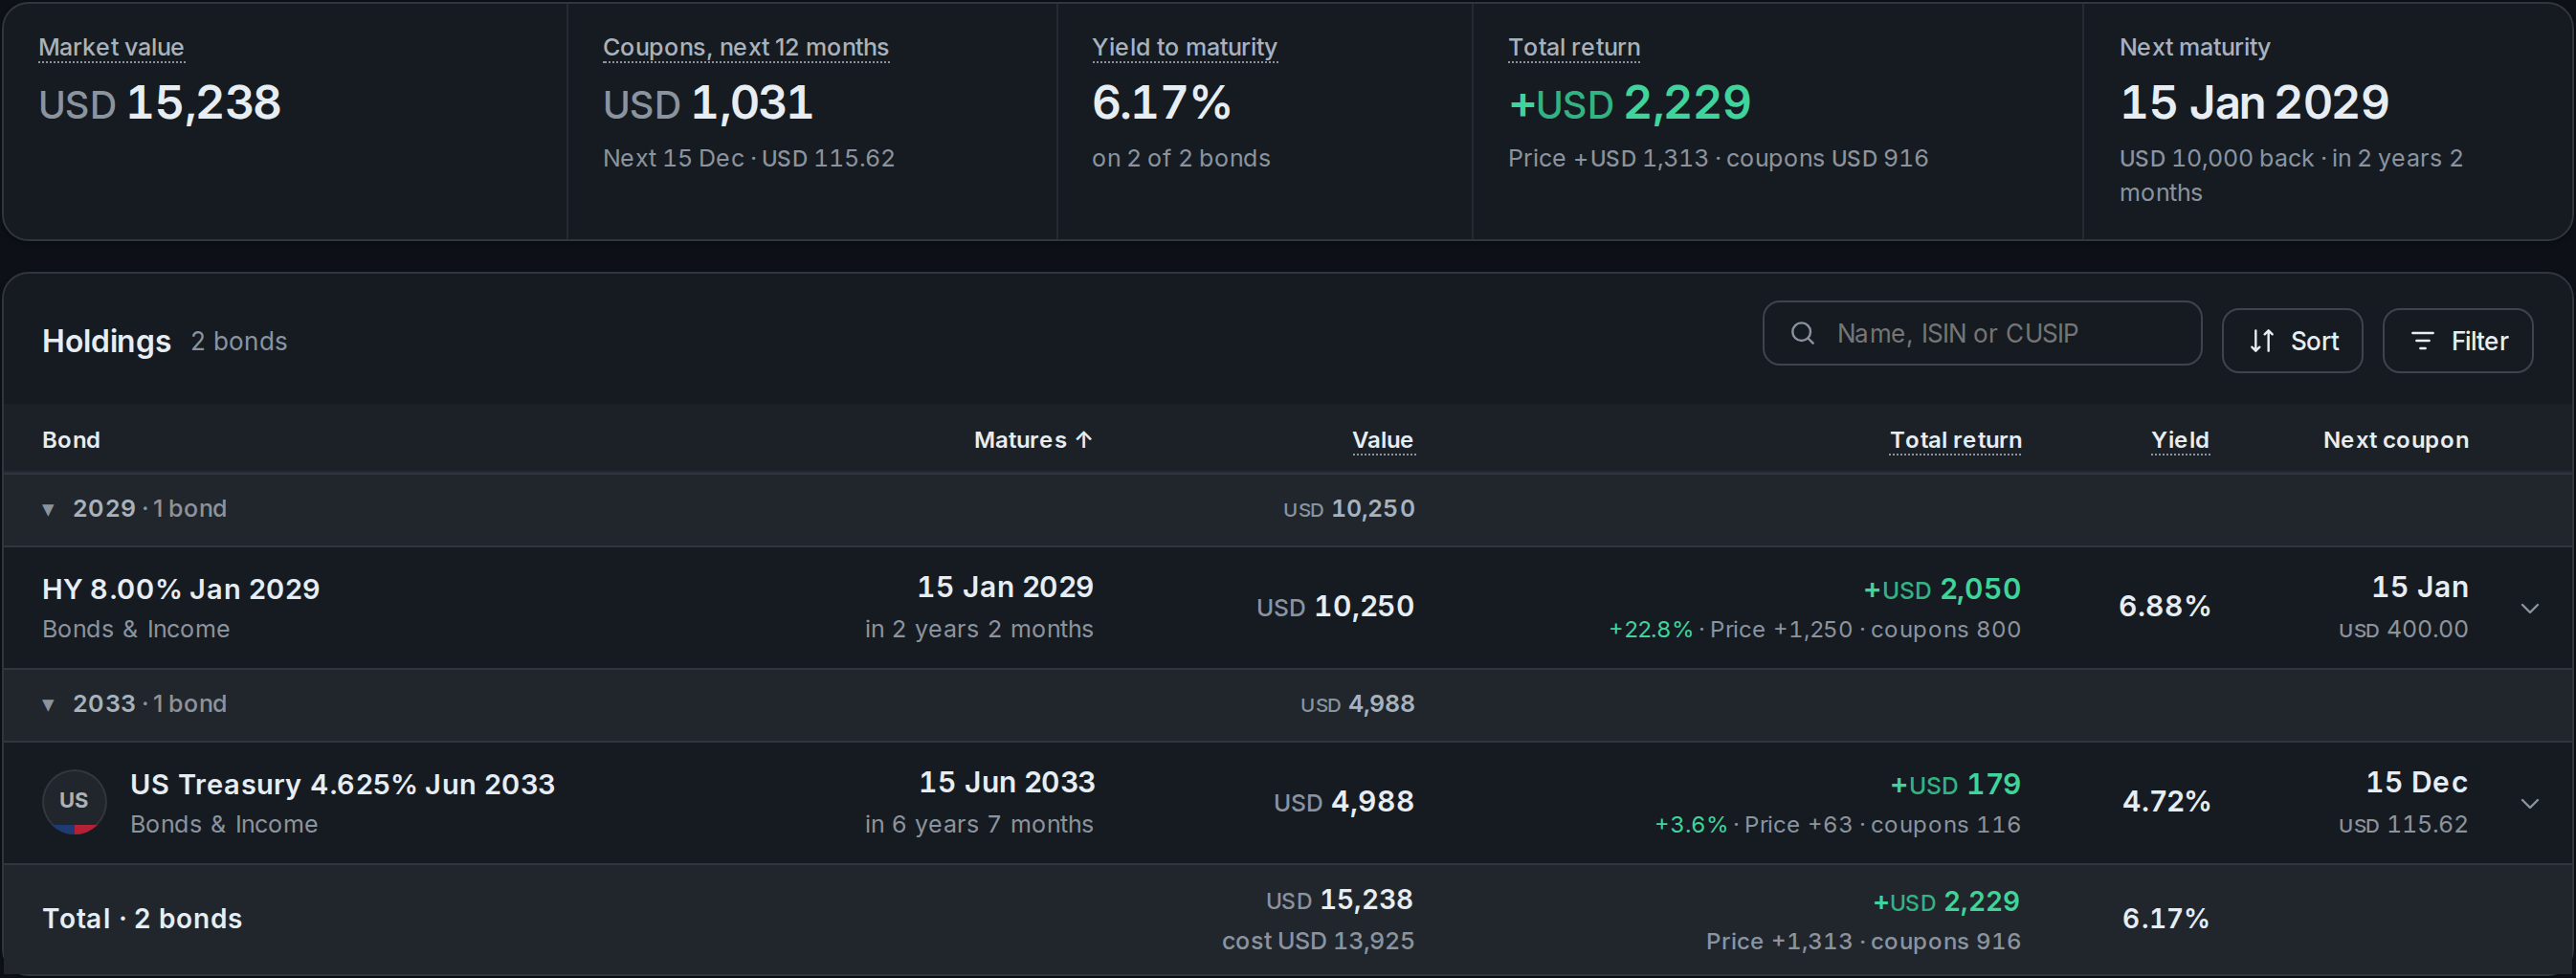
The bond report shows the yield to maturity of each bond and of the whole book, the coupons due over the next 12 months and each bond's return split into price and coupons. Your bonds sit in the same portfolio as your stocks, ETFs and options, synced from your brokers or imported from a file. Open a bond for its payment schedule, purchases, duration and spread over the government curve.

See the bond tracker

AllInvestView AllInvestView bond report with yield to maturity 6.17% on 2 of 2 bonds, coupons for the next 12 months, total return, and a holdings table showing 6.88% on a high-yield bond due January 2029 and 4.72% on a US Treasury 4.625% due June 2033 AllInvestView bond report with yield to maturity 6.17% on 2 of 2 bonds, coupons for the next 12 months, total return, and a holdings table showing 6.88% on a high-yield bond due January 2029 and 4.72% on a US Treasury 4.625% due June 2033
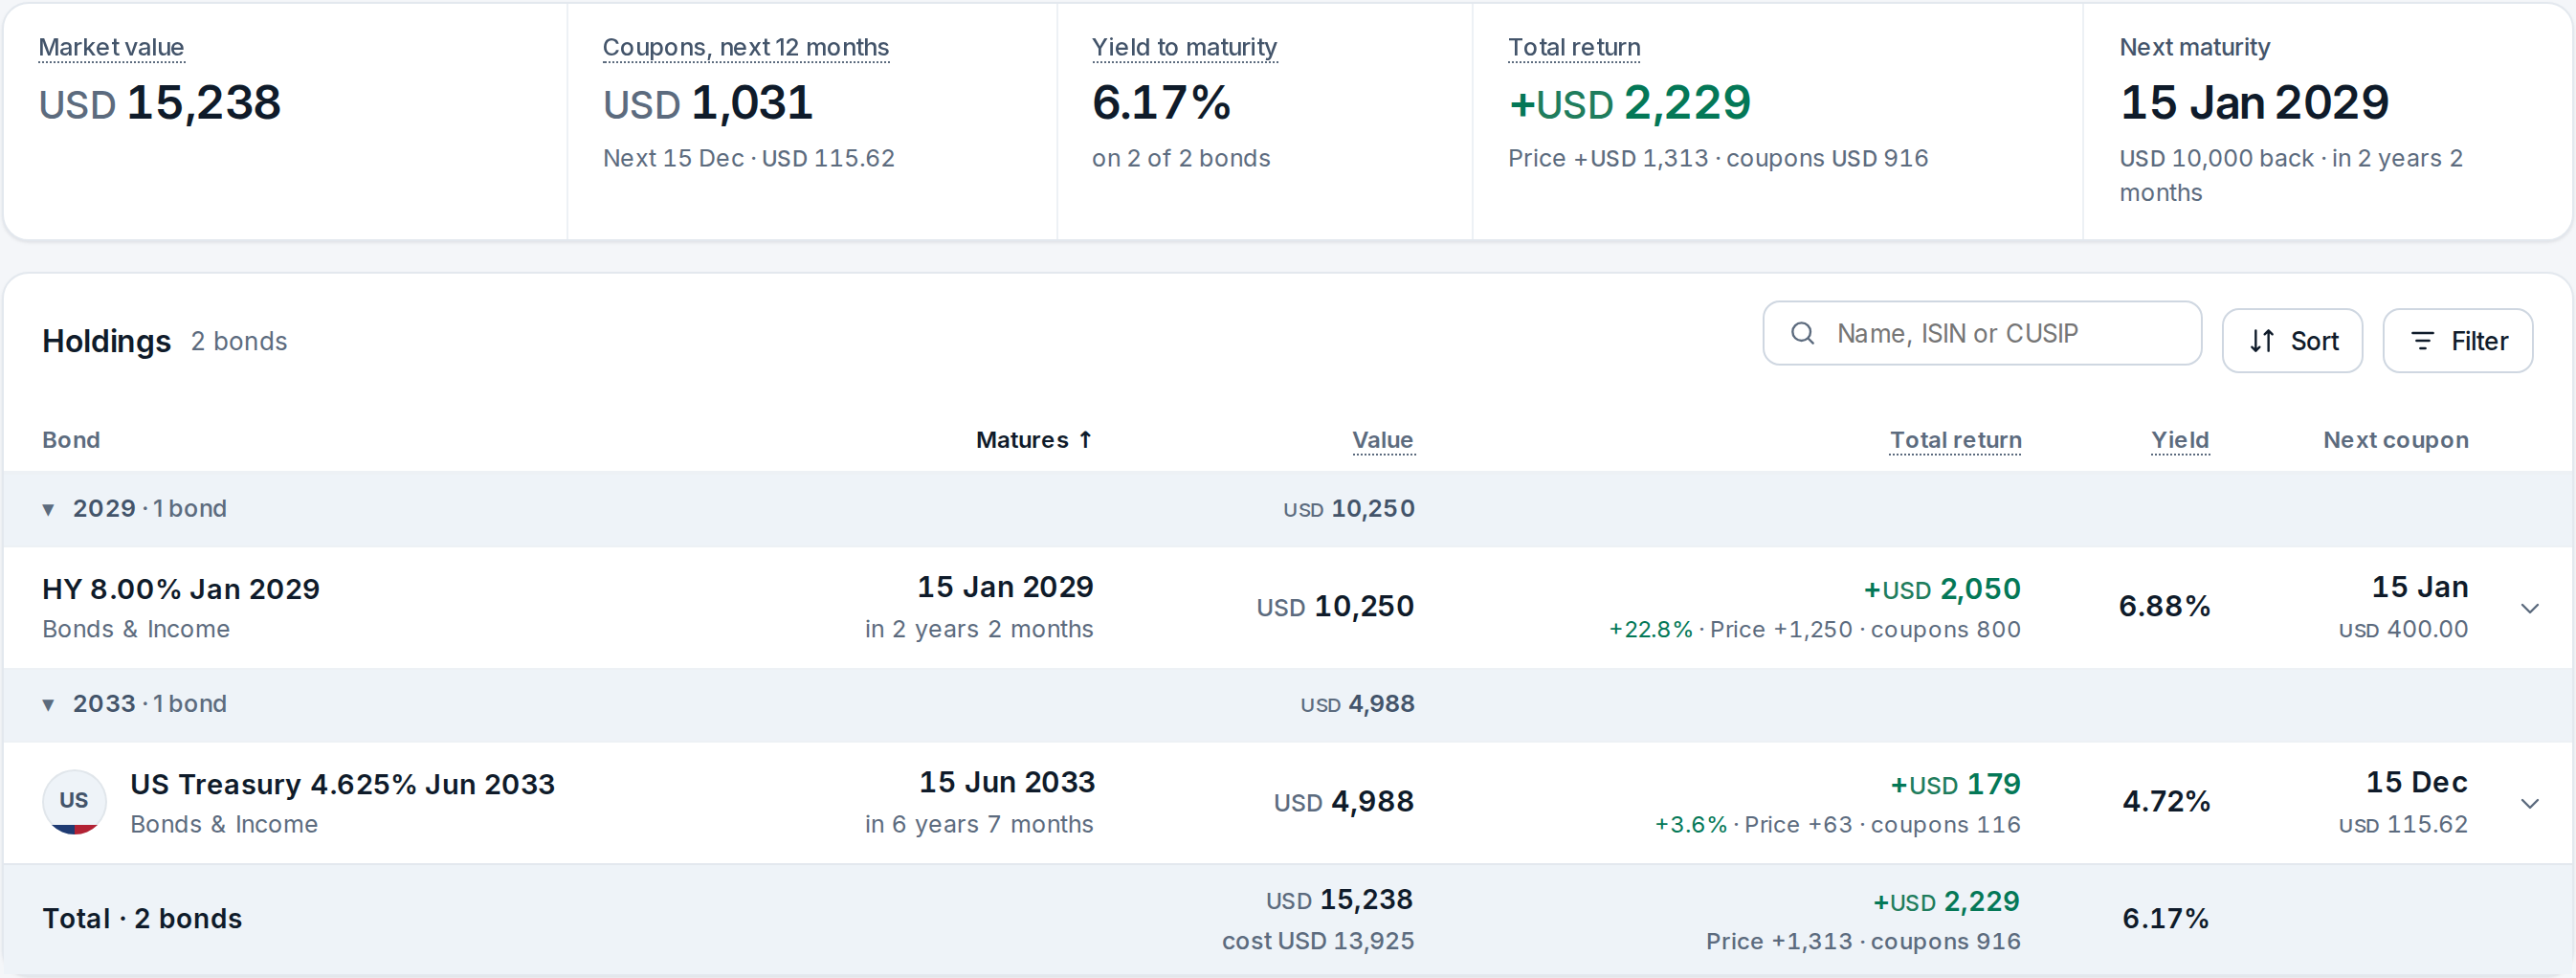
The bond report: 6.17% yield to maturity across the book, 4.72% on the US Treasury 4.625% 2033 and 6.88% on a high-yield bond due 2029. Seeded demo portfolio.View full-size View full-size
Tracking bonds you own

AllInvestView keeps the yield of every bond you hold

This calculator works out one bond. AllInvestView does it for all of them, next to your stocks, ETFs and options from every broker, and shows the average yield of your whole bond book.

YTM, duration and convexity per bond Stocks, ETFs, options and bonds together Free for up to 10 holdings

Yield to maturity questions

Is yield to maturity the return I'll actually get?

Only if you keep the bond until it's repaid, the issuer pays every coupon and the principal on time, and you reinvest each coupon at the same yield. Sell early or reinvest at a different rate and your return will differ. YTM is the best single estimate when you buy, not a promise.

Why does my broker show a slightly different yield?

Usually it's the settlement date, accrued interest or the compounding. Switch the calculator to maturity date, enter the quoted price and your trade's settlement date, and it adds accrued interest the way brokers do. Quoted yields compound as often as the bond pays, twice a year for Treasuries. The effective annual figure compounds once a year, so it's a little higher.

Can yield to maturity be negative?

Yes. If you pay more than the coupons and the repayment add up to, the yield is below zero. A 3-year bond with a 1% annual coupon bought at 110% of face value yields -2.19% to maturity. Many euro and Japanese government bonds traded at negative yields in the late 2010s.

How do you work out YTM on a zero-coupon bond?

With no coupons there's a direct formula: divide face value by price, take the root for the number of years and subtract 1. A 5-year zero bought at $780 for $1,000 of face value yields 5.09% a year compounded annually, or 5.03% quoted with semiannual compounding. Set the coupon rate to 0 in the calculator to get the same answer.

What is yield to worst?

The lowest of a bond's yield to maturity and its yield to each date it can be called. For a callable bond bought above its call price, yield to call is usually the lower one, so that's the figure to compare with other bonds. The calculator works it out for the call date and price you enter.

What's the difference between YTM and the coupon rate?

The coupon rate is fixed when the bond is issued: yearly interest as a share of face value. YTM moves with the price every trading day. Buy below face value and YTM is above the coupon rate; buy above it and YTM is below.

Sources and how the calculator works

The calculator solves the price equation exactly rather than using the shortcut. Coupon dates are counted back from maturity, and accrued interest uses actual days in the coupon period. Yields are before tax and fees and assume the issuer pays in full. Every example here was checked on 22 October 2026 against AllInvestView's bond engine, and the spreadsheet ones against the formulas Microsoft documents for YIELD and RATE.