Bond investing · updated October 2026

What are bonds? How bonds work and how to invest in them

A bond is a loan you make to a government or a company. Most pay a fixed interest, the coupon, usually twice a year, and give back their face value on the maturity date. In between, a bond's price moves the opposite way to interest rates: when rates rise, bonds you already own fall in price, and when rates fall, they rise. You can buy single bonds, from $100 for US Treasuries, or a bond fund that holds thousands of them.

$10,000 of the 10-year US Treasury, 4.625% due Aug 2036At the 5.00% 10-year Treasury yield on 23 Oct 2026
You pay$9,71197.11 per 100 of face value

Plus $87 of interest built up since 15 Aug, which the next coupon pays back

It pays you$462.50A year, $231.25 at a time

Every 15 February and 15 August until 2036

If rates rise 1 point$8,990Down 7.4%

And $10,503 if they fall 1 point, up 8.2%

At maturity$10,000Back on 15 Aug 2036

Whatever the price did in between, if you hold it

How bonds work

The same Treasury note from start to finish. Most bonds follow these four steps; only the issuer, the coupon and the dates change. Zero-coupon bonds skip step two, floating-rate bonds reset their coupon, and callable bonds can be repaid early.

  1. You lend the money

    The US Treasury sold this note at auction on 12 August 2026 at a 4.683% yield, just under face value. Its terms were fixed that day: a 4.625% coupon and a maturity of 15 August 2036.

  2. It pays the coupon

    Every six months the holder gets half the coupon: $231.25 per $10,000. A company has to offer a higher yield than the government, to pay for the chance it can't pay.

  3. The price moves every day

    Holders can sell to other investors at any time. The price is whatever makes the remaining payments yield what new bonds pay. On 23 October the 10-year yield was 5.00%, which puts the note at about 97.11.

  4. Your money comes back

    On 15 August 2036 the last coupon and the full face value are paid to whoever holds the note, whatever they paid for it.

Why bond prices fall when interest rates rise

The note's coupons are fixed at 4.625%. If new 10-year bonds start paying 6%, nobody will pay 97 for 4.625%; the price drops until the old note also yields 6%. When rates fall, the reverse happens.

$10,000 of the 4.625% Aug 2036 note at different yields

Price on 23 October 2026, against $9,711 at 5.00%, the 10-year yield that day.

  • 3.0%−2 points
    $11,372+$1,661
  • 4.0%−1 point
    $10,503+$792
  • 4.5%−0.5
    $10,098+$387
  • 5.0%23 Oct
    Today
    $9,711
  • 5.5%+0.5
    $9,342−$369
  • 6.0%+1 point
    $8,990−$721
  • 7.0%+2 points
    $8,333−$1,378

Clean prices, without the $87 of accrued interest, on the note's own coupon dates.

Longer bonds move more

What a 1 point rise would do to a new Treasury bought at face value on 23 October 2026, at that day's yield for each term.

2-year at 4.69%−1.9%

Duration 1.9 years

10-year at 5.00%−7.4%

Duration 7.8 years

30-year at 5.33%−13.4%

Duration 14.9 years

That number is the bond's duration: roughly the % its price moves for each 1 point change in rates. It's the single best measure of how much rate risk you hold. Work it out for any bond with the bond calculator or see the full price-yield curve in the yield to maturity calculator.

What 2022 did to bonds, and what came back

The 10-year Treasury yield went from 1.63% on the first trading day of 2022 to 3.88% on the last. Here is the 10-year note sold in November 2021, 1.375% due November 2031, per $10,000 of face value, priced at each day's Treasury yield for its remaining term.

  1. Nov 2021 auction$9,935Yield 1.44%

    Bought just under face value.

  2. 3 Jan 2022$9,768Yield 1.63%

    Rates start to climb.

  3. 30 Dec 2022$8,119Yield about 3.9%

    18% below the auction price in about a year.

  4. 23 Oct 2026$8,467Yield 4.82%

    Higher rates now, but five years closer to $10,000.

  5. 15 Nov 2031$10,000Maturity

    Paid in full, with $137.50 of coupons every year on the way.

Someone who sold at the end of 2022 lost about $1,800 per $10,000. Someone who held loses nothing on the price: a bond's price drifts back to face value as maturity gets closer. What they gave up is the difference between 1.375% and the 4% to 5% that new bonds have paid since. That's the real cost of buying a long bond at a low yield.

A total bond market index fund, every year from 1987 to 2025

-13.2% in 2022 was its worst year by far. The 5 other losing years were all smaller than 3%, and in 2008, when stocks lost 37.0%, it gained 5.1%.

  • Gain
  • Loss
  • Average 5.0% a year from 1987 to 23 Oct 2026

Vanguard Total Bond Market Index Fund (VBMFX), distributions reinvested, the same series as our 60/40 portfolio study.

Types of bonds

Who borrows the money decides most of the risk and the tax. The ratings agencies call a bond rated BBB− (Baa3 at Moody's) or higher investment grade; anything lower is high yield.

TypeWho issues itRiskUS tax on the interestWhere to buy
Treasury bills, notes and bondsA few weeks to 30 yearsThe US governmentLowest credit risk
Long ones still swing with rates
Federal only; free of state and local taxTreasuryDirect, any broker, Treasury funds
TIPS5, 10 and 30 yearsThe US governmentLowest credit risk
Principal rises with inflation
Federal, including each year's inflation increase; free of state taxTreasuryDirect, brokers, TIPS funds
Savings bondsSeries I and EEThe US governmentCan't fall in value
Locked for 12 months; cashing in before 5 years costs 3 months of interest
Federal, which you can defer until you cash in; free of state taxTreasuryDirect only, up to $10,000 a year of each series
Municipal bondsStates, cities, school districts, utilitiesLow to moderate
Depends on the issuer
Usually free of federal tax, and of state tax in your own stateBrokers, muni funds
Agency and mortgage bondsFannie Mae, Freddie Mac, Ginnie Mae, the Home Loan BanksLow
Mortgage bonds repay early when rates fall
Federal; some are also taxed by statesBrokers, total bond market funds
Investment-grade corporateCompanies rated BBB− or higherLow to moderate
Pays a spread over Treasuries
Federal and stateBrokers, corporate bond funds
High-yield corporateCompanies rated below BBB−Higher
More defaults; tends to fall when stocks do
Federal and stateMostly through funds
International and emerging marketsForeign governments and companiesVaries widely
Adds currency and country risk
Federal and stateMostly through funds

The extra yield a company pays over a Treasury of the same maturity is its credit spread. See what it is today for any bond with the bond spread calculator.

How to buy bonds

There are three ways in. Most people use a broker, for single bonds or bond funds; TreasuryDirect sells Treasuries and savings bonds straight from the government.

TreasuryDirect

The Treasury's own site. You buy new Treasuries at auction and hold them to maturity, with no fees.

  • Treasuries from $100, in $100 steps; savings bonds from $25
  • Bills, notes, bonds, TIPS and the only place for savings bonds
  • To sell early you first move the bond to a broker, which you can do once you've held it 45 days

A broker

Large brokers sell new Treasuries at auction and let you search thousands of corporate, municipal and agency bonds already trading, by maturity, yield and rating.

  • Treasuries and most other bonds in $1,000 pieces
  • Sell any day the market is open
  • The broker's markup is built into the price; on many corporate, agency and municipal trades the confirmation shows it

A bond fund or ETF

One trade buys a slice of thousands of bonds. Total bond market ETFs such as Vanguard's BND or iShares AGG charge 0.03% a year.

  • ETFs from one share; mutual funds set their own minimum
  • Pays a monthly income that changes as the fund's yield does
  • Never matures: you get whatever the price is when you sell (target-maturity ETFs are the exception)

A bond ladder is a middle way: single bonds maturing one after another, say every year for five or ten years, so part of your money comes back each year and gets reinvested at the rates of the day.

Build a bond ladder

Individual bonds vs bond funds

Both hold the same kind of bonds. The difference is the end date: a bond has one, most funds don't.

Individual bondsBond fund or ETF
What you get backFace value on a known date, if the issuer paysThe market price on the day you sell
IncomeFixed coupons on fixed datesMonthly payouts that rise and fall with the fund's yield
After rates riseThe price falls, then works its way back to face value by maturityThe price falls; the fund reinvests at the higher yields, so its income rises and starts to win the loss back
Spread of riskAs many issuers as you buyHundreds or thousands
CostsA markup or spread when you trade, no yearly feeA yearly expense ratio, as low as 0.03% for index ETFs
Minimum$100 for Treasuries at TreasuryDirect, usually $1,000 at a brokerOne ETF share; mutual funds set a minimum
Best forMoney needed on a set date: a house, a tuition bill, the first years of retirementThe bond part of a long-term portfolio

Bonds vs stocks

A stock is a share of a company and of its future profits. A bond is a loan with fixed payments. Stocks have grown more over long periods; bonds have fallen much less in the bad years, which is why most portfolios hold both. How much of each is the subject of the asset allocation guide.

BondsStocks
What you ownA loan to the issuerA piece of the company
What it paysA fixed couponDividends the company can raise, cut or stop
At the endFace value back at maturityNo end date; you sell at the market price
If the company goes bustPaid before shareholdersPaid last, often nothing
Yearly return, 1987 to Oct 20265.0%11.2%
Worst calendar year-13.2% in 2022-37.0% in 2008
Deepest fall from a high-18.8%-55.3%
In 2008 and 2022+5.1% and -13.2%-37.0% and -18.2%

Returns are Vanguard's Total Bond Market Index Fund (VBMFX) and 500 Index Fund (VFINX) with distributions reinvested, from 1987 to 23 October 2026.

Are bonds a good investment?

For a high-quality bond held to maturity, the yield you buy at is very close to the return you get. That makes the starting yield the best guide there is, and it's far higher now than when 2022 began.

US Treasury yields, then and now

Official par yields on 3 January 2022 and 23 October 2026.

  • 3 months
    0.08%
    4.22%
  • 1 year
    0.40%
    4.44%
  • 2 years
    0.78%
    4.69%
  • 5 years
    1.37%
    4.82%
  • 10 years
    1.63%
    5.00%
  • 30 years
    2.01%
    5.33%
  • 3 Jan 2022
  • 23 Oct 2026

When bonds make sense

Money you'll need within a few years
A Treasury maturing when you need the money pays a known amount on a known date; a stock fund might be down 30% that year.
A cushion for a stock portfolio
In most stock market falls, high-quality bonds held up or rose, as in 2008. 2022, when both fell, was the exception, and it started from yields near 1.6%.
Income you can plan around
Coupons arrive on fixed dates, which is why retirees often build ladders.
What they won't do
Grow like stocks over decades: 5.0% a year against 11.2% since 1987. And inflation above the yield shrinks what the coupons buy, which TIPS and I bonds protect against.

Track your bonds next to everything else

Each broker shows only the bonds it holds. AllInvestView keeps single bonds and bond funds in the same portfolio as your stocks, ETFs and options, and works out what a bond investor actually needs to know.

Bond report

Yield, coupons and maturities for the whole book

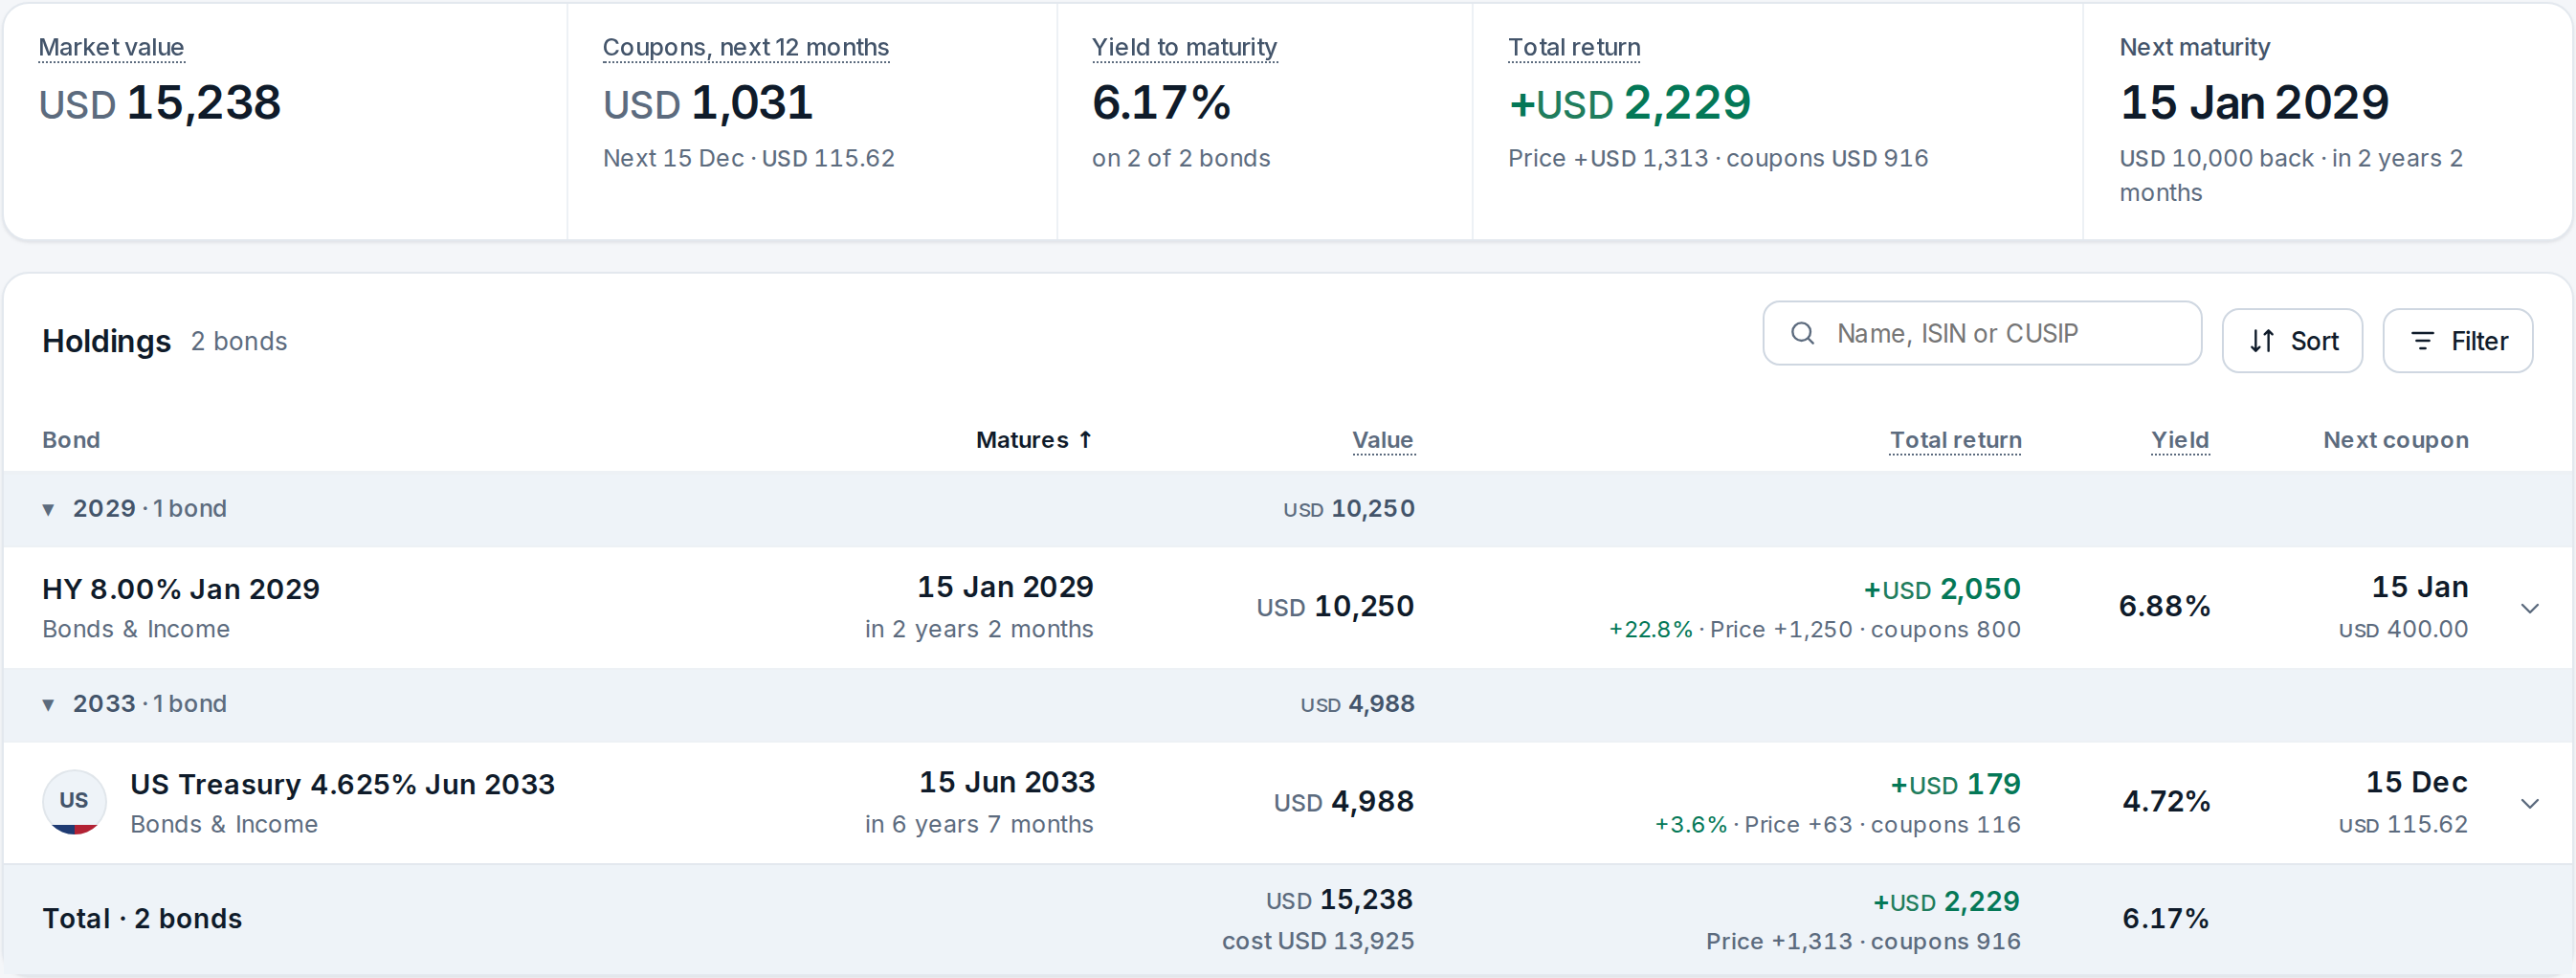
Each bond shows its yield to maturity, its next coupon and its total return, split into price and coupons received. The strip on top adds up the market value, the coupons due in the next 12 months, the book's yield and the next maturity. Bonds are grouped by the year they mature, so you can see when your money comes back.

See the bond tracker
AllInvestView AllInvestView bond report: market value USD 15,238, coupons in the next 12 months USD 1,031, yield to maturity 6.17% on 2 of 2 bonds, total return +USD 2,229, next maturity 15 Jan 2029; holdings HY 8.00% Jan 2029 at 6.88% and US Treasury 4.625% Jun 2033 at 4.72% AllInvestView bond report: market value USD 15,238, coupons in the next 12 months USD 1,031, yield to maturity 6.17% on 2 of 2 bonds, total return +USD 2,229, next maturity 15 Jan 2029; holdings HY 8.00% Jan 2029 at 6.88% and US Treasury 4.625% Jun 2033 at 4.72%
A demo book of two example bonds.View full-size View full-size
Rate risk

What a move in rates would do to your bonds

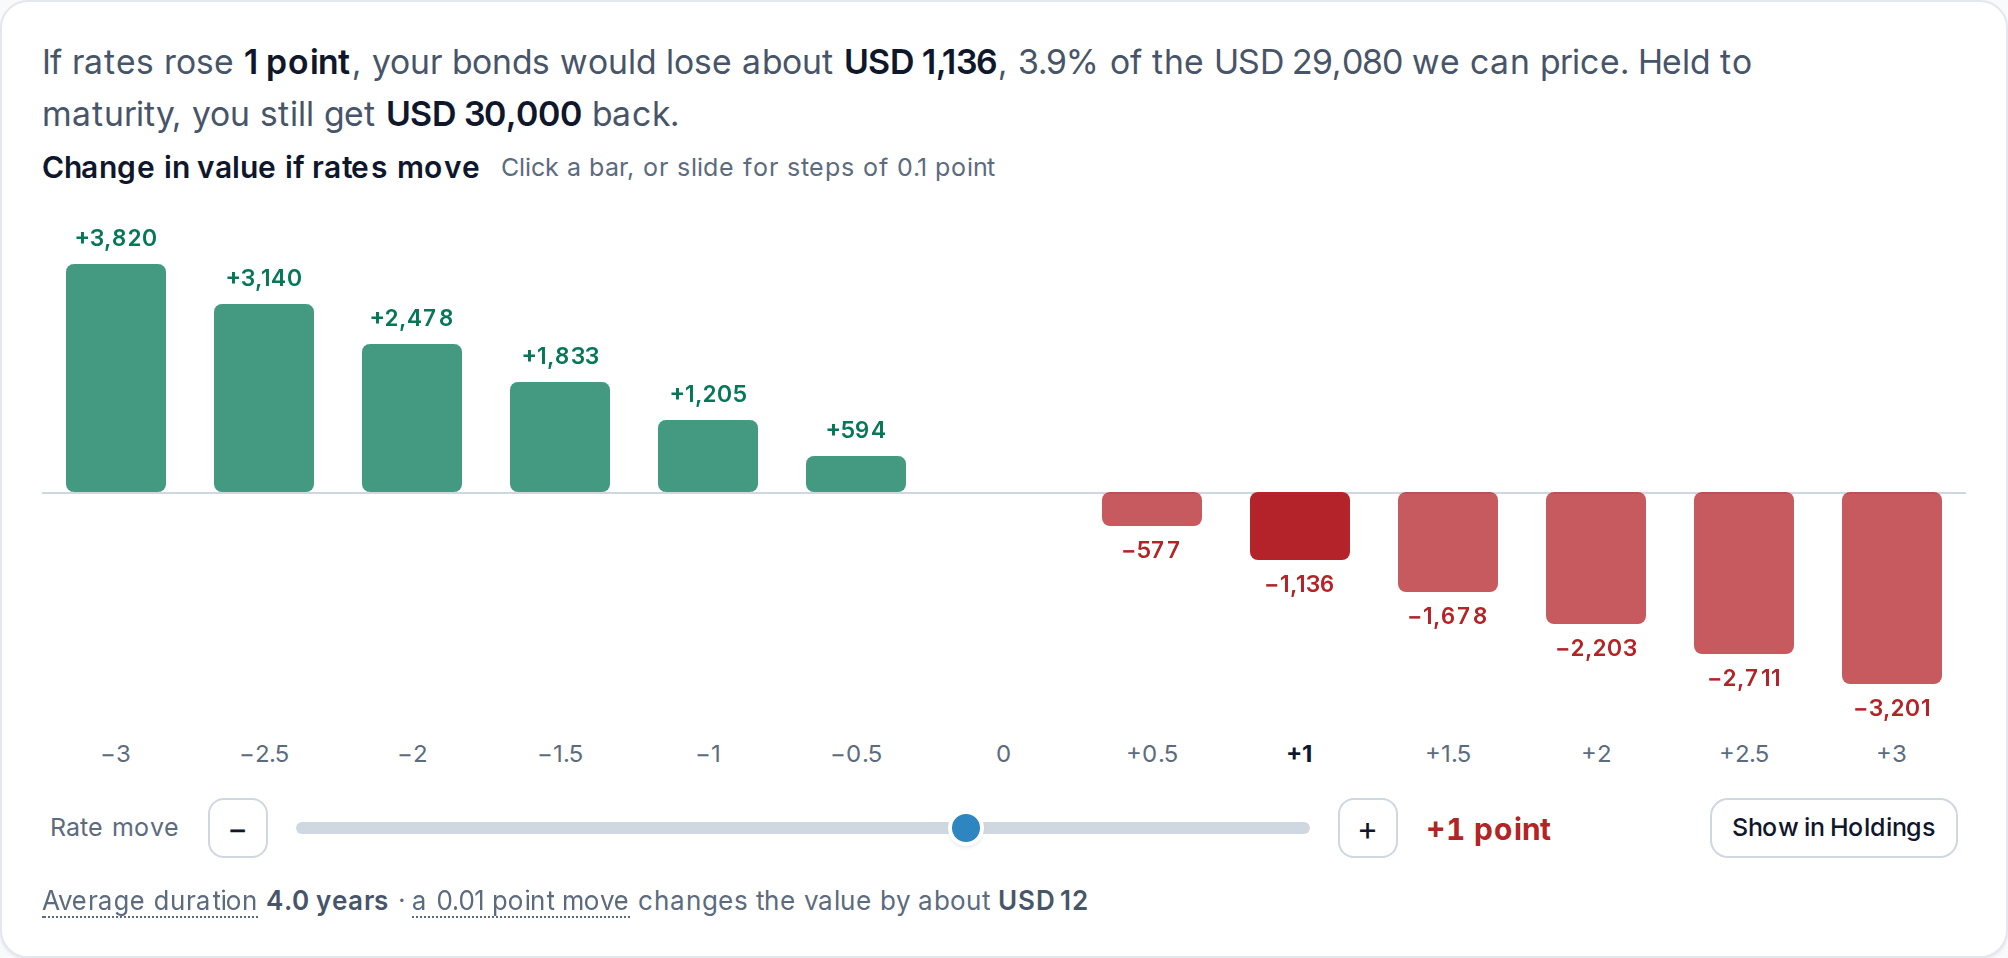
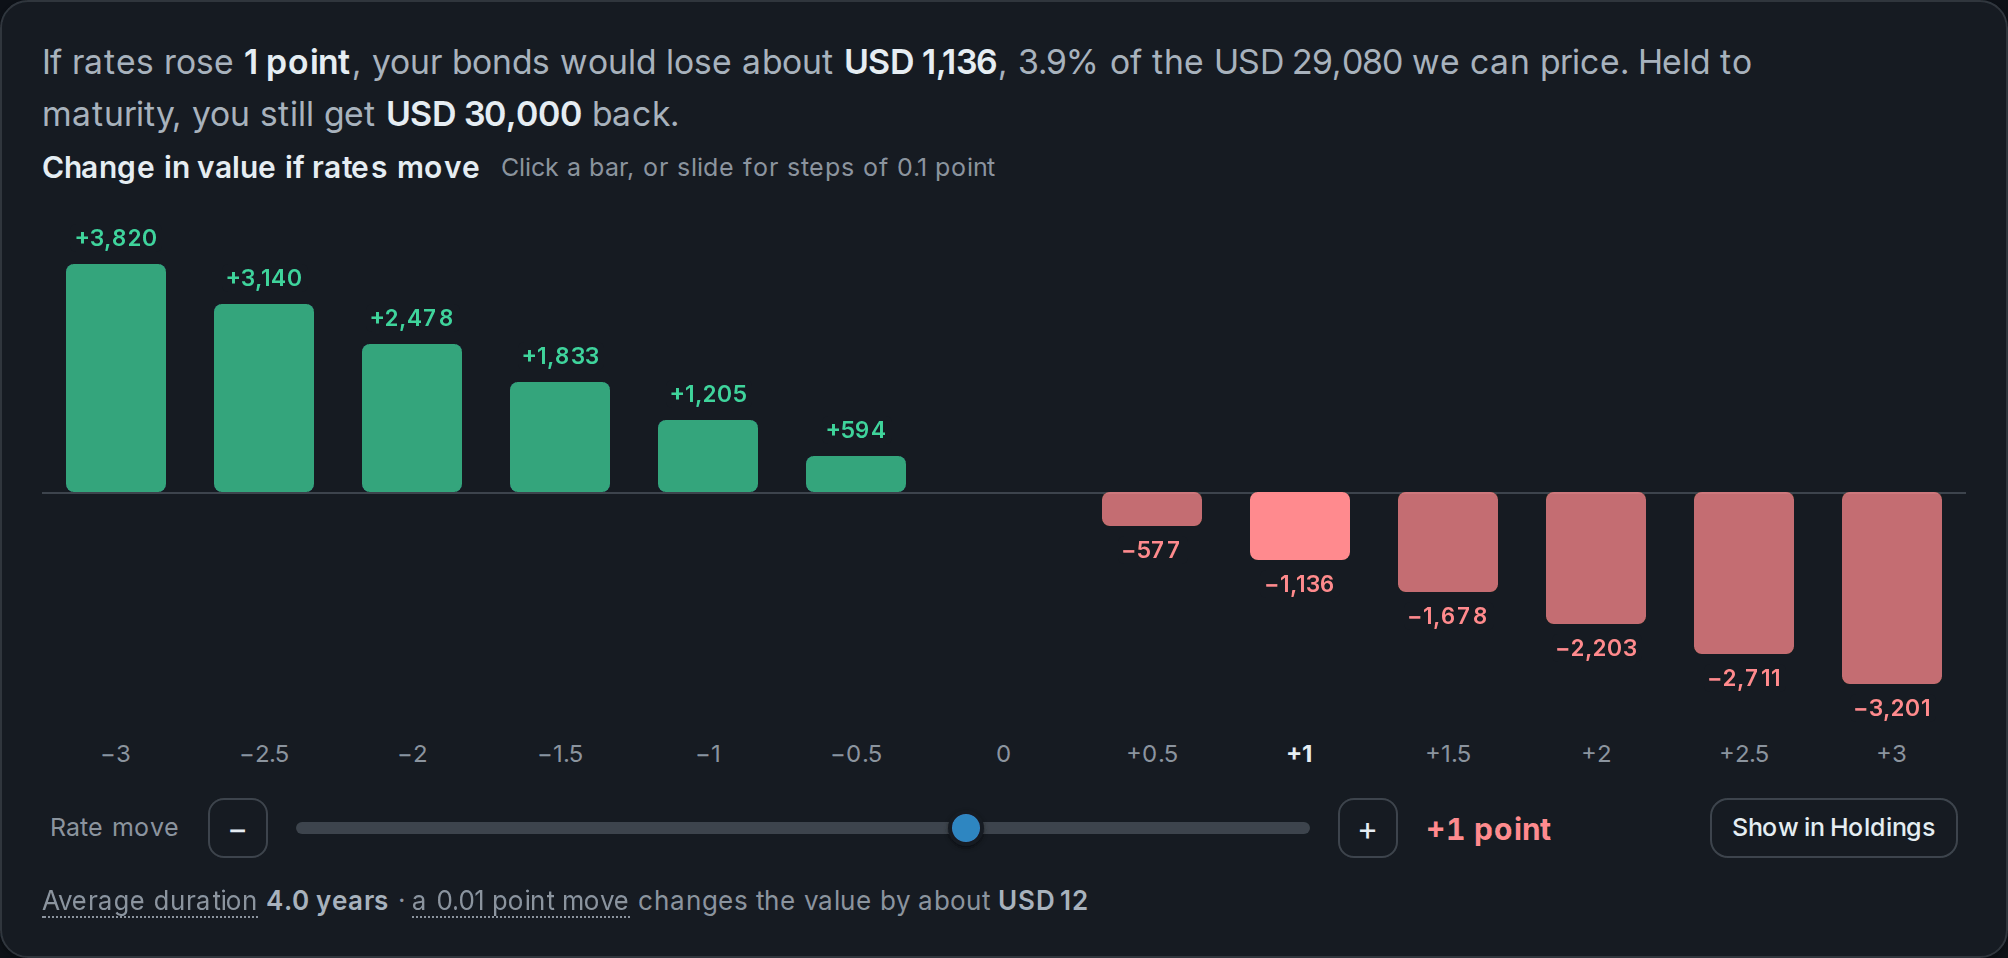
The Risk tab prices every bond again for rate moves from −3 to +3 points and shows the gain or loss in your currency. It also shows the book's average duration and what a 0.01 point move is worth, the same duration idea as above, added up across your bonds. Next to it, the amount you still get back if you hold every bond to maturity.

See the bond tracker
AllInvestView Change in value if rates move: a 1 point rise would lose about USD 1,136, 3.9% of USD 29,080, with USD 30,000 back at maturity; bars from +3,820 at minus 3 points to minus 3,201 at plus 3 points; average duration 4.0 years Change in value if rates move: a 1 point rise would lose about USD 1,136, 3.9% of USD 29,080, with USD 30,000 back at maturity; bars from +3,820 at minus 3 points to minus 3,201 at plus 3 points; average duration 4.0 years
A demo book of three example bonds: a 1 point rise would cost about USD 1,136.View full-size View full-size

Bond questions

What is a bond in simple terms?

A loan you make to a government or a company. It pays you interest, called the coupon, on fixed dates and gives your money back on a set day, the maturity date. You can hold it to that day or sell it earlier at whatever the market pays.

How do bonds make money?

Two ways. The coupons, paid usually every six months, and any difference between the price you paid and what you get back. A bond bought at $97 that repays $100 earns the $3 on top of its coupons. Selling before maturity can add a gain or a loss, depending on how rates have moved.

Can you lose money on bonds?

Yes, in two ways. If rates rise, the price falls, so selling early can lock in a loss: total bond market funds lost about 13% in 2022. And if the issuer defaults, you may get back less than you lent. A US Treasury held to maturity pays every coupon and the full face value.

Are bonds a good investment right now?

The best guide to what a high-quality bond will earn over its life is its yield when you buy it. On 23 October 2026 the 10-year Treasury yielded 5.00%, against 1.63% at the start of 2022. A higher starting yield means more income and more room to absorb a rise in rates.

How much money do you need to buy bonds?

Treasuries start at $100 at TreasuryDirect and usually $1,000 at a broker. Corporate and municipal bonds usually trade in $1,000 pieces, often with a higher minimum order. A bond ETF costs one share, so you can start with less; mutual funds set their own minimum.

What is the difference between the coupon and the yield?

The coupon is fixed when the bond is issued: 4.625% of face value a year on the August 2036 Treasury. The yield is what you earn at today's price. Buy below face value and the yield is higher than the coupon; above it and the yield is lower.

Are individual bonds or bond funds better?

A fund is simpler and spreads the risk across thousands of bonds for a small yearly fee, but most never mature, so there is no date when you are sure to get your money back. Individual bonds give you known payments and a known end date, which suits money you need on a specific day.

Every bond, coupon and maturity in one place

Link your brokers or add your bonds by ISIN or CUSIP, and AllInvestView tracks their yield, coupons, rate risk and maturities next to the rest of your portfolio.

Create a free account

Related calculators and guides

Sources

Bond prices are worked out from each note's coupon schedule at the yields shown, as our bond calculator does. Fund returns are daily closes with distributions reinvested to 23 October 2026. Checked on 26 October 2026; this page explains bonds in general terms.