Ten years of saving
Builds $51,316 by 35, then adds nothing for 30 years.
- Put in
- $36,000
- At 65
- $390,627
Compound interest means you earn interest on your interest. Each year's gain is added to the balance, so next year's percentage works on a bigger number. $10,000 at 7% a year grows to $19,672 in 10 years, $38,697 in 20 and $76,123 in 30. With simple interest, paid only on the original $10,000, it would be $31,000 after 30 years.
Reinvesting the dividends was worth about $57,000 more than taking them as cash. That gap is compounding: each dividend bought shares that paid dividends of their own.
Enter what you start with, what you add each month and the yearly rate. You'll see the balance, how much of it is growth, and what it's worth in today's money.
| Year | Put in | Growth | Balance |
|---|
The calculator works month by month: the yearly rate becomes an effective yearly rate for the compounding you pick, then a monthly growth factor, and each month's addition goes in at the end of the month. With compounding left on yearly it uses the same maths as the goals planner in AllInvestView. Returns from shares vary from year to year, so the result is what a steady rate would give, not a forecast.
One formula for a lump sum, a second for money you add on a schedule. Add the two together for a plan like the calculator's.
A = P (1 + r/n)nt
Worked through: $10,000 at 7% compounded monthly for 10 years is 10,000 × (1 + 0.07/12)120 = 10,000 × 2.00966 = $20,096.61. Compounded once a year it would be $19,671.51.
The interest alone is A − P: $10,096.61 here.
FV = PMT × ((1 + r/n)nt − 1) ÷ (r/n)
Worked through: $500 a month at 7% compounded monthly for 30 years is 500 × (1.0058333360 − 1) ÷ 0.0058333 = $609,985. Add the $10,000 starting amount grown the same way, $81,165, and you have $691,150 from $190,000 put in. Set the calculator's compounding to monthly to see the same figure.
In a spreadsheet: =FV(7%/12, 360, -500, -10000) gives $691,150 in Excel and Google Sheets. The minus signs mark money going in.
Simple interest is paid on the original amount only. Compound interest is paid on the growing balance, so the gap between them widens every year. How often it compounds matters much less.
After 40 years compounding has produced $139,745 of interest against $28,000 for simple interest. Years 31 to 40 alone add $73,622.
| Compounded | APY | After 10 years |
|---|---|---|
| Yearly | 4.00% | $14,802.44 |
| Quarterly | 4.06% | $14,888.64 |
| Monthly | 4.07% | $14,908.33 |
| Daily | 4.08% | $14,917.92 |
Divide 72 by the yearly rate to get the years it takes to double. It's a mental shortcut for the formula above, and close enough for planning. More in the rule of 72 glossary entry.
| Rate | Rule of 72 | Exact |
|---|---|---|
| 2% | 36 | 35.0 |
| 4% | 18 | 17.7 |
| 6% | 12 | 11.9 |
| 7% | 10.3 | 10.2 |
| 8% | 9 | 9.0 |
| 10% | 7.2 | 7.3 |
| 12% | 6 | 6.1 |
Exact years are log 2 ÷ log (1 + rate), with the rate compounding once a year.
At 10.1% a year the rule says a double every 7.1 years. The $10,000 from 1996 doubled a little over four times in 30 years, but not evenly:
Values each October with dividends reinvested. Markets compound in bursts: the ten years from October 1999 lost 10%, the ten from October 2009 gained 258%.
Three people put $300 a month into the same fund earning 7% a year. The only difference is when they start and stop. Each is valued at 65.
Builds $51,316 by 35, then adds nothing for 30 years.
Puts in three times as much and still finishes behind.
The first two added together: the early decade does most of the work.
Monthly additions at the end of each month, 7% a year compounding yearly, no fees or tax. If you're starting later, adding more each month and keeping costs low are what close the gap; the dollar-cost averaging guide covers investing a fixed amount on a schedule.
Anything that takes a slice of the return every year takes it from all the later years too. Using the calculator's first example, $10,000 plus $500 a month for 30 years at 7%:
A fund charging 1% a year instead of 0.03% leaves you with $544,691 instead of $656,989.
At 2.5% inflation, the $660,849 you'd have in 30 years buys what $315,055 buys today. US prices rose 2.1 times from October 1996 to September 2026.
Tax on dividends and interest each year leaves less to reinvest. A 401(k) or IRA in the US, an ISA in the UK or a TFSA in Canada shelters your returns from that yearly tax. See how dividends are taxed.
Up 50% one year and down 50% the next averages 0%, but $10,000 becomes $7,500. The compound rate is −13.4% a year. Losses cost more than the same-sized gains earn.
A calculator assumes a steady rate. Your portfolio gets a real one, with deposits on different dates and dividends paid along the way. AllInvestView shows you both.
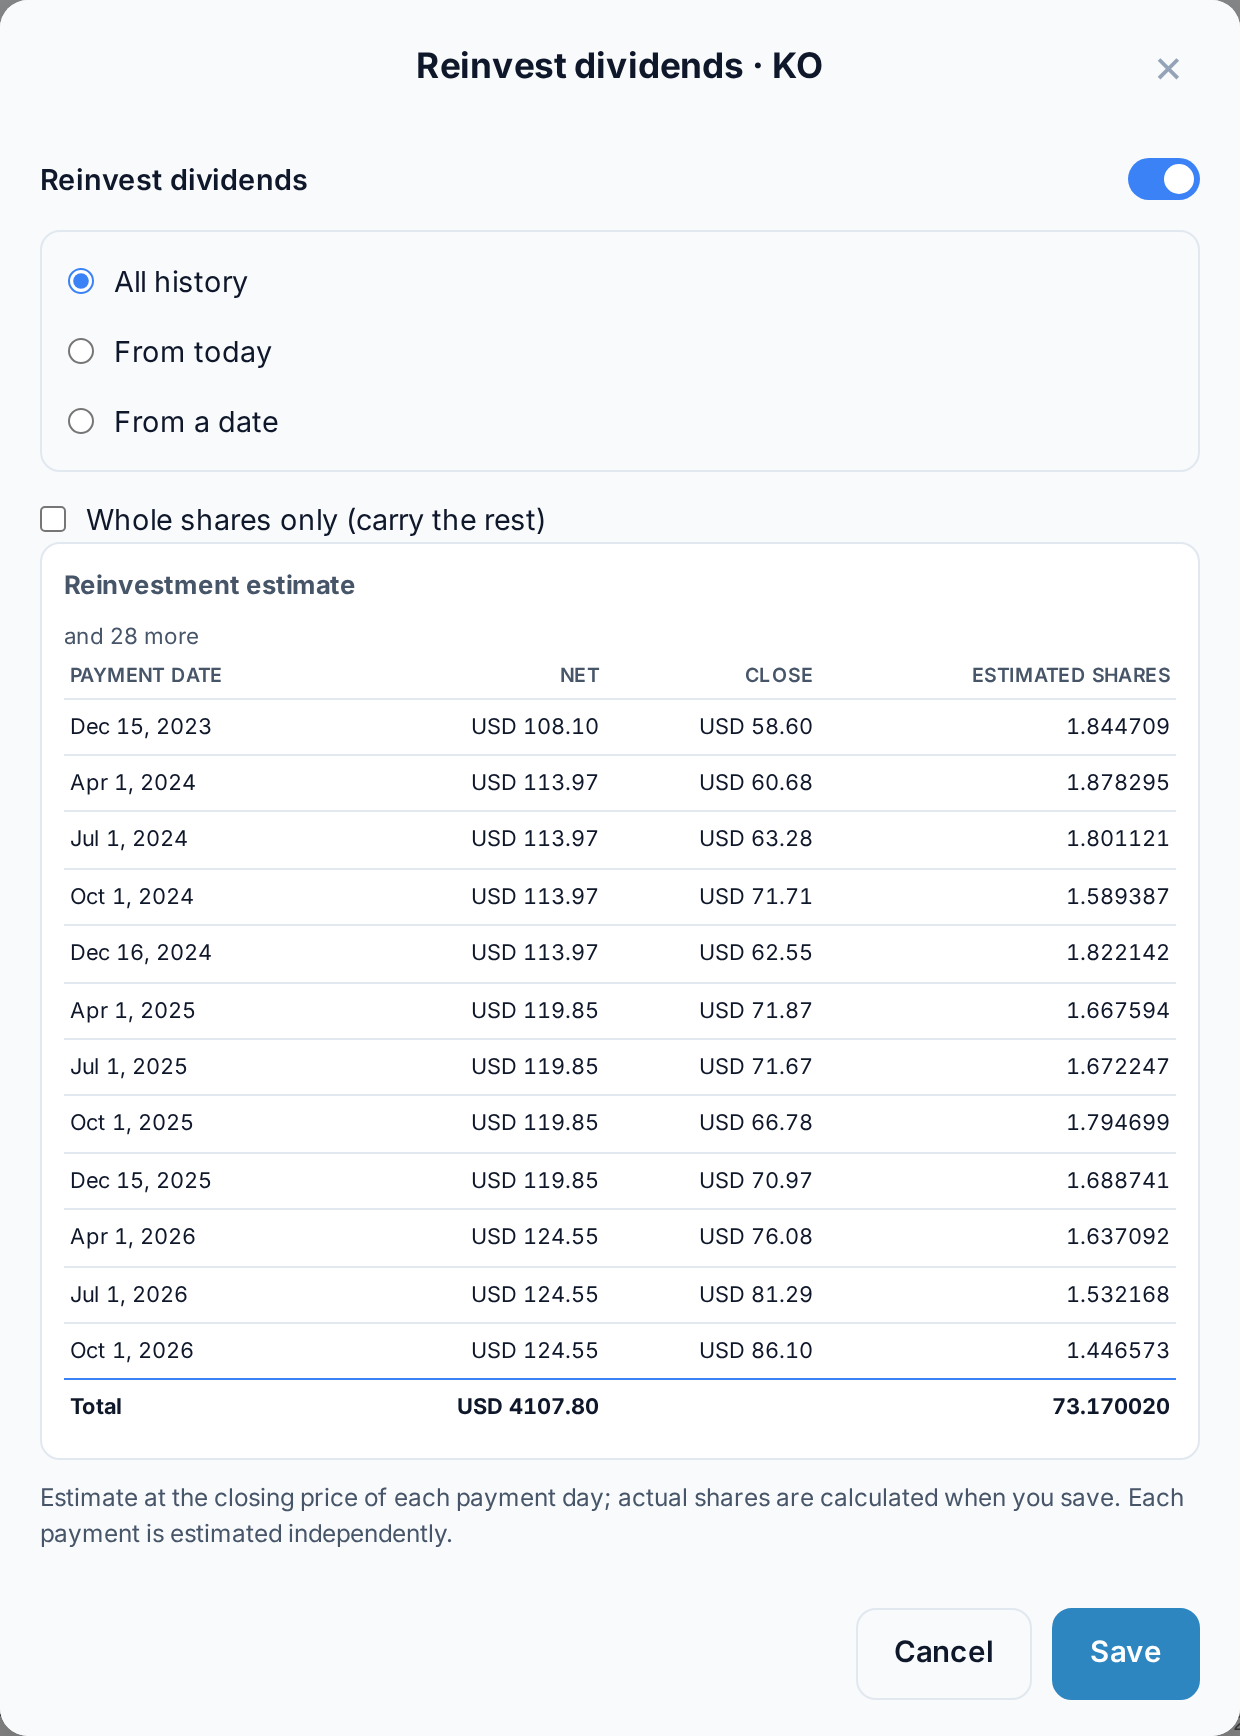
Broker reinvestments come in as purchases with their own price and quantity. For a holding you track by hand, turn reinvestment on and each dividend books the shares it bought, priced on its own date. Those shares then earn the dividends after them, as in the S&P 500 example above.
Read the DRIP guide AllInvestView
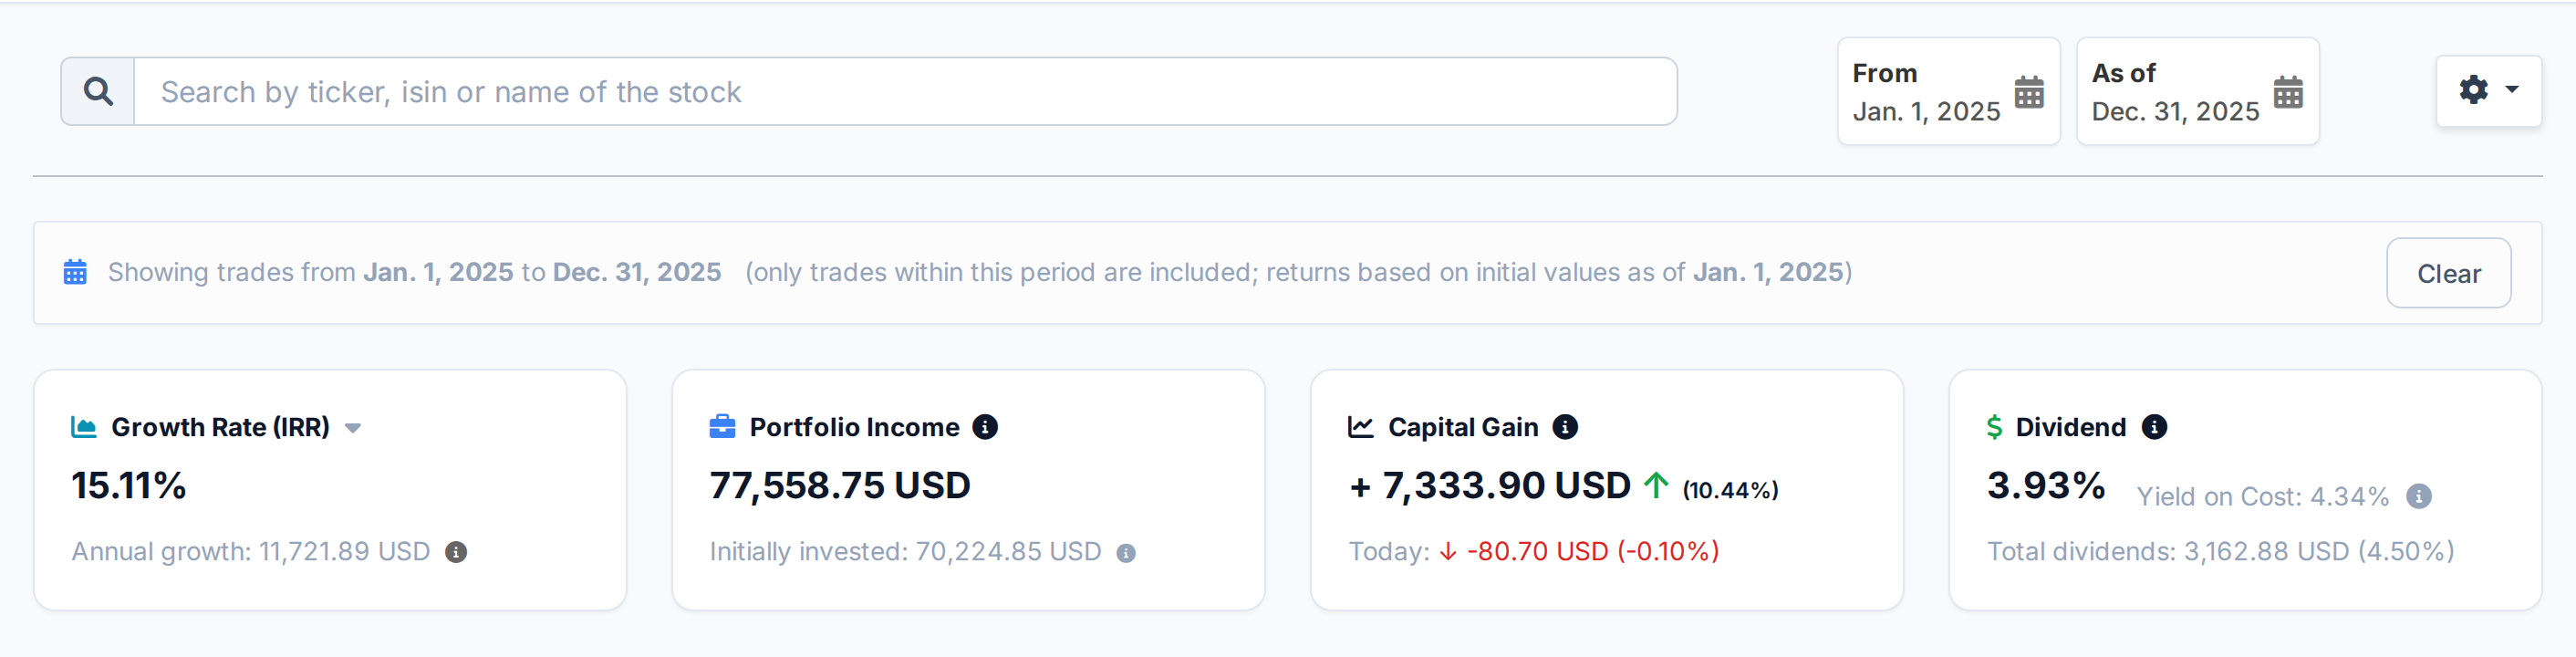
Each portfolio shows its IRR: the yearly compound rate that matches what you put in, when you put it in and what it's worth now. Pick any two dates to see it for that stretch, next to the capital gain and the dividends. That's the number to put in the calculator above.
How portfolio returns are measuredAllInvestView
Multiply the starting amount by (1 + r/n) raised to the power n × t, where r is the yearly rate, n the number of times it compounds a year and t the number of years. $10,000 at 7% compounded monthly for 10 years is 10,000 × (1 + 0.07/12)^120 = $20,096.61. In Excel or Google Sheets, =FV(7%/12, 120, 0, -10000) gives the same answer.
APR is the stated yearly rate. APY is what you actually earn in a year once the interest has compounded: 4% compounded daily is an APY of 4.08%. US banks have to quote APY on savings accounts and CDs, which makes accounts that compound differently easy to compare.
Divide 72 by the yearly rate. At 7% that gives about 10.3 years; the exact answer is 10.24. The rule is close between about 6% and 10% and drifts further off at very low or very high rates.
Stocks don't pay interest, but the same thing happens when you reinvest dividends and leave gains invested. $10,000 in the S&P 500 (SPY) at the end of October 1996 was worth about $180,600 on 26 October 2026 with dividends reinvested, against $108,000 of shares plus $15,350 paid out if you'd taken the dividends as cash. The difference is the dividends earning returns of their own.
For savings, use the account's APY. For a stock portfolio, a figure below the market's past is the careful choice: SPY returned 10.1% a year over the 30 years to October 2026, or about 7.4% a year after US inflation. Returns jump around from year to year, so treat any single rate as a planning figure, not a forecast.
$10,000 at 4% for 10 years is $14,908.33 compounded monthly and $14,917.92 compounded daily, a difference of $9.59. Beyond monthly the frequency barely matters; the rate and the number of years matter far more.
Yes. Interest you don't pay is added to what you owe and then charged interest too, which is why a credit card balance left alone grows quickly. Paying down high-rate debt earns you that rate, guaranteed, which is hard to match by investing.
Link your brokers or import your trades. AllInvestView keeps your return, dividends and reinvestments up to date across all your accounts and currencies.
Checked on 27 October 2026. Past returns don't tell you what markets will do next. This page explains how compounding works and isn't advice to buy or sell any investment.