The loss waits in the new shares
$1,534.24federal tax for 2026The $1,994.60 loss is added to the cost of the 20 shares bought back, and the 182 days you held the old shares count toward the new ones.
You report the stocks you sold, not the ones you hold. Every sale on your broker's Form 1099-B ends up on Schedule D: straight onto line 1a or 8a when the broker reported your cost and nothing needs fixing, or through Form 8949 when something does, like a wash sale, a missing cost or a sale with no 1099-B. Dividends from your 1099-DIV go on Form 1040 lines 3a and 3b, even the ones you reinvested. There's no minimum: a $40 sale is reported like a $40,000 one.
Here it is on a real year: in 2026 you sell 40 Apple shares bought in 2021, 50 Nvidia shares bought in February, and 20 Tesla shares at a loss that you buy back 29 days later.
40 shares bought at $129.41 on 4 January 2021, sold at $306.31 on 1 June 2026.
50 shares bought at $185.61 on 2 February, sold at $224.36 on 1 June.
Sold on 3 August, bought back on 1 September. The loss moves into the new shares.
Line 16 is $9,013.50; SCHD dividends $310.60 at 15%.
Your broker sends one consolidated 1099 with a 1099-B for sales and a 1099-DIV for dividends. Each line on it takes one of these routes.
One line per sale.
The year's dividends and fund payouts.
Box 12 checked, box 1g empty, and the 1099-B figures are right.
Totals straight to Schedule D line 1a or 8aA wash sale, a wrong or missing cost, a fee or premium left out, or a sale with no 1099-B.
One row each on Form 8949, boxes A to FOrdinary and qualified dividends, then any capital gain distributions from funds.
Form 1040 lines 3a and 3b · Schedule D line 13Form 8949 has six boxes for stock: A, B and C for short-term sales, D, E and F for long term. A and D are sales whose cost the broker reported to the IRS, B and E are sales where it didn't, and C and F are sales with no 1099-B at all. Crypto reported on the new Form 1099-DA has its own boxes, G to L. Ordinary dividends over $1,500 also need Schedule B.
Only when something happens: a sale, or a payment to you. Owning shares that went up is not a taxable event.
The three sales from the top of the page in Form 8949's columns, at the real closing price on each date, and where each one goes.
| Sale (a) description | Bought (b) | Sold (c) | Proceeds (d) | Cost (e) | Code and adjustment (f) and (g) | Gain or loss (h) | Goes on |
|---|---|---|---|---|---|---|---|
| 01/04/2021 | 06/01/2026 | $12,252.40 | $5,176.40 | none | +$7,076.00 | Long line 8a | |
| 02/02/2026 | 06/01/2026 | $11,218.00 | $9,280.50 | none | +$1,937.50 | Short line 1a | |
| 02/02/2026 | 08/03/2026 | $6,441.60 | $8,436.20 | W +$1,994.60 | $0.00−$1,994.60 before W | Short 8949 box A |
Apple and Nvidia need no Form 8949: the broker reported their cost and nothing changes. Tesla has an amount in box 1g, so it takes a Form 8949 row.
Single filer with $90,000 in wages, so $73,900 taxable before the investments. SCHD paid $310.60 through September on 400 shares held since 2024, counted here as qualified.
Buying the same stock within 30 days before or after a loss sale blocks the loss for now. Tesla was sold on 3 August and bought back on 1 September, day 29.
The $1,994.60 loss is added to the cost of the 20 shares bought back, and the 182 days you held the old shares count toward the new ones.
The loss cancels Nvidia's gain and the last $57.10 comes off Apple's. Line 7 is −$57.10, line 16 $7,018.90, and federal tax $434.81 lower this year.
The higher cost shrinks the gain or grows the loss on the replacement shares. Sell them in 2027 and the $1,994.60 counts then.
A buy in another broker, your IRA or your spouse's account can wash a loss, and the 1099-B often leaves it out. Add any it missed with code W. A buy in an IRA loses the deduction for good.
The wash sale tracker checks the 61 days around a loss across every account, and the tax-loss harvesting guide covers selling losses on purpose.
A consolidated 1099 can run to dozens of pages. These are the boxes that decide your return.
| Box | What it holds | What you do with it |
|---|---|---|
| 1099-B box 1d and 1e | Proceeds and cost basis of each sale | Column (d) and (e) of Form 8949, or the line 1a and 8a totals |
| 1099-B box 1g | Wash sale loss disallowed | Form 8949 with code W, the amount in column (g) |
| 1099-B box 2 | Short term or long term | Part I or Part II of Form 8949, lines 1 to 3 or 8 to 10 of Schedule D |
| 1099-B box 12 | Basis reported to the IRS | Checked: box A or D. Not checked: box B or E, and you supply the cost |
| 1099-DIV box 1a and 1b | Ordinary dividends, and the qualified part | Form 1040 line 3b and 3a; Schedule B when 1a tops $1,500 |
| 1099-DIV box 2a | Capital gain distributions from funds | Schedule D line 13, as long-term gain |
Box numbers from the 2025 forms; the IRS keeps them stable year to year. Cost basis rules and lot methods are in the cost basis guide; how options land on these forms is in how options are taxed.
Most errors come from a 1099-B that's right about the sale and wrong about the cost. These are the ones to check before you file.
The 1099-B often shows a cost of zero or only what you paid, because the rest was taxed as wages on your W-2. Leave it and you pay tax twice on the same income.
Fix: Form 8949 code B, so the wage income counts as cost.Shares bought before 2011, or moved from another broker without their history, come with box 12 unchecked and often no cost at all.
Fix: box B or E, and your own cost from the original broker's records.Brokers only have to match buys and sales inside the same account. A loss sold at one broker and bought back at another is a wash sale your 1099-B usually won't show.
Fix: add code W yourself and carry the loss into the new shares.Each reinvested dividend was taxed when it was paid and bought more shares. If your records miss those buys, the gain on the sale comes out too high.
Fix: keep every reinvestment as a purchase with its own cost.Fund reclassifications often land after the first statement, and brokers send corrected 1099s into March. File on the first version and a correction that changes your numbers means an amended return.
Fix: wait for the final version if your broker says one is coming.Long term means held more than a year: shares bought on 4 January 2021 are long term from 5 January 2022. Gifted and inherited shares follow their own rules.
Fix: check box 2 against your own purchase dates.You still report every sale, and the losses lower the tax on your gains, then on your wages.
Short-term losses come off short-term gains first and long-term off long-term, then the two totals offset each other. That's what happened to Apple's gain in the day 31 version above.
A net loss on Schedule D line 16 takes up to $3,000 off your other income, or $1,500 if you're married filing separately.
What's left goes to next year's Schedule D, lines 6 and 14, and keeps its short or long character until it's used. It doesn't expire during your lifetime.
Trades settle into the year by their trade date, so a sale on 31 December 2026 counts in 2026.
Large gains with nothing withheld can mean quarterly estimated tax, and the fourth payment for 2026 is due now.
Brokers send the 1099-B with the 1099-DIV and 1099-INT in one statement, usually by the middle of February.
Fund reclassifications and late cost data bring corrected statements. Your broker's site shows the latest version.
The return and any tax due. An extension moves the return to 15 October 2027, but not the payment.
Every country has its own form for share sales, and most of them want a cost worked out across all your brokers, not the one each broker sends you.
| Country | Where it goes on the return | How cost is worked out | Report |
|---|---|---|---|
| UKUnited Kingdom | SA108 capital gains summary | Same day, then 30 days, then the Section 104 pool | UK report |
| CACanada | Schedule 3 | Adjusted cost base pooled across all non-registered accounts | Canada report |
| AUAustralia | Item 18 for gains, items 11 and 20 for dividends | Parcels, losses before the CGT discount | Australia report |
| IEIreland | Form 11, or CG1 if you're not self-assessed; funds on Form 11 | Shares and funds under separate regimes | Ireland report |
| DEGermany | Anlage KAP and KAP-INV | FIFO, with the advance lump sum on funds | Germany report |
| ESSpain | Modelo 100, listed shares section | FIFO, with the repurchase rule | Spain report |
| FRFrance | Form 2074, then 2042 C | Weighted average purchase price | France report |
| ITItaly | RT section, or Quadro T on the 730 | Last in, first out for the shares you declare yourself | Italy report |
US citizens abroad still file Form 8949 and Schedule D, in dollars, at the exchange rate of each trade date. Sales at a foreign broker that sends no 1099-B go in box C or F.
One ledger for every broker you use, synced or imported from a file, with the tax forms built from all of it at once.
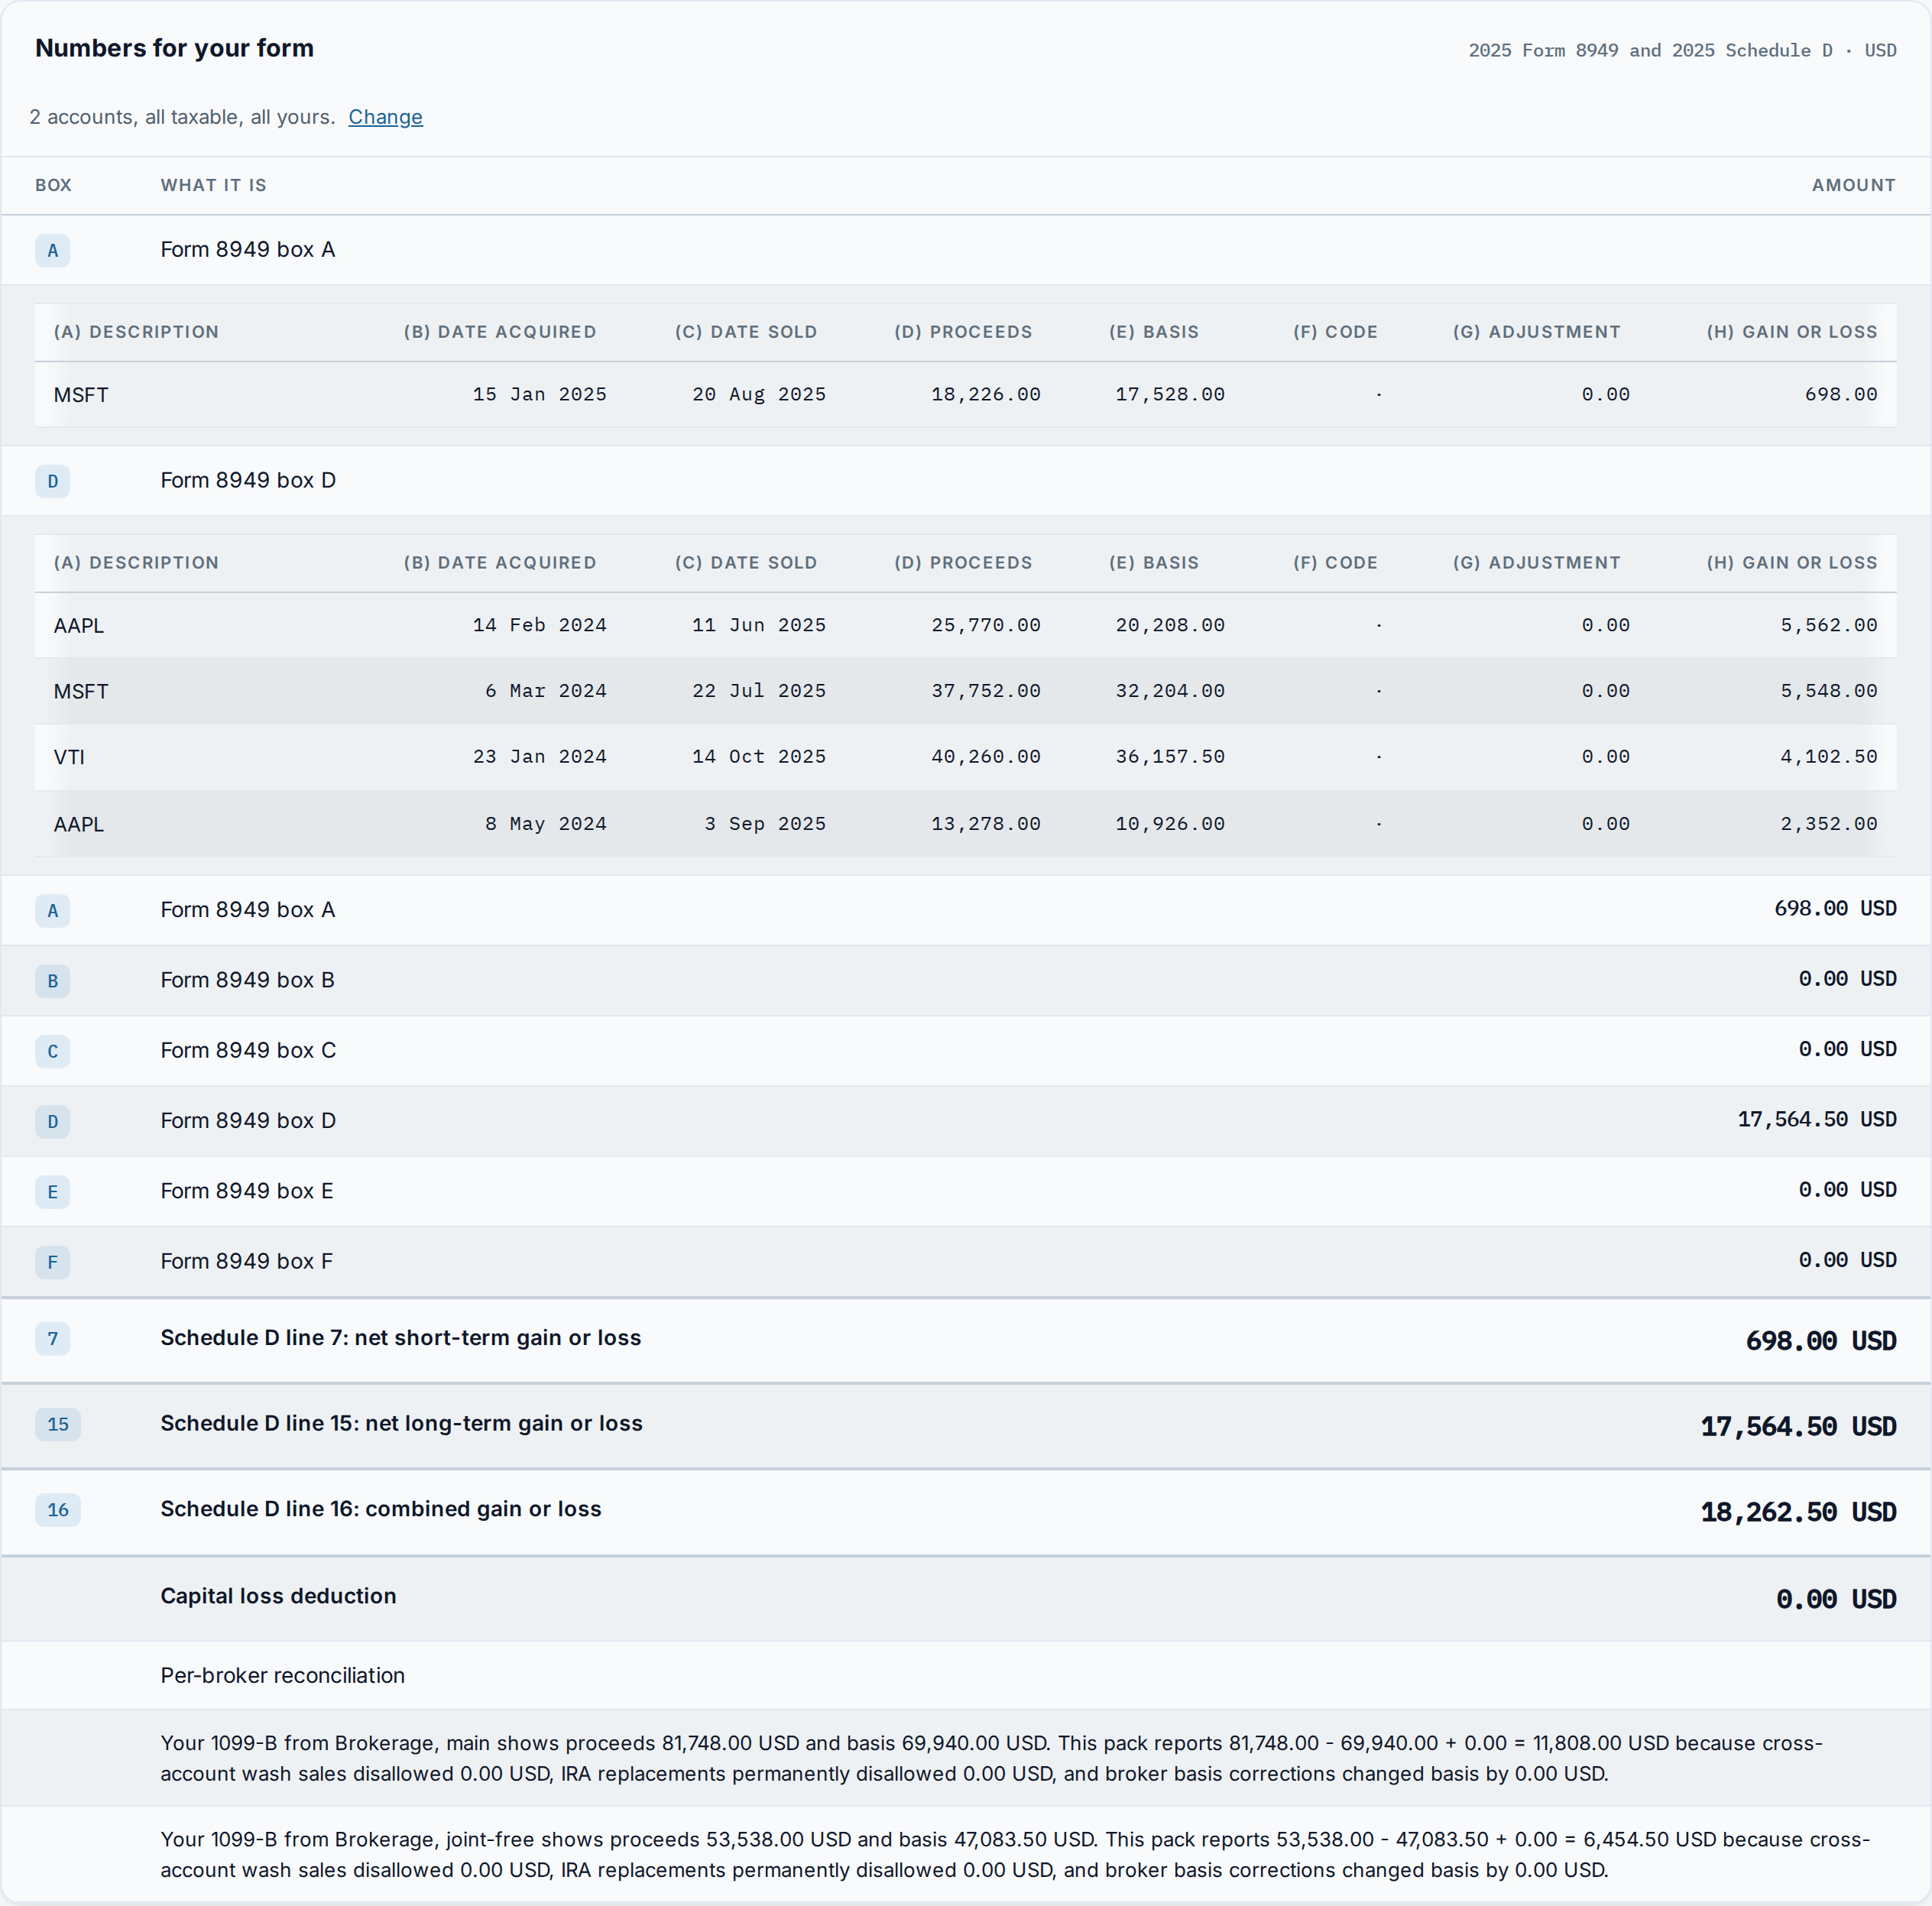
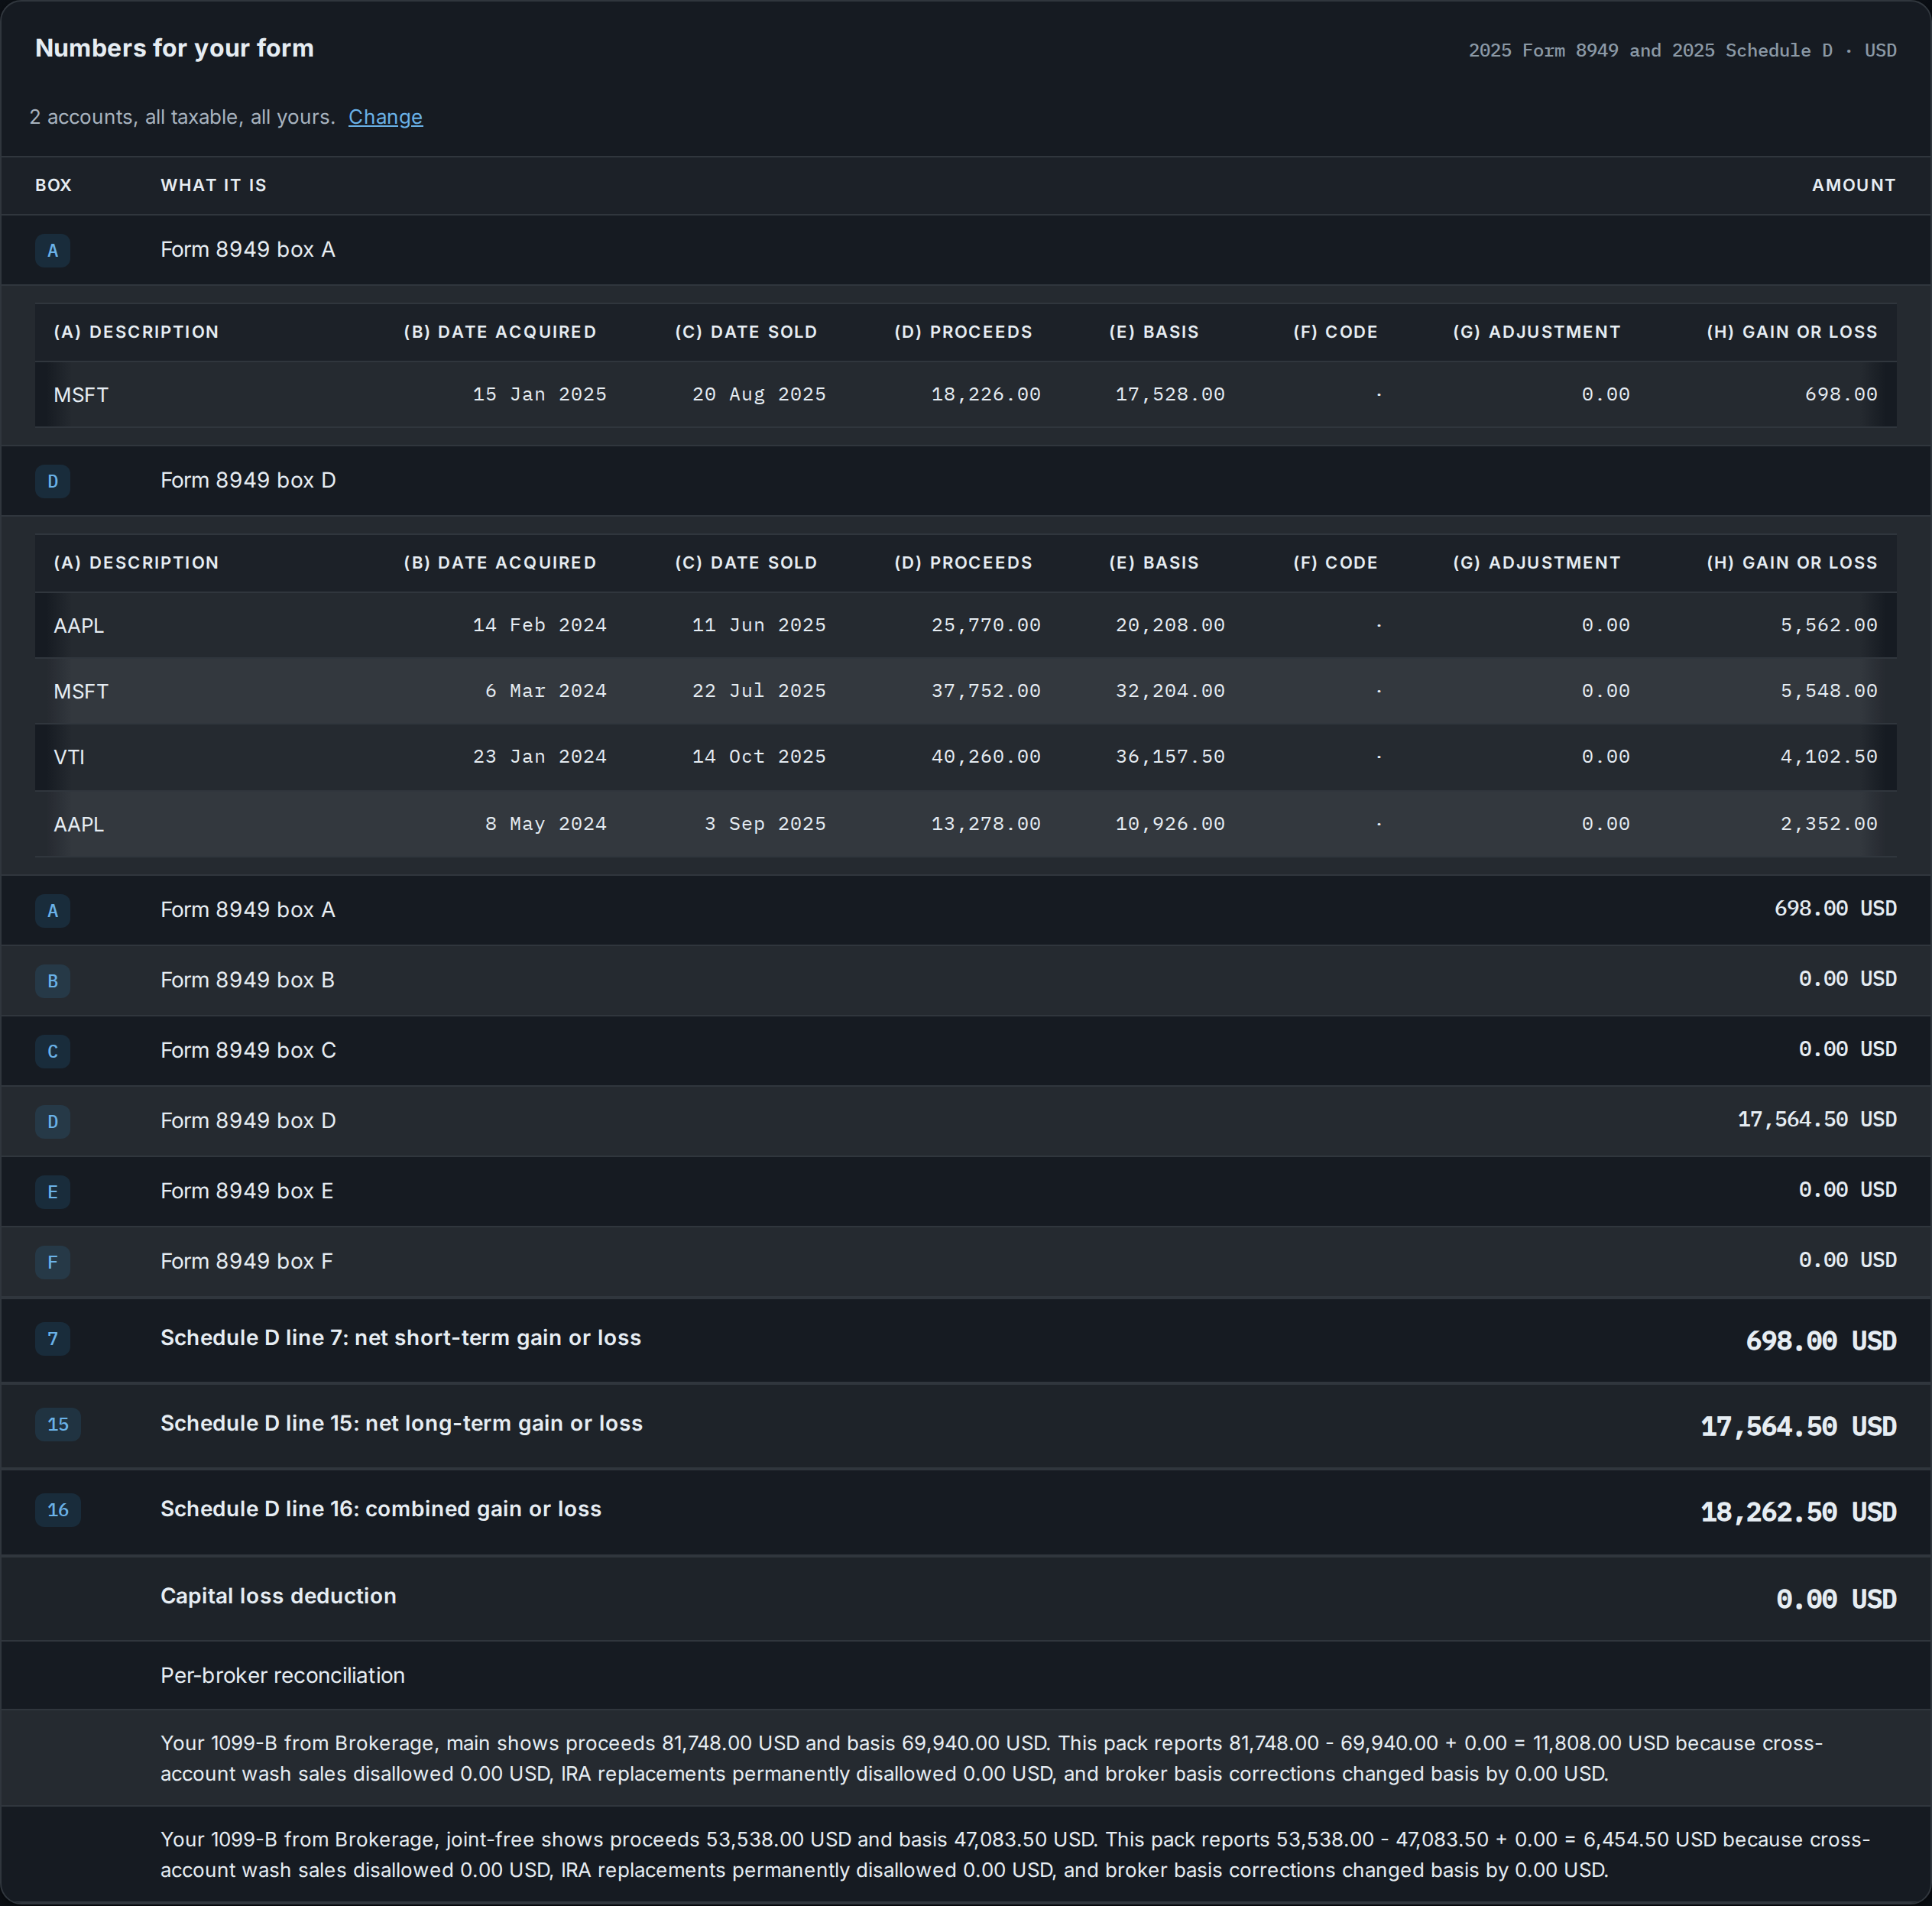
The pack sorts every sale into its Form 8949 box with all eight columns, adds the box totals, and fills Schedule D lines 7, 15 and 16. Then it reconciles each broker's 1099-B proceeds and cost to its own figures, in one sentence per broker, and says what made them differ.
The tax report with realized gains, dividends and an estimate of the tax is on the free plan for up to 10 holdings. The filing packs are on paid plans, with a 14-day free trial and no card.
AllInvestView
Stocks, ETFs, funds, options, bonds and dividends on one dashboard, synced from your brokers or imported from a file, with realized gains split short and long term.
No. Buying and holding shares isn't reported, however much they gained. You report sales, and you report dividends every year, including the ones you reinvested.
No. Every sale goes on your return, even a $40 one, and your broker sends the IRS a copy of the same 1099-B. Small sales your broker reported with their cost can go in the Schedule D line 1a or 8a total without their own line.
Not for sales whose cost the broker reported to the IRS (box 12 checked) with nothing in box 1f or 1g and no adjustment to make. Their totals go straight onto Schedule D line 1a for short term or 8a for long term. Everything else takes a Form 8949 row.
Like cash dividends: the 1099-DIV includes them in box 1a, and they go on Form 1040 line 3b, with the qualified part on line 3a. Each reinvestment also bought shares, so add it to your cost; otherwise the gain on a later sale comes out too high.
Report the sales anyway. Losses offset gains, and a net loss takes up to $3,000 a year off your other income, or $1,500 if you're married filing separately. The rest carries forward to later years.
The sale still goes on Form 8949, in box C for short term or box F for long term, with the proceeds and cost from your own records. Sales at a foreign broker that sends no 1099-B are reported this way, converted to dollars.
Check the cost on the 1099-B. It often leaves out the amount already taxed as wages on your W-2. Report the sale on Form 8949 with code B, so the amount already taxed as wages counts as cost and isn't taxed twice.
Most send a consolidated 1099 with the 1099-B, 1099-DIV and 1099-INT by mid-February, and corrected versions can follow into March. For the 2026 tax year the return is due on 15 April 2027.
Checked on 26 October 2026. Last updated 26 October 2026.
Commissions are left out. The tax figures use 2026 federal rates on top of $90,000 in wages for a single filer with the $16,100 standard deduction; state tax is not included.
This guide explains the federal rules in general terms. It isn't tax advice for your situation.