Dividend investing · updated October 2026

DRIP investing: how dividend reinvestment plans work

A DRIP, or dividend reinvestment plan, takes each cash dividend and buys more shares of the stock or fund that paid it, usually including a fraction of a share. Those new shares earn the next dividend, so the payments grow even if the company never raises them. Most brokers do it for free on dividend stocks and ETFs, and some companies run their own plan. One thing doesn't change: in a taxable account, a reinvested dividend is taxed like cash, and every reinvestment is a new purchase with its own cost basis.

235 Coca-Cola shares, reinvested for ten years24 Oct 2016 to 23 Oct 2026, real prices and dividends
Shares320.451From 235

40 dividends bought 85.451 more

Worth now$29,709vs $25,895 taking cash

$3,814 ahead

Yearly income$679vs $498 taking cash

At the $0.53 quarterly dividend

Still taxed$94.43On 2025's $629.52

Reinvested, never seen as cash

How a DRIP works

Here's the first payment in the example below, step by step.

  1. The dividend is paid

    Coca-Cola paid $0.35 a share on 15 December 2016. On 235 shares that's $82.25.

  2. It buys more shares

    Instead of landing as cash, the $82.25 buys KO at $41.55, the price that day: 1.9795 shares.

  3. The next one is bigger

    The next dividend is paid on 235 + 1.9795 shares, so it buys a little more, and so on, 40 times in ten years.

  4. Each buy is a tax lot

    Every reinvestment has its own date and price. That's what you'll need when you sell, and what the tax section below is about.

Ten years of Coca-Cola: reinvested vs taken as cash

235 KO shares bought at the close on 24 October 2016 for $10,001.60, held to 23 October 2026. Same shares, same 40 dividends, two choices.

What the position was worth at each year end

Reinvested: the shares, including those the dividends bought. Cash: the original shares plus every dividend collected so far.

  • Reinvested $29,709.05
  • Cash $25,894.65

On 23 October 2026, at $92.71

No new money in either case. Taxes are left out, as in an IRA; the next sections add them.

ReinvestedCash
Shares320.451235
Shares' value$29,709.05$21,786.85
Dividends collectedReinvested$4,107.80
Total$29,709.05$25,894.65
Dividends a year now$679.36$498.20

The 40 reinvestments used $4,875.18 of dividends and bought 85.451 shares, now worth $7,922.20. Taking the cash would have paid $4,107.80, less because each payment stayed at 235 shares.

Reinvesting isn't free money. It worked here because KO went from $42.56 to $92.71, so the shares the dividends bought rose too. In a stock that falls, reinvested dividends fall with it, and they make an already large position larger. Counting the cash dividends as they arrived, the annual return was 11.50% reinvested and 11.15% taking cash; without any dividends at all it would have been 8.09%.

Prices are each day's close; every dividend is reinvested at the close on its pay date, with fractional shares and no fees. Want to project your own numbers forward? The dividend calculator adds yearly contributions, dividend growth and tax.

Broker DRIP or company plan

There are two ways to reinvest. Most people use their broker's; the company plans are older and still run by the transfer agents for many large US companies.

At your brokerBroker reinvestmentWith the companyDirect plan, run by a transfer agent
How you joinA setting on the account or on each holding.Enroll with the plan's agent, such as Computershare or Equiniti. Shares sit in your own name, not the broker's.
What it reinvestsDividend stocks and ETFs the broker supports, often mutual funds too.That one company's shares.
CostFree at most large US brokers.Set by each plan: some charge per purchase or sale, some companies pay the fees, a few sell at a small discount.
When it buysOn or shortly after the pay date, at the market price.On the plan's purchase dates, sometimes at an average price over several days.
Extra purchasesOrdinary trades.Optional cash purchases, often from small minimums or by monthly debit.
SellingA normal trade.A request to the agent, filled on its schedule and fee.
RecordsOn your broker statements and one 1099.A separate statement and 1099 from each plan, kept for as long as you hold.

Taxes on reinvested dividends and the cost basis

In a taxable US account a DRIP changes nothing about the tax on the dividend. The IRS treats it as cash paid to you and then spent on shares. What it changes is the paperwork when you sell.

The 2025 tax on dividends you never saw

The same KO position in a taxable account. A single filer with $85,000 of other income; KO's dividends count as qualified.

  • Dividends paid in 20254 payments, all reinvested$629.52
  • On Form 1099-DIVBox 1a and box 1b, qualified$629.52
  • RateQualified dividends in the 15% band15%
  • Federal tax for 2025Paid from other money$94.43

The rate depends on your income. Work out yours with the dividend tax calculator, which separates qualified from ordinary dividends.

41 purchases, one position

The original buy plus 40 reinvestments. Each one's cost is the dividend it used.

DateSharesPriceCost
24 Oct 2016Purchase235$42.56$10,001.60
15 Dec 2016Reinvested1.9795$41.55$82.25
3 Apr 2017Reinvested2.0675$42.41$87.68
36 more reinvestments
1 Jul 2026Reinvested2.0631$81.29$167.71
1 Oct 2026Reinvested1.9605$86.10$168.80
Total320.451$14,876.78
Gain if all sold 23 Oct 2026$14,832.27

$29,709.05 less $14,876.78 of basis.

Reported with only the first buy$19,707.45

$4,875.18 taxed twice: about $731.28 extra at 15%.

Two more things change when you sell. The 4 reinvestments from the last twelve months (8.455 shares, from 15 Dec 2025) haven't been held more than a year, so their gain is short-term and taxed like salary. And you can choose which lots to sell: brokers report the basis of DRIP shares bought since 2012 on Form 1099-B and may let you use average cost for them, while older shares, company plans and accounts that moved brokers are where the records most often go missing. A reinvested dividend is also a purchase for the wash sale rule, so turn reinvestment off on a position you plan to sell at a loss.

United Kingdom

Reinvested dividends are taxed like any other dividends once you're past the £500 dividend allowance. The shares join your Section 104 pool at the amount reinvested, unless you sold the same shares that day or in the 30 days before: the same-day and 30-day rules match the reinvestment to that sale first. Inside an ISA or SIPP there's no tax on either. See the UK share CGT calculator.

Canada

Reinvested dividends are taxed in the year paid: with the gross-up and dividend tax credit if they come from Canadian companies, as foreign income if they come from a US stock like KO. Each reinvestment adds its cost to the shares' adjusted cost base, and forgetting them overstates the gain later. See the ACB calculator.

Australia

A dividend taken as DRP shares is still assessable income, franking credits included. The new shares' cost base is the dividend applied, and each allocation starts its own 12-month clock for the CGT discount. See the Australian CGT calculator.

Should you reinvest dividends?

Reinvesting is a good default while you're building a portfolio. It's a setting per holding, so you can keep it on for some and off for others.

Reinvest when

  • You don't need the income yet and the holding still fits your plan.
  • The account is an IRA, 401(k), Roth, ISA or TFSA, where reinvesting adds nothing to your tax return and leaves no lots to track.
  • You'd otherwise leave the cash sitting uninvested. Small dividends are hard to put to work by hand.

Take the cash when

  • You live on the income, or will soon.
  • The position is already too big: send the cash to what's underweight instead, which rebalances without selling.
  • You plan to sell at a loss within 30 days, to keep the wash sale rule away.
  • You'd rather not track dozens of small lots in a taxable account without a tool that does it for you.

DRIP stocks

Any stock or ETF that pays a dividend can be reinvested at a broker that offers it, so "DRIP stocks" mostly means companies with their own plan. Coca-Cola is one: its direct stock purchase and dividend reinvestment plan is administered by Computershare. Before joining any company plan, read its fee schedule; it varies from plan to plan.

Long dividend records

Companies that raise their dividend every year make the reinvested shares grow faster. Start from the dividend growth guide.

Dividend ETFs

A fund that pays quarterly reinvests the same way as a single stock, with fractional shares at most brokers, and spreads the bet across many companies.

Yield and safety

A high yield reinvested into a dividend that gets cut buys shares on the way down. Check the payout before the yield; see dividend yield.

Track reinvested dividends across every account

Broker reinvestments come into AllInvestView as purchases with their own price and quantity. For a holding you track by hand, turn reinvestment on and every paid dividend books the shares it bought.

Reinvest dividends

See every reinvestment before you save it

Turn it on for a holding and choose all history, from today or from a date. The estimate lists each payment, the closing price that day and the shares it buys, and you can keep whole shares only and carry the rest. Saving books the purchases in order, so each one also earns the dividends after it.

See the dividend tracker

AllInvestView AllInvestView Reinvest dividends window for KO with All history selected: a reinvestment estimate listing the last 12 of 40 payments, from 15 December 2023 to 1 October 2026, each with its net amount, closing price and estimated shares, totalling USD 4,107.80 and 73.170020 shares AllInvestView Reinvest dividends window for KO with All history selected: a reinvestment estimate listing the last 12 of 40 payments, from 15 December 2023 to 1 October 2026, each with its net amount, closing price and estimated shares, totalling USD 4,107.80 and 73.170020 shares
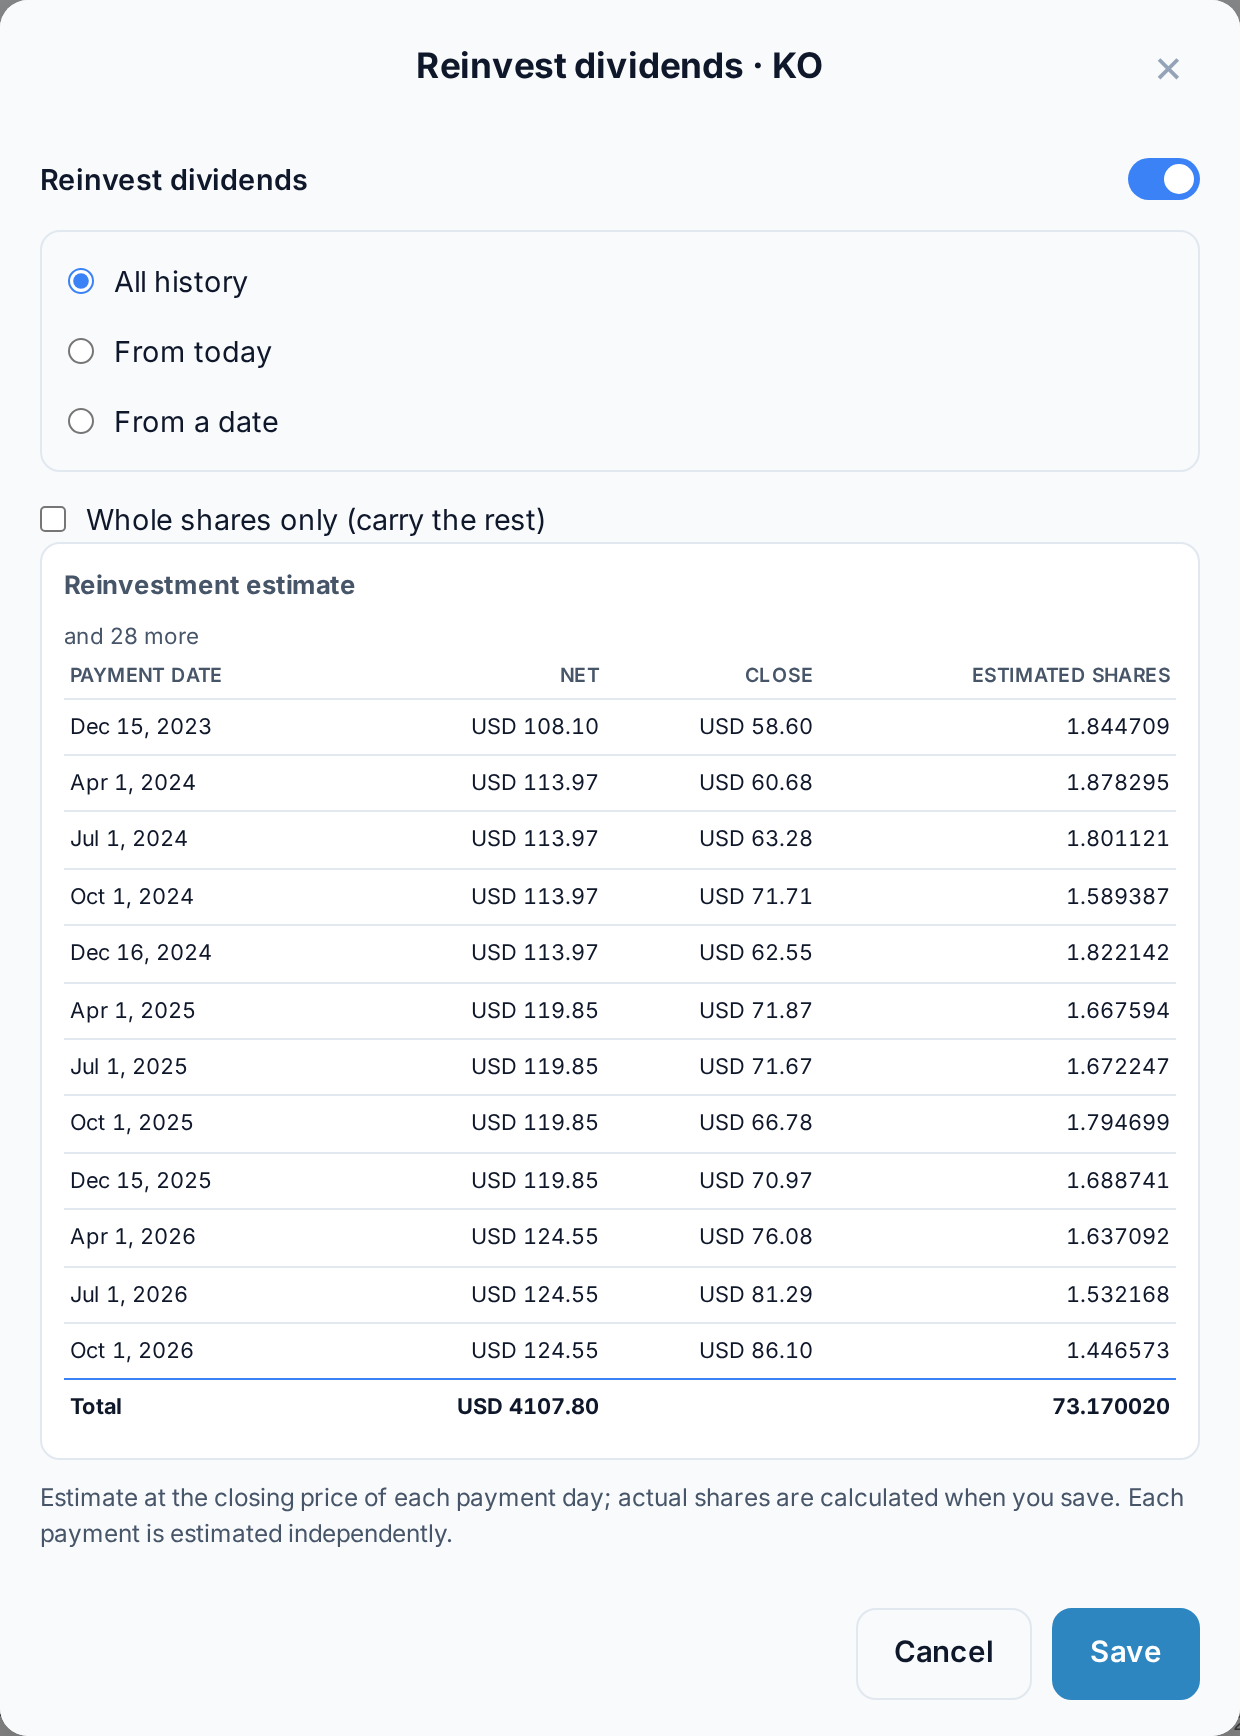
The estimate for the 235 KO shares in this guide: each of the 40 payments priced on its own, USD 4,107.80 in total. Saved, the reinvested shares also earn the later dividends.View full-size View full-size
Dividend report

Income that grows with the shares

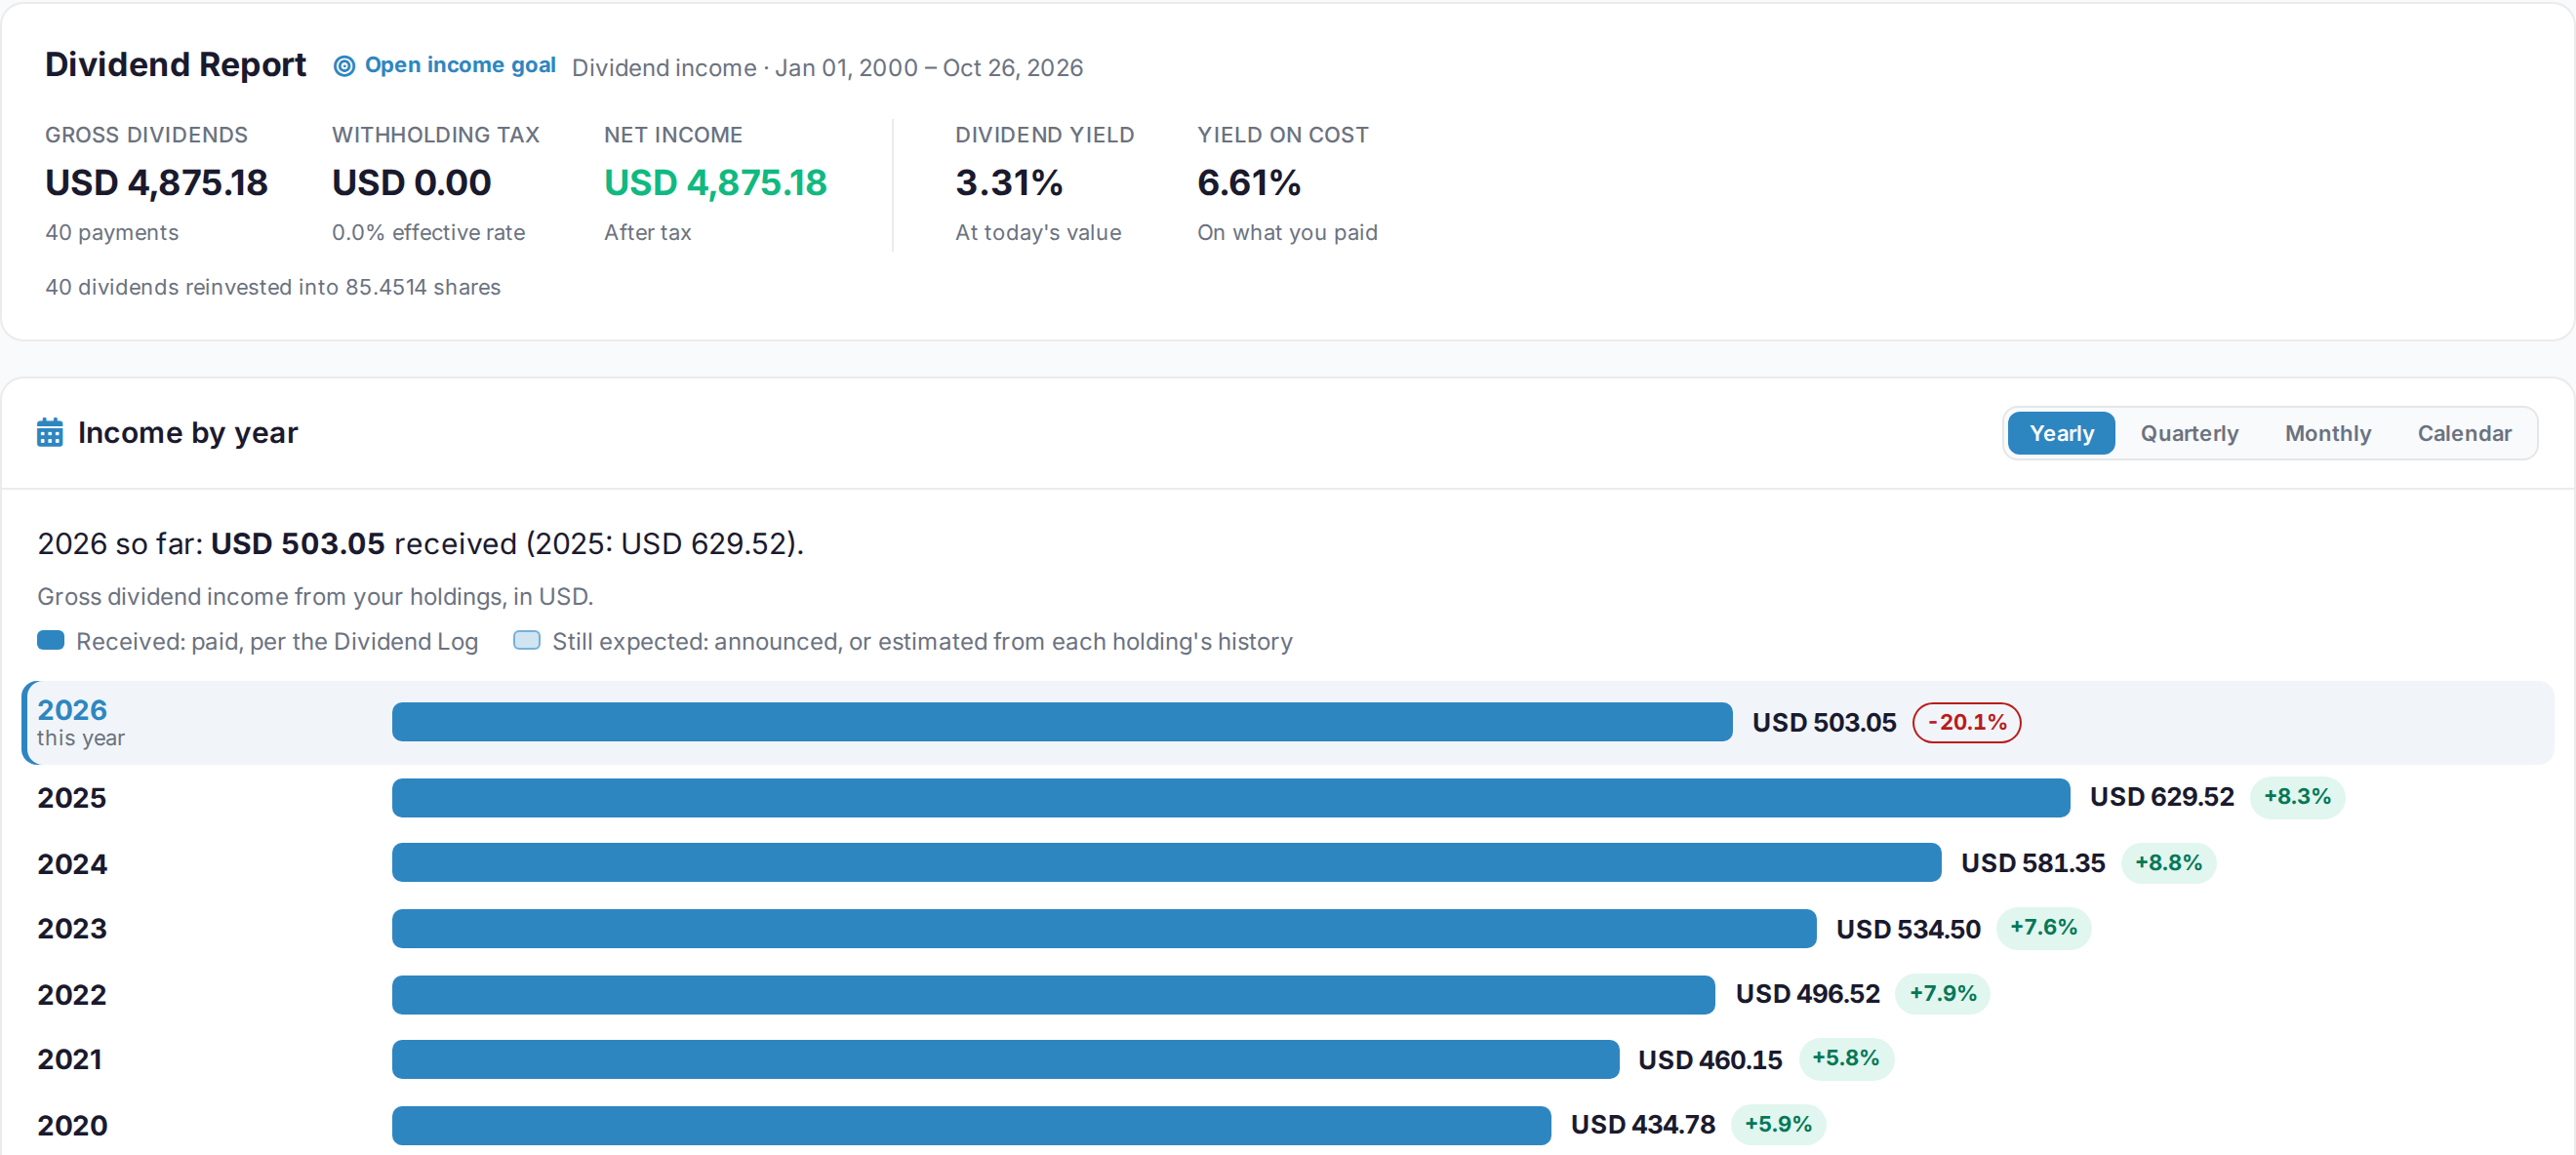
The dividend report counts what you were paid and how many shares it bought, with dividend yield and yield on cost. Income by year shows the payments rising as the reinvested shares add up, next to what's still expected this year. Each reinvested lot keeps its date and cost, so the tax report starts from the right basis when you sell.

See the dividend tracker
AllInvestView AllInvestView dividend report for the same KO holding after saving: gross dividends USD 4,875.18 over 40 payments, 40 dividends reinvested into 85.4514 shares, dividend yield 3.31%, yield on cost 6.61%, and income by year from USD 434.78 in 2020 to USD 629.52 in 2025 AllInvestView dividend report for the same KO holding after saving: gross dividends USD 4,875.18 over 40 payments, 40 dividends reinvested into 85.4514 shares, dividend yield 3.31%, yield on cost 6.61%, and income by year from USD 434.78 in 2020 to USD 629.52 in 2025
The same holding after saving: USD 4,875.18 of dividends over 40 payments, reinvested into 85.4514 shares, and 2025's USD 629.52, the figure taxed in the example above. Demo account, staged for this guide.View full-size View full-size

DRIP questions

What is a DRIP?

A dividend reinvestment plan, or DRIP, uses each cash dividend to buy more shares of the stock or fund that paid it, usually including a fraction of a share. Most brokers offer it free on dividend stocks and ETFs, and some companies run their own plan through a transfer agent.

Are reinvested dividends taxable?

Yes, in a taxable account. A reinvested dividend is taxed as if you'd been paid the cash and then bought the shares, so it's on your Form 1099-DIV for the year it was paid. In our example, Coca-Cola's 2025 dividends of $629.52 were all reinvested and still added $94.43 of federal tax. Inside an IRA, 401(k) or Roth IRA there's nothing to pay that year.

Should I reinvest my dividends?

If you don't need the income and the holding still fits your plan, yes: the money goes back to work without a trade to remember. 235 Coca-Cola shares reinvested for ten years ended worth $29,709, against $25,895 for the same shares with the dividends taken as cash. Take the cash when you live on it, when the position is already too big, or when another part of your portfolio needs it more.

How do I work out the cost basis of DRIP shares?

Each reinvestment is a new purchase and its holding period starts that day. Its cost is the dividend it used plus any fee, or the shares' full market value if a company plan sold them at a discount (the discount is taxed as a dividend too). Add them all to what you paid for the original shares: in our example that's $10,001.60 plus $4,875.18 of reinvested dividends, $14,876.78 across 41 lots. Leave the reinvestments out and you pay tax on the same $4,875.18 twice.

What are DRIP stocks?

Any stock or ETF that pays a dividend can be reinvested at a broker that offers it. The phrase usually means companies that run their own plan, such as Coca-Cola's, administered by Computershare, where you hold the shares in your own name and can buy more straight from the plan.

Can dividend reinvestment cause a wash sale?

Yes. A reinvested dividend is a purchase, so if it lands within 30 days before or after you sell the same stock at a loss, the loss on that many shares is disallowed and added to the new shares' basis. Turn reinvestment off on a position you plan to sell at a loss.

Every reinvested share, with its cost

Link your brokers or bring in your history, and AllInvestView keeps each reinvestment as its own lot, shows your dividend income across accounts and carries the right basis into your tax report.

Create a free account

Related calculators and guides

Sources

Prices and dividends are KO's closes and payments from 24 October 2016 to 23 October 2026. Rules checked on 26 October 2026; this page explains them in general terms.