US options taxes · 2026 tax year

How options are taxed in the US: calls, puts, covered calls and the wheel

Options on US stocks and ETFs are capital assets, so every trade ends in a capital gain or loss, and how the option ends decides the rule. Sold, bought back or expired: the gain or loss counts that day, and most trades are short term because they last under a year. A premium you collected is short term when the option expires or you buy it back. Exercised or assigned: the premium moves into the shares. Shares you buy cost less or more and nothing is taxed until you sell them; shares you sell bring more or less, and that sale is taxed now.

Here it is on real trades. On 23 October 2026 Apple closed at $347.73. Buy its 18 December $350 call for $1,365 and let it expire, and you have a $1,365 short-term loss in 2026. Sell the 18 December $330 put for $670 and get assigned, and nothing is taxed in 2026: your 100 shares cost $32,330, not $33,000.

Four Apple trades, four tax results Apple $347.73 · quotes at the 23 October 2026 close
Bought call expires−$1,365short-term loss, 18 Dec 2026

The $350 call bought at $13.65 is a capital loss on its expiry date.

Sold put assigned$323.30cost per share, $0 taxed in 2026

$330 strike less the $6.70 premium. The premium counts when you sell the shares.

Covered call called away$37,520sale price, gain long term

$370 strike plus the $520 premium, on shares held since January 2021.

SPX option gain, $10,00026.8%top rate, against 37%

60% at the 20% long-term rate, 40% at 37%, whatever the holding period.

How it ends decides how it's taxed

An option ends one of three ways: you close it, it expires, or it's exercised or assigned. Find your side and the ending; each cell has the rule and the Apple number.

How a US equity option is taxed by side and by the way it ends, with Apple examples from 23 October 2026
YouSold or bought backExpires worthlessExercised or assigned
Bought a callDec $350 call, paid $1,365 SoldUsually ST Sale price minus cost, short or long term by how long you held it.Say you sell it for $1,800: +$435 ExpiresUsually ST The cost is a capital loss on the expiry date.18 Dec 2026: −$1,365 ExercisedNo tax Add the premium to the shares' cost. Their holding period starts the day after exercise.$35,000 + $1,365 = $36,365 basis
Bought a putDec $340 put, paid $1,015 SoldUsually ST Sale price minus cost, as for a call.Say you sell it for $600: −$415 ExpiresUsually ST The cost is a capital loss on the expiry date.18 Dec 2026: −$1,015 ExercisedOn the shares You sell shares at the strike; subtract the premium from the amount realized.$34,000 − $1,015 = $32,985 realized
Sold a callDec $370 call, got $520 Bought backST Premium received minus the cost to close.Say you buy it back for $200: +$320 ExpiresST The premium is a gain on the expiry date.18 Dec 2026: +$520 AssignedShares' term Add the premium to the share sale price. The gain is short or long term by how long you held the shares.$37,000 + $520 = $37,520 realized
Sold a putDec $330 put, got $670 Bought backST Premium received minus the cost to close.Say you buy it back for $200: +$470 ExpiresST The premium is a gain on the expiry date.18 Dec 2026: +$670 AssignedNo tax Subtract the premium from the shares' cost. Their holding period starts when you buy them, not when you sold the put.$33,000 − $670 = $32,330 basis

ST: short term, a year or less. Options on stocks and ETFs, bought at the 23 October ask and sold at the bid, 100 shares a contract. The "say" prices are illustrations. A bought option held more than a year (a LEAPS, say) gives a long-term gain or loss.

Four Apple trades from open to tax year

The same 23 October quotes, followed to the day each one is taxed.

Bought call

The 18 December $350 call, three endings

  1. Buy 1 call at the $13.65 ask: $1,365No deduction for the cost; it's a capital expenditure.
  2. It ends one of three waysThe holding period is 56 days at most, so it's short term.
Sold first, say for $1,800+$435 ST
Expires with Apple under $350−$1,365 ST
Exercised: 100 shares at $350, no gain or loss yet$36,365 basis
After exercise the shares cost $363.65 each, and their holding period starts the next day. Sell them more than a year later and the whole gain is long term.
Cash-secured put

Sell the 18 December $330 put

  1. Sell 1 put at the $6.70 bid: $670 inNot income yet: the premium waits until the put ends. $33,000 set aside.
  2. Expiry dayApple above $330: it expires. Below: you're assigned 100 shares.
Expires: the premium is yours+$670 ST
Bought back, say for $200+$470 ST
Assigned: buy 100 at $330, minus $670$32,330 basis
Assigned, the put is never taxed on its own. The $670 lowers the shares' cost to $323.30 each, so your gain is $670 bigger, or your loss $670 smaller, when you sell them.
Covered call on long-held shares

Sell the 18 December $370 call against 100 shares

  1. Bought 100 Apple shares at $129.41: $12,941Held more than a year, so the shares are long term.
  2. Sell 1 call at the $5.20 bid: $520 in$22.27 above the price, 56 days to expiry: a qualified covered call.
Expires: keep the shares and the premium+$520 ST
Bought back, say for $200+$320 ST
Called away at $370: $37,520 − $12,941+$24,579 LT
Called away, the $520 joins the sale price and becomes part of a long-term gain. If the call expires or you buy it back, the premium is short term on its own.
The wheel, one cycle

Put assigned in 2026, shares called away in 2027

  1. Sell the Dec $330 put for $670Real quote, the bid at the close.
  2. Assigned: 100 shares, basis $32,330Nothing taxed. The shares' holding period starts here.
  3. Sell a 15 Jan 2027 $340 call, say for $450Priced on the day you sell it.
  4. Called away at $340: $34,450 realized$34,450 − $32,330 = +$2,120, short term, held 28 days.
All $1,120 of premium is taxed in 2027, inside one $2,120 short-term gain, even though the put was sold and assigned in 2026. More on the strategy in the wheel strategy guide.
Covered calls

Qualified covered calls keep the shares' clock

A call you write on shares you own is qualified when it trades on an exchange, has more than 30 days to expiry when written, isn't deep in the money and, for most, runs 12 months or less. An out-of-the-money call with more than 30 days left, like the $370 above, fits.

Write a qualified call below the share price and the shares' holding period pauses while it's open, and a loss on the call counts as long term if the shares would have been. A call that isn't qualified makes a straddle: losses can be deferred and a short-term holding period can start again when it ends. Shares held more than a year before the straddle keep their long-term status.

Protective puts

A put can reset the clock on young shares

Buying a put is generally treated as a short sale. If you've held the shares a year or less when you buy the put, any gain on the put is short term, and the shares' holding period starts over when the put is exercised, sold or expires, or when you sell the shares.

On shares held more than a year, like the 2021 lot above, a put leaves the holding period alone. More on the strategy in the protective put guide.

Short term, long term, and which year

Held more than a year means long term; a year or less, short term. Count from the day after you buy. The tax year is the year the option is closed or expires, or for an exercise or assignment, the year the shares are sold, not the year you opened it.

An option open on 31 December

Sell Apple's 15 January 2027 $370 call on 23 October 2026 at the $7.75 bid. The $775 isn't 2026 income: the premium waits until the call ends.

Bought back on 30 Dec 2026, say for $300
+$475short term, 2026
Expires on 15 Jan 2027
+$775short term, 2027
Assigned on 15 Jan 2027
2027$775 added to the share sale
2026 or 2027Close a short option in December and the result is 2026's; let it run into January and it's 2027's, unless it's assigned early. A bought option works the same way, except index options under section 1256, which are marked to market on 31 December.
2026 federal capital gains rates and thresholds by taxable income
2026 rateSingleMarried filing jointly
Long term 0%up to $49,450up to $98,900
Long term 15%up to $545,500up to $613,700
Long term 20%above $545,500above $613,700
Short termordinary rates, 10% to 37%37% above $640,60037% above $768,700
Net investment income taxon top of both rates3.8% above $200,000 MAGI3.8% above $250,000 MAGI

Taxable-income thresholds from Rev. Proc. 2025-32 for 2026. Net capital losses offset up to $3,000 of other income a year ($1,500 married filing separately); the rest carries forward.

Section 1256: SPX options and the 60/40 rule

Listed options on a broad-based stock index, such as the S&P 500 (SPX) options traded on Cboe, are nonequity options and fall under section 1256. Every gain or loss is 60% long term and 40% short term, however long you held the contract, even for a day.

Tax on a $10,000 gain, 2026 federal rates

The same gain on a short-term equity option against an SPX option, at three ordinary brackets.

Equity option, held under a yearSPX option, 60/40
24% bracket long-term rate 15%
Short term$2,400
60/40$1,860
35% bracket long-term rate 15%
Short term$3,500
60/40$2,300
37% bracket long-term rate 20%
Short term$3,700
60/40$2,680

Marginal rates on the whole gain: 60% × long-term rate + 40% × ordinary rate. The 3.8% net investment income tax, where it applies, adds the same to both.

What changes with section 1256

Split
60% LT / 40% STon every gain or loss
Open on 31 December
Marked to markettreated as sold at the last business day's value
Form
Form 6781lines 8 and 9 go to Schedule D lines 4 and 11
Net 1256 loss
Can go back 3 yearsagainst 1256 gains only, box D on Form 6781
On the 1099-B
One aggregate figurebox 11, profit or loss on contracts
SPY is not SPXSPY, QQQ and IWM options are options on fund shares, so they are equity options: normal holding periods, Form 8949, no 60/40. SPX is cash settled and European style; SPY delivers shares and can be assigned early.

Wash sales with options

Sell stock at a loss and, within 30 days before or after, buy the same stock or acquire a contract or option to buy it, and you can't deduct the loss yet. The rule also covers losses on the options themselves.

Apple example

A call bought inside the window

You bought 100 Apple shares at $347.73 on 23 October. Say Apple drops to $320 and you sell them on 20 November for a $2,773 loss. Buy one Apple call between 21 October and 20 December, and that loss is a wash sale.

$34,773 − $32,000 = $2,773 deferred, added to the call's cost
What happens to the loss

Deferred, not lost

The disallowed loss is added to the cost of the replacement, so you get it back when you close it. If the replacement is bought in an IRA, the loss is gone for good. One call covers 100 shares, so it washes the whole 100-share loss.

Where the IRS hasn't ruled

Different strikes and expiries

The IRS has no test for when an option with a different strike or expiry is substantially identical to another, or to the stock. Selling a put that is almost sure to be exercised can count as buying the stock (Revenue Ruling 85-87).

Brokers only have to report a wash sale on the 1099-B when the sale and the purchase are the same security in the same account. A share loss washed by a call, or by a buy at another broker or in an IRA, is yours to find. The wash sale tracker covers the rule across accounts in full.

Where options go on your return

Options on stocks and ETFs go on Form 8949, then Schedule D, usually straight from your 1099-B. Section 1256 contracts go on Form 6781. Four things to check before you file.

  1. Premiums on exercise and assignment

    For options opened since 2014, the broker has to fold the premium into the shares' basis or sale price. Check it's there, above all on shares moved between brokers. If a called-away call's premium is missing from the sale price, Form 8949 takes code E in column (f) and the premium in column (g).

  2. Expired options

    An expired option you bought shows the expiry date as the sale date and "Expired" as the proceeds. One you sold shows the expiry date as the acquired date and "Expired" as the cost. Each one is a line.

  3. Wash sales the broker can't see

    Brokers don't have to report losses washed by an option, by another account or by your spouse's buy. Check for them yourself and add any your 1099-B leaves out with code W.

  4. Index options on the right form

    SPX-type contracts belong on Form 6781 with the 60/40 split, not on Form 8949 as short-term trades. ETF options such as SPY belong on Form 8949. The Schedule D guide shows how the totals flow.

The Options Trading Tax Tracker

Your options, shares and every other holding in one ledger, synced from your brokers or imported from a file, with a realized gains report that already knows what each option did.

Capital gains tax report

Assigned shares at the right cost, every option on its own line

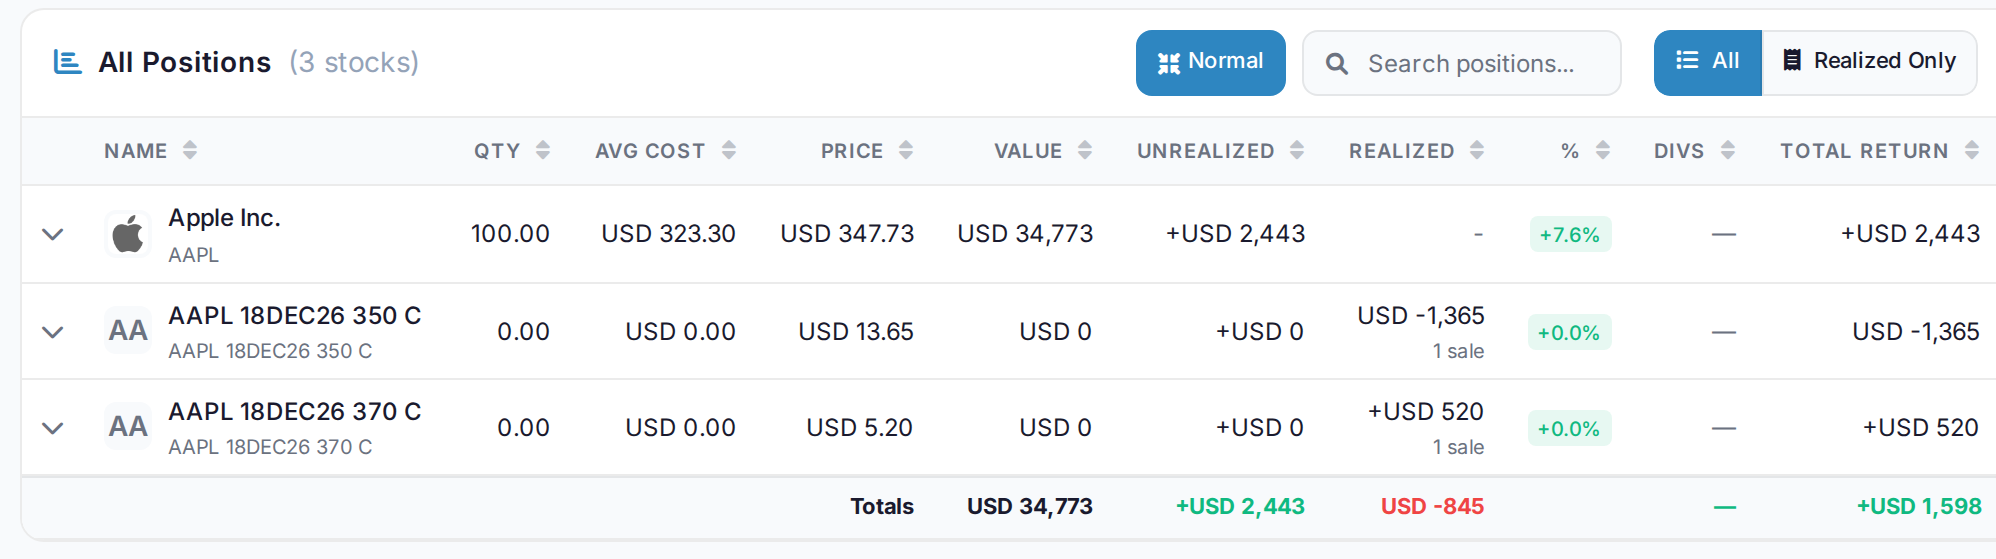
An assigned put or an exercised call books the shares at a cost that includes the premium, so the put above shows up as 100 Apple shares at $323.30, not as a separate gain. Each expired or closed option is a realized gain or loss with its own dates, and the report books every option you sold as short term.

  • Assigned put and exercised call premiums in the share basis
  • Every leg of a spread or iron condor with its own dates
  • Short and long term by the US holding-period rule
  • Export to PDF, CSV or Excel for you or your accountant

When shares are called away, the report shows the call's premium as its own short-term gain next to the share sale. The total is the same as the IRS figure; on shares held more than a year, move that premium onto the share sale on Form 8949.

AllInvestView AllInvestView tax report positions for 2026 under US rules: 100 Apple shares at an average cost of 323.30 dollars, the 18 December 350 call with a realized loss of 1,365 dollars and the 18 December 370 call with a realized gain of 520 dollars AllInvestView tax report positions for 2026 under US rules: 100 Apple shares at an average cost of 323.30 dollars, the 18 December 350 call with a realized loss of 1,365 dollars and the 18 December 370 call with a realized gain of 520 dollars
This guide's Apple trades: the $330 put assigned into 100 shares at $323.30, the bought $350 call expired at −$1,365 and the $370 call expired at +$520. A staged demo account.Full sizeFull size
Every broker in one place

Every premium, assignment and expiry in one ledger

Options, shares, ETFs, bonds and dividends on one dashboard, synced from your brokers or imported from a file, with realized gains ready for tax time.

Premiums in the share basis Wheel cycles linked 14-day free trial, no card required

Questions about options taxes

How does an options assignment affect my cost basis?

If a put you sold is assigned, the premium lowers the cost of the shares you buy. Sell Apple's 18 December 2026 $330 put for $670 and get assigned, and your 100 shares cost $32,330 ($323.30 each), not $33,000. Nothing is taxed on the put itself; the premium shows up when you sell the shares. If a call you sold is assigned, the premium is added to what you get for the shares instead.

How are wheel strategy trades taxed?

Each leg follows its own rule. A put that expires or that you buy back is a short-term gain or loss. An assigned put's premium lowers the share basis. A covered call that expires or that you buy back is short-term, except that a loss on an in-the-money call written against shares held over a year is long term; if the shares are called away, its premium is added to the sale price and the gain's term follows the shares. A cycle that starts with an assignment in December and ends with a call-away in January is taxed in January's year.

What is the difference between Section 1256 contracts and regular options?

Section 1256 covers nonequity options such as options on the S&P 500 index (SPX). Any gain or loss is 60% long term and 40% short term however long you held them, open contracts are marked to market on the last business day of the year, and they go on Form 6781. Options on stocks and ETFs, SPY, QQQ and IWM included, are equity options: normal holding periods and Form 8949.

Does the wash sale rule apply to options?

Yes. Selling stock at a loss and buying a call on the same stock within 30 days before or after is a wash sale, and the rule also covers losses on options themselves. The IRS has not said when options with different strikes or expiries count as substantially identical. Brokers only have to flag wash sales on the 1099-B for the same security in the same account.

How do I report options trades on my taxes?

Options on stocks and ETFs go on Form 8949 and then Schedule D, usually straight from your 1099-B. An expired option you bought takes the expiry date as its sale date and "Expired" as its proceeds; one you sold takes the expiry date as its acquired date and "Expired" as its cost. Section 1256 contracts such as SPX options go on Form 6781, whose 40% and 60% lines carry to Schedule D lines 4 and 11.

What is the tax treatment of expired options?

If you bought the option, its cost is a capital loss on the expiry date, short or long term by how long you held it. If you sold it, the premium is a short-term gain on the expiry date. Apple's 18 December $350 call bought for $1,365 and left to expire is a $1,365 short-term loss in 2026.

Can I deduct losses on options that expired worthless?

Yes. A bought option that expires worthless is a capital loss dated the expiry day. Capital losses offset capital gains first, then up to $3,000 of other income a year ($1,500 if married filing separately), and the rest carries forward. A wash sale can still defer it if you bought a substantially identical position within 30 days.

How do covered calls affect my cost basis when assigned?

They don't change the basis; they raise the sale price. Sell Apple's 18 December $370 call for $520 against shares bought in January 2021 at $129.41, get called away at $370, and you sold the shares for $37,520. The $24,579 gain is long term because the shares were held more than a year. If the call expires instead, the $520 is a short-term gain and you keep the shares.

What does AllInvestView's report show for options trades?

Every closed or expired option as its own realized gain or loss, with its dates, and shares from an assigned put or an exercised call at a cost that includes the premium. A covered call's premium stays a separate short-term gain when the shares are called away, so the total matches the IRS treatment; on shares held more than a year, move that premium onto the share sale on Form 8949. Export the report to PDF, CSV or Excel.

Sources

Checked on 26 October 2026. Last updated 26 October 2026.

Options bought at the ask and sold at the bid, 100 shares a contract, commissions left out. Prices marked "say" are illustrations of what a later trade could fetch. Rates are 2026 federal rates applied at the margin; state taxes are not included.

This guide explains the federal rules in general terms. It isn't tax advice for your situation.