Unused allowance is gone on 5 April
Nothing carries over. Putting £10,000 in this year doesn't let you put £30,000 in next year.
You can put £20,000 into ISAs between 6 April 2026 and 5 April 2027, split however you like between stocks and shares, cash, innovative finance and a Lifetime ISA. Interest, dividends and gains inside are free of UK tax and never go on your tax return. The allowance doesn't carry over, and from 6 April 2027 anyone under 65 can put no more than £12,000 of it in cash.
Four share your £20,000. The Junior ISA has its own allowance and belongs to the child.
| ISA | Yearly limit | Who can open one | What goes in | Taking money out |
|---|---|---|---|---|
| Stocks and shares ISA | £20,000shared | UK residents aged 18 or over | Shares (AIM ones too), funds, ETFs, investment trusts, bonds and cash | Any time, tax-free. A flexible ISA lets you put cash back in the same tax year without using more allowance |
| Cash ISA | £20,000£12,000 from April 2027 if under 65 | UK residents aged 18 or over | Savings accounts and cash deposits | Any time, subject to the account's notice or fixed term |
| Lifetime ISA | £4,000inside the £20,000 | Aged 18 to 39 to open; you can pay in until 50 | Cash or investments, plus a 25% government bonus | Free from 60, with under 12 months to live, or paid through your conveyancer for a first UK home up to £450,000 bought with a mortgage, 12 months or more after your first payment. Otherwise a 25% charge |
| Innovative finance ISA | £20,000shared | UK residents aged 18 or over | Peer-to-peer loans, crowdfunding debentures and some bonds | When the loans allow; this money can be locked up |
| Junior ISA | £9,000per child, separate | A parent or guardian, for a UK resident child under 18. From 16 a child can open their own | Cash or investments; a child can hold one of each. A Child Trust Fund has to be moved in, not kept alongside | Locked until 18. The child can run it from 16 |
Any mix works as long as the total stays within £20,000 and the Lifetime ISA within £4,000.
The rules move every couple of years. These are the ones that touch you now.
Brokers that sell slices of a share can now hold them inside your stocks and shares ISA.
Dividend tax went up to 10.75% for basic rate and 35.75% for higher rate taxpayers (39.35% additional rate unchanged), above a £500 allowance. Inside an ISA it's still nothing.
The £20,000 adult and £9,000 Junior ISA allowances stay where they are until 5 April 2031.
The Treasury consulted on a simpler first-home product until 18 August 2026. Nothing is legislated and there's no start date. You can still open a Lifetime ISA, and existing ones carry on under today's rules.
Most expensive ISA mistakes come from one of these.
Nothing carries over. Putting £10,000 in this year doesn't let you put £30,000 in next year.
Pay in £20,000, withdraw £5,000, and you can't pay in again this tax year. Only a flexible ISA lets you replace it, and only before 5 April. Lifetime and Junior ISAs are never flexible.
Ask the new provider to transfer it and the money keeps its ISA status without using this year's allowance. Withdraw it yourself and it's just cash again. Lifetime ISAs differ: money moved in from another type of ISA counts towards the £4,000, and moving a Lifetime ISA into another type before 60 usually costs the 25% charge.
No tax on gains also means no relief for losses. A loss inside your ISA can't be set against gains in a general account.
Pay in £4,000, get £1,000 of bonus, and take the £5,000 out for anything else: the 25% charge is £1,250, so you get £3,750 back. That's £250 less than you paid in.
You keep the ISA and it stays free of UK tax, but you can't add to it while you're not UK resident, unless you're a Crown employee or married to one. Your new country may tax it.
When an ISA holder dies, the account stays tax-free while the estate is dealt with, for up to three years. A surviving spouse or civil partner also gets an extra one-off allowance equal to the ISA's value, on top of their own £20,000.
The same investments held in a general account, at 2026/27 rates.
A portfolio paying 3%, so £3,000 a year, for a higher rate taxpayer.
(£3,000 − £500 allowance) × 35.75%. A basic rate taxpayer pays £268.75.
Shares bought for £50,000 and sold for £80,000, no other gains that year.
(£30,000 − £3,000 exempt) × 24%. At 18%, if the gain fits in your basic rate band: £4,860.
Gains above the £3,000 exempt amount have to be reported to HMRC, and so do sales over £50,000 if you already file Self Assessment.
ISA income and gains don't go on a Self Assessment return at all.
Sell in your general account, buy the same thing back inside your ISA. The sale is taxed; the buyback isn't matched to it, so the gain is worked out from your average cost.
Each bar is the whole £60,000: already in your ISA, moved that year, and still outside.
| Tax year | Sold and rebought in the ISA | Gain | Taxable | Tax | Left outside |
|---|
Prices are held at today's value and later years assume no other gains, a £3,000 exempt amount and a £20,000 allowance. Costs of dealing are left out; they reduce the gain.
Every account as its own portfolio, and one view across all of them.
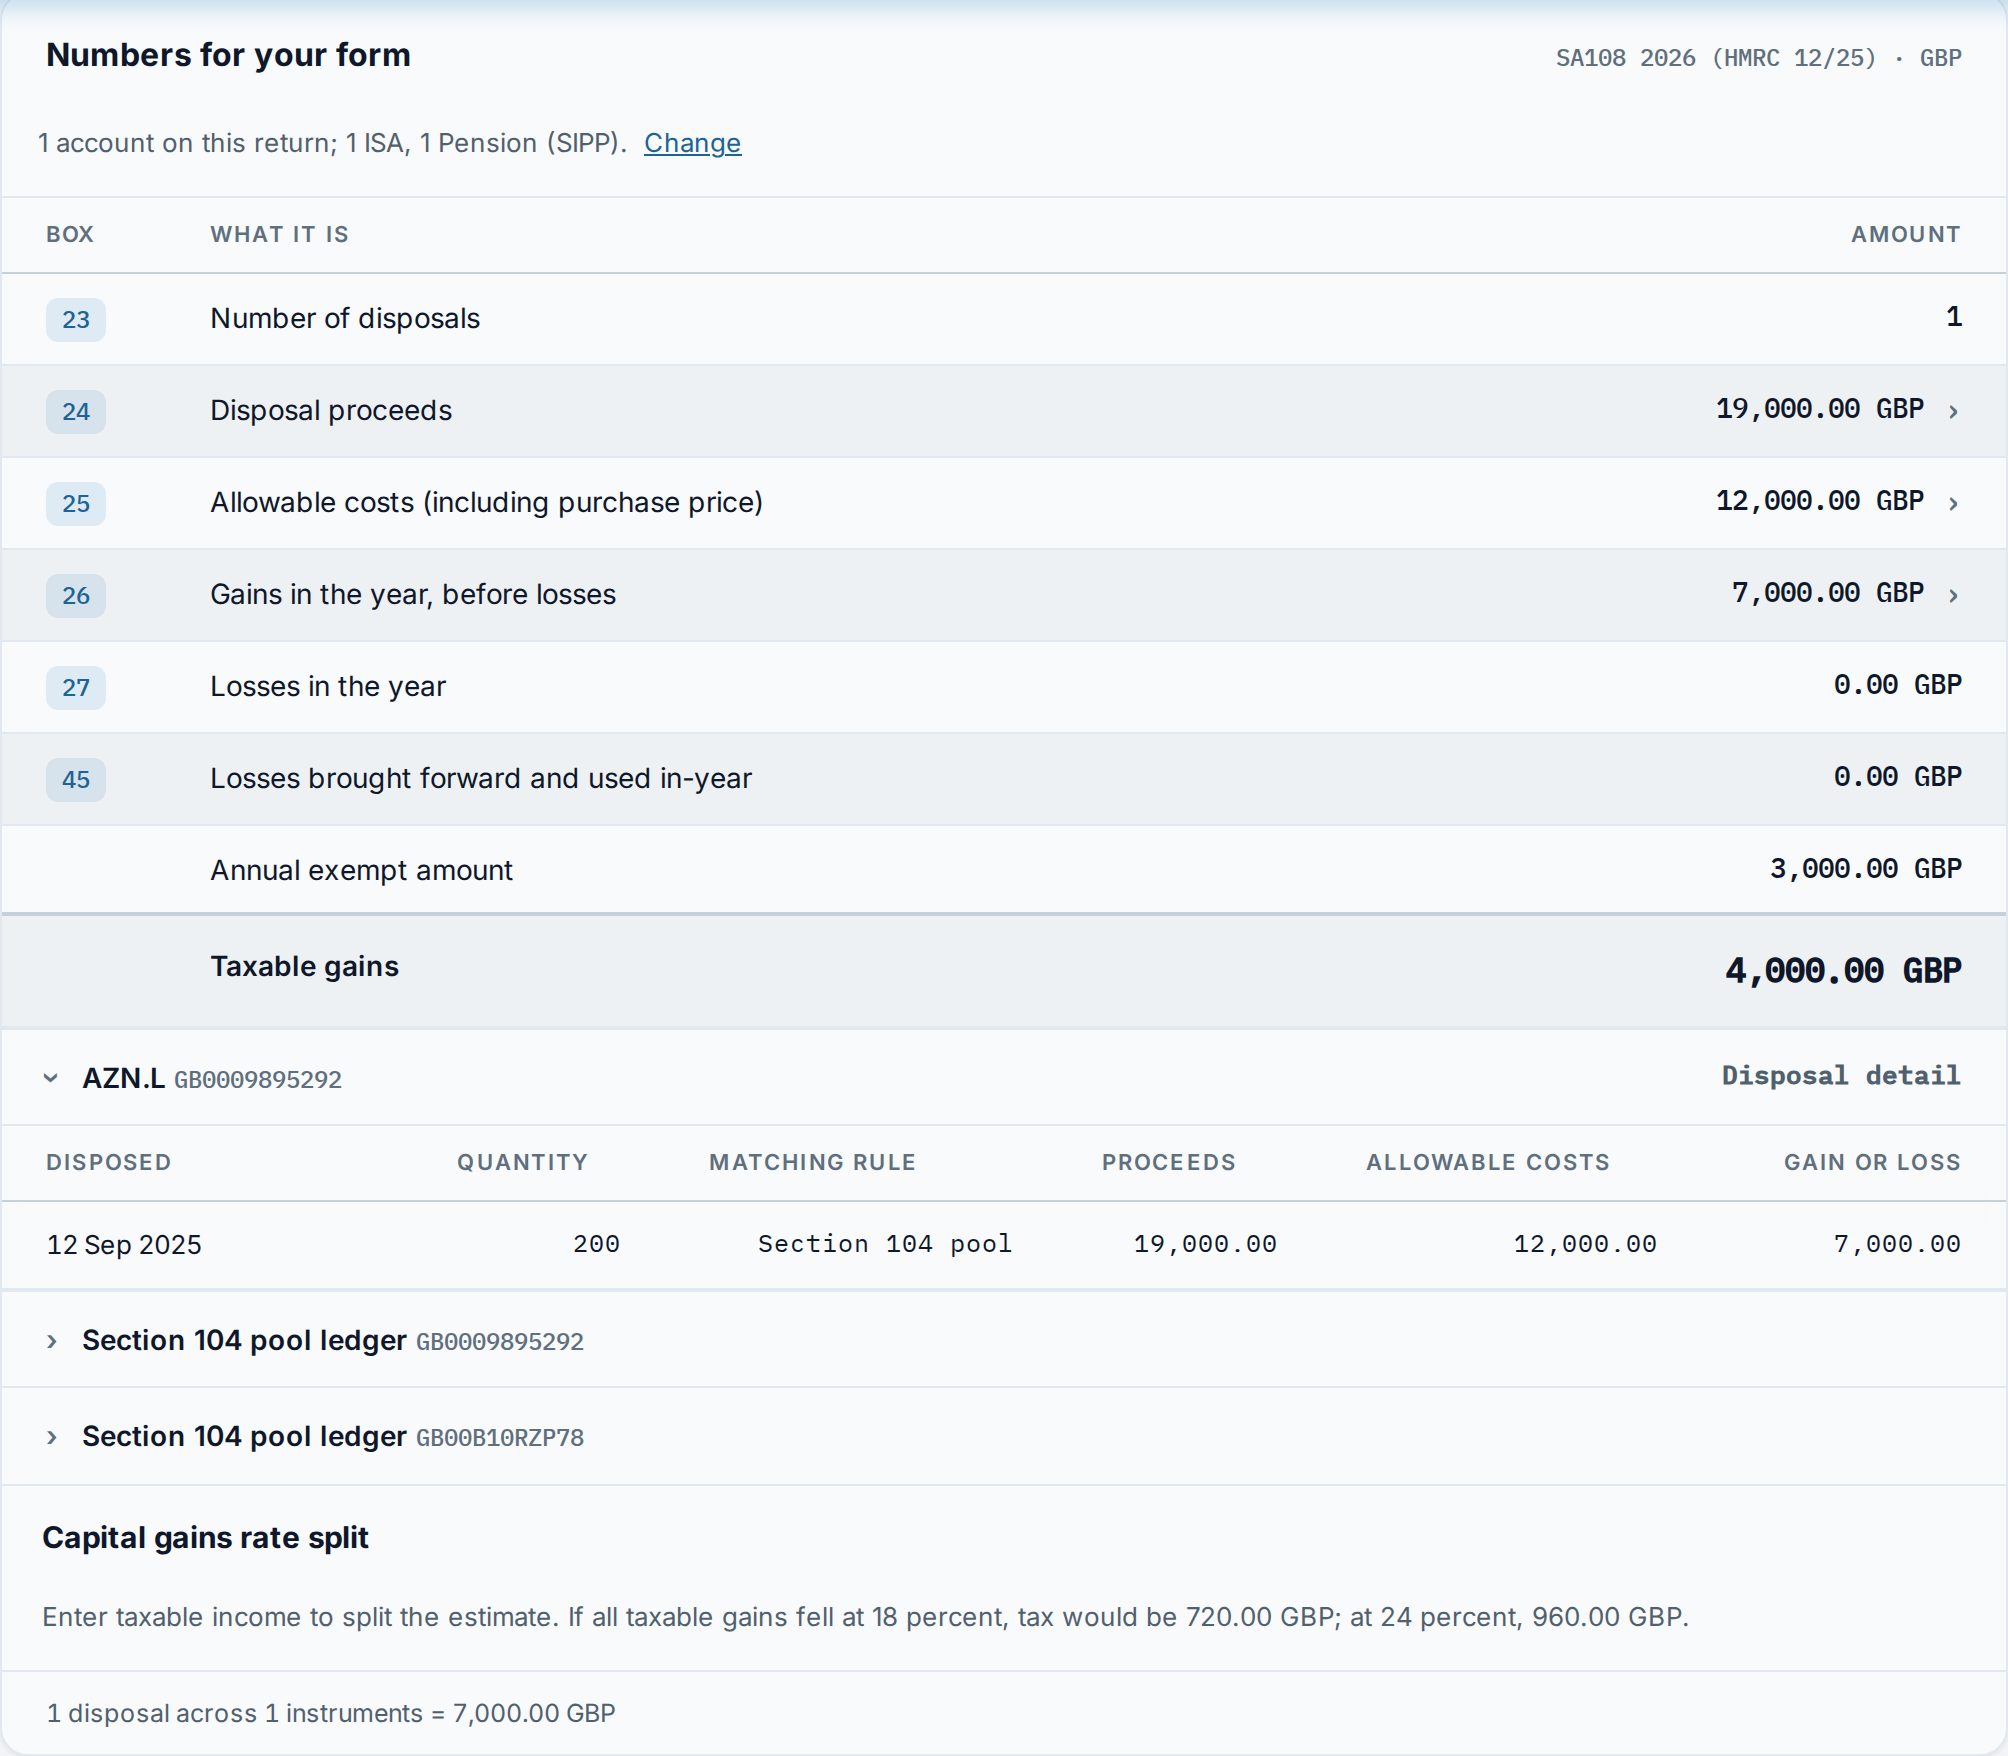
Mark an account as an ISA, or just name it one, and its gains and dividends stay out of your tax figures, in the free tax report and in the SA108 pack. Here 200 shares were sold in the general account and bought back in the ISA the same day. The pack matches the sale to the pool, not to the buyback: a £7,000 gain, £4,000 of it taxable. Your ISA, SIPP and general accounts from every broker sit side by side, each with its own returns and dividends.
See the UK tax report AllInvestView
ISA, SIPP, Lifetime ISA and general accounts across brokers, with real returns, dividends and a UK tax report that leaves the ISA out.
£20,000 between 6 April 2026 and 5 April 2027, across every adult ISA you pay into. A Lifetime ISA takes up to £4,000 of that £20,000. A Junior ISA has its own £9,000 for each child and doesn't touch yours. Both allowances are frozen until 5 April 2031, and whatever you don't use by 5 April is gone.
Yes. Since 6 April 2024 you can pay into as many cash, stocks and shares and innovative finance ISAs as you like in the same tax year, as long as the total stays within £20,000. The exceptions are the Lifetime ISA, where you can pay into one a year, and Junior ISAs, where a child can hold one cash and one stocks and shares ISA.
Selling investments in a taxable account and buying them straight back inside your ISA, so future growth and dividends are tax-free. The sale counts for capital gains tax, but the buyback inside the ISA isn't matched to it under the same-day or 30-day rules, so the gain is worked out from the average cost of your holding. Keep each year's gains within the £3,000 allowance and the move costs no tax at all.
No. Interest, dividends and gains inside an ISA are free of UK tax and don't go on your Self Assessment return. The flip side is that a loss made inside an ISA can't be used against gains elsewhere.
Yes, from 6 April 2027. If you are under 65 at the end of the tax year, no more than £12,000 of your £20,000 can go into cash ISAs, and you won't be able to move stocks and shares or innovative finance ISA money into a cash ISA. If you turn 65 that year or are older, you can still put the full £20,000 in cash. The rules were made in September 2026 and start on 6 April 2027.
You keep it and it stays free of UK tax, but you can't pay anything new into it while you're not UK resident, unless you're a Crown employee such as a diplomat or in the armed forces, or married to one. Tell your provider when you leave. The country you move to may tax the income, because the ISA is a UK wrapper.
Checked on 23 October 2026.
Free to start. Connect a broker or import your history.