The average covers every depå you have
Shares of the same company and class share one average cost, whichever bank or broker holds them. A and B shares are separate. Shares in an ISK stay out of it.
In an ordinary account, a depå, you pay 30% on gains and dividends, and the gain is the sale price minus the average cost of all your shares of the same kind, whichever broker holds them. In an ISK selling and dividends cost nothing; you pay a yearly tax on the account's value instead, 1.065% for 2026 on everything above SEK 300,000. Losses on listed shares cancel listed gains in full, and 70% of what's left is deductible. Sales go on the K4 form.
The same shares and funds, two very different tax bills.
| Depå (ordinary account) | ISK (investeringssparkonto) | |
|---|---|---|
| When you sell | 30% of the gain. The cost is your average cost, or 20% of the sale price for listed shares and funds | Nothing. Sales inside an ISK aren't reported at all |
| Dividends | 30%. On Swedish shares the bank usually withholds it as you're paid | Nothing in Sweden. Foreign withholding tax can be credited against the ISK tax |
| Every year | Nothing on shares. Funds and ETFs add a standard income of 0.4% of their value on 1 January, so 0.12% tax | 3.55% of the capital base, taxed at 30% for 2026, above the tax-free SEK 300,000. Paid in a good year or a bad one |
| Losses | Cancel listed gains in full; 70% of the rest is deductible | Not deductible |
| Your return | Share sales on K4, with the cost you're responsible for. Fund gains and losses usually arrive filled in | One prefilled figure, the standard income |
 Avanza
 Nordnet
Swedish banks and online brokers such as Avanza and Nordnet offer both an ISK and a depå, and you can hold foreign listed shares and funds in either. Many investors keep both: the ISK for long-term holdings, a depå for positions they might sell at a loss. Browse Swedish stocks on Nasdaq Stockholm.
Same money, same return. One pays a little every year, the other pays when you sell.
The ISK's capital base is the average of the values on 1 January, 1 April, 1 July and 1 October.
| Year | Value on 1 January | ISK capital base | ISK tax | Depå tax |
|---|
The return is all growth, with no dividends and no new money, and the rate and tax-free amount stay the same every year. Taxes are paid from outside the account, so both accounts grow the same; the depå sells everything in the last year and pays 30% on the gain, using the 20% method when that costs less. Fees are left out.
Income year 2025. Shares bought at Avanza and Nordnet, sold from Nordnet.
Bought 100 Volvo B at SEK 320
SEK 32,000Bought 200 Volvo B at SEK 200
SEK 40,000SEK 72,000 ÷ 300 shares
SEK 240 a share| QuantityAntal | SecurityBeteckning | Sale priceFörsäljningspris | CostOmkostnadsbelopp | GainVinst | LossFörlust |
|---|---|---|---|---|---|
| 150 | Volvo B | 45,000 | 36,000 | 9,000 | |
| 100 | Ericsson B | 6,000 | 9,000 | 3,000 | |
| Totals | 9,000 | 3,000 |
One ISK, the same four values, taxed under the 2025 and the 2026 rules.
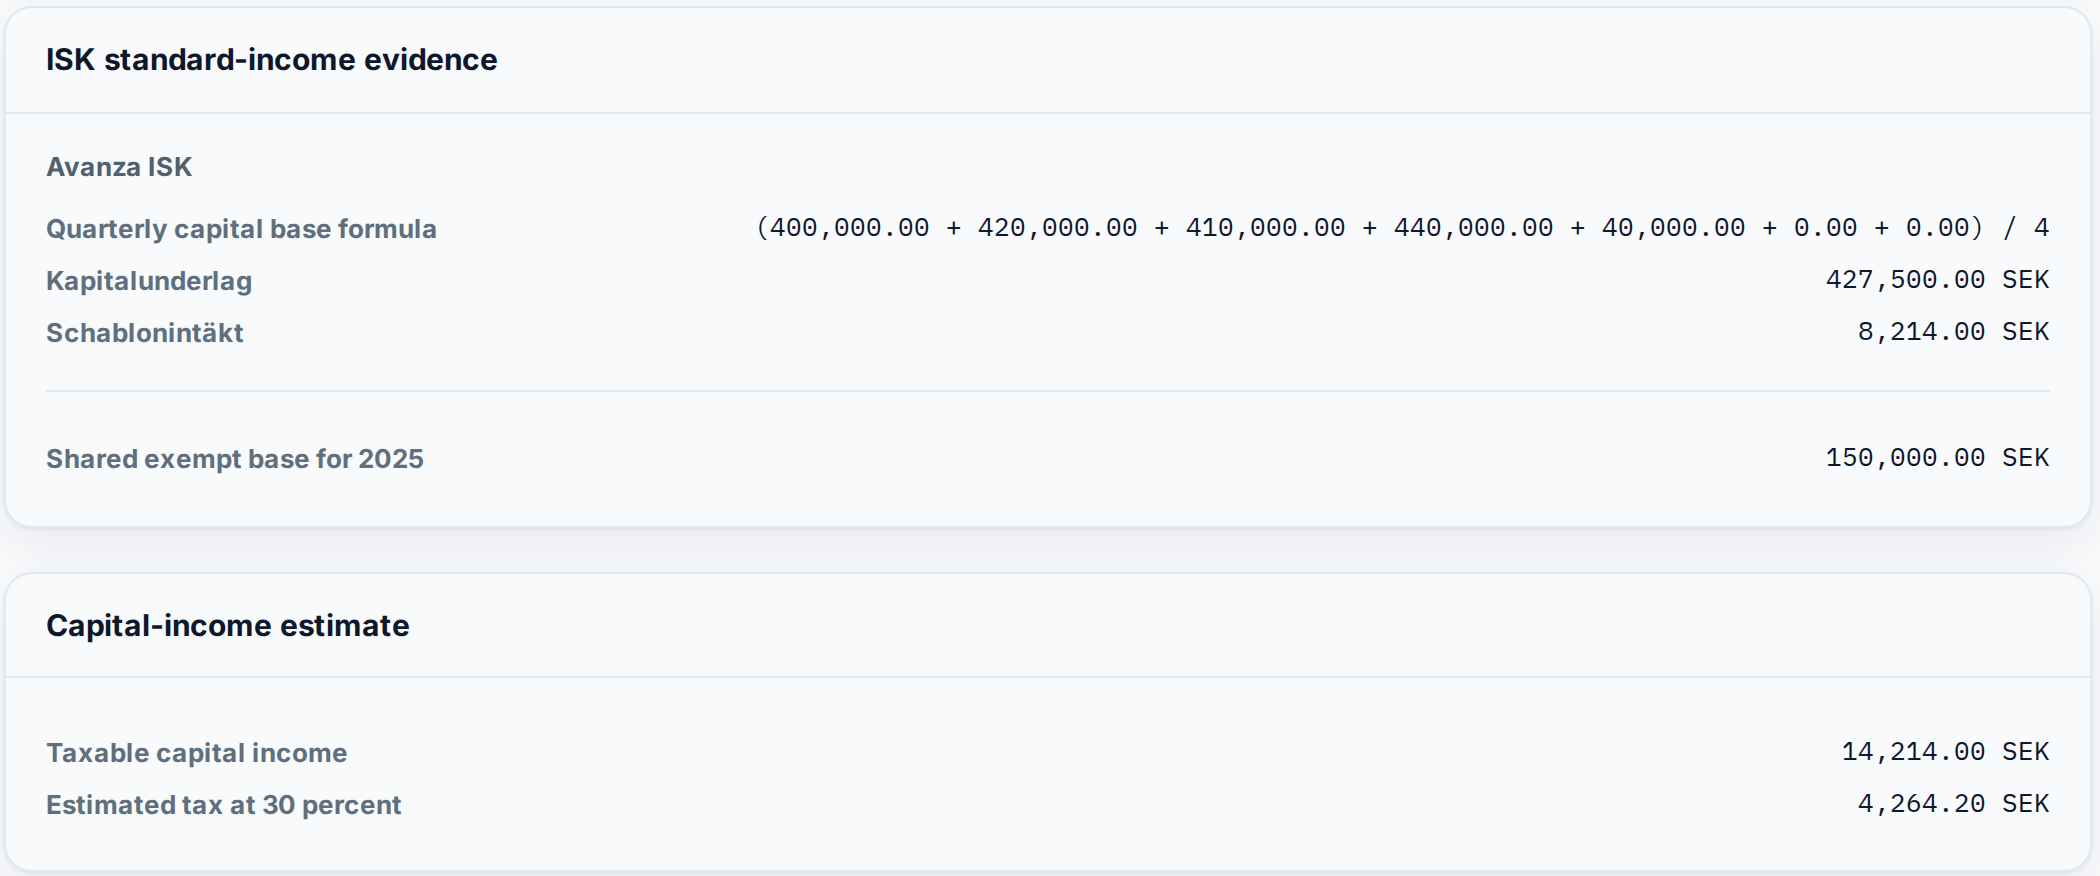
Add the value at the start of each quarter and every deposit made during the year, then divide by four. Money moved from another ISK of yours doesn't count as a deposit.
Take off the tax-free amount, apply the year's standard rate, then tax the result at 30%.
Shares of the same company and class share one average cost, whichever bank or broker holds them. A and B shares are separate. Shares in an ISK stay out of it.
After listed losses have cancelled listed gains, 70% of what's left is deducted from your other capital income. If that leaves a deficit, you get 30% of it off your tax up to SEK 100,000, and 21% above that.
Nothing you lose inside an ISK can be deducted, and the yearly tax is due even in a year the account falls. That's the reason to keep a speculative position in a depå.
Shares moved from your depå into an ISK count as sold at market value. You report the gain or loss on K4 that year, and the value counts as a deposit in the ISK's capital base.
Convert the purchase at that day's rate and the sale at the sale day's rate. Use the rate you actually got when currency is exchanged on the trade day, or when you change the sale money into SEK within 30 days. Converting the gain once at the end gives the wrong figure.
A US dividend usually has 15% withheld under the tax treaty. You declare the full dividend and claim a credit for the tax paid abroad, up to the Swedish tax on it. It's often filled in for you when the payer reports it.
K4 (SKV 2104) is the form for selling shares, funds and other securities.
| Section | What goes there | How losses work |
|---|---|---|
| A | Listed shares, listed equity and mixed funds, ETFs that hold shares, subscription rights and similar | Cancel gains in section A in full; 70% of the rest is deductible |
| B | Gains deferred in an earlier share exchange, coming back now | Not a section for ordinary sales |
| C | Listed bonds, foreign currency and listed interest funds that hold SEK debt | Deductible in full |
| D | Crypto, unlisted funds, unlisted bonds and other assets. Unlisted company shares go on K10 or K12 instead | 70% deductible |
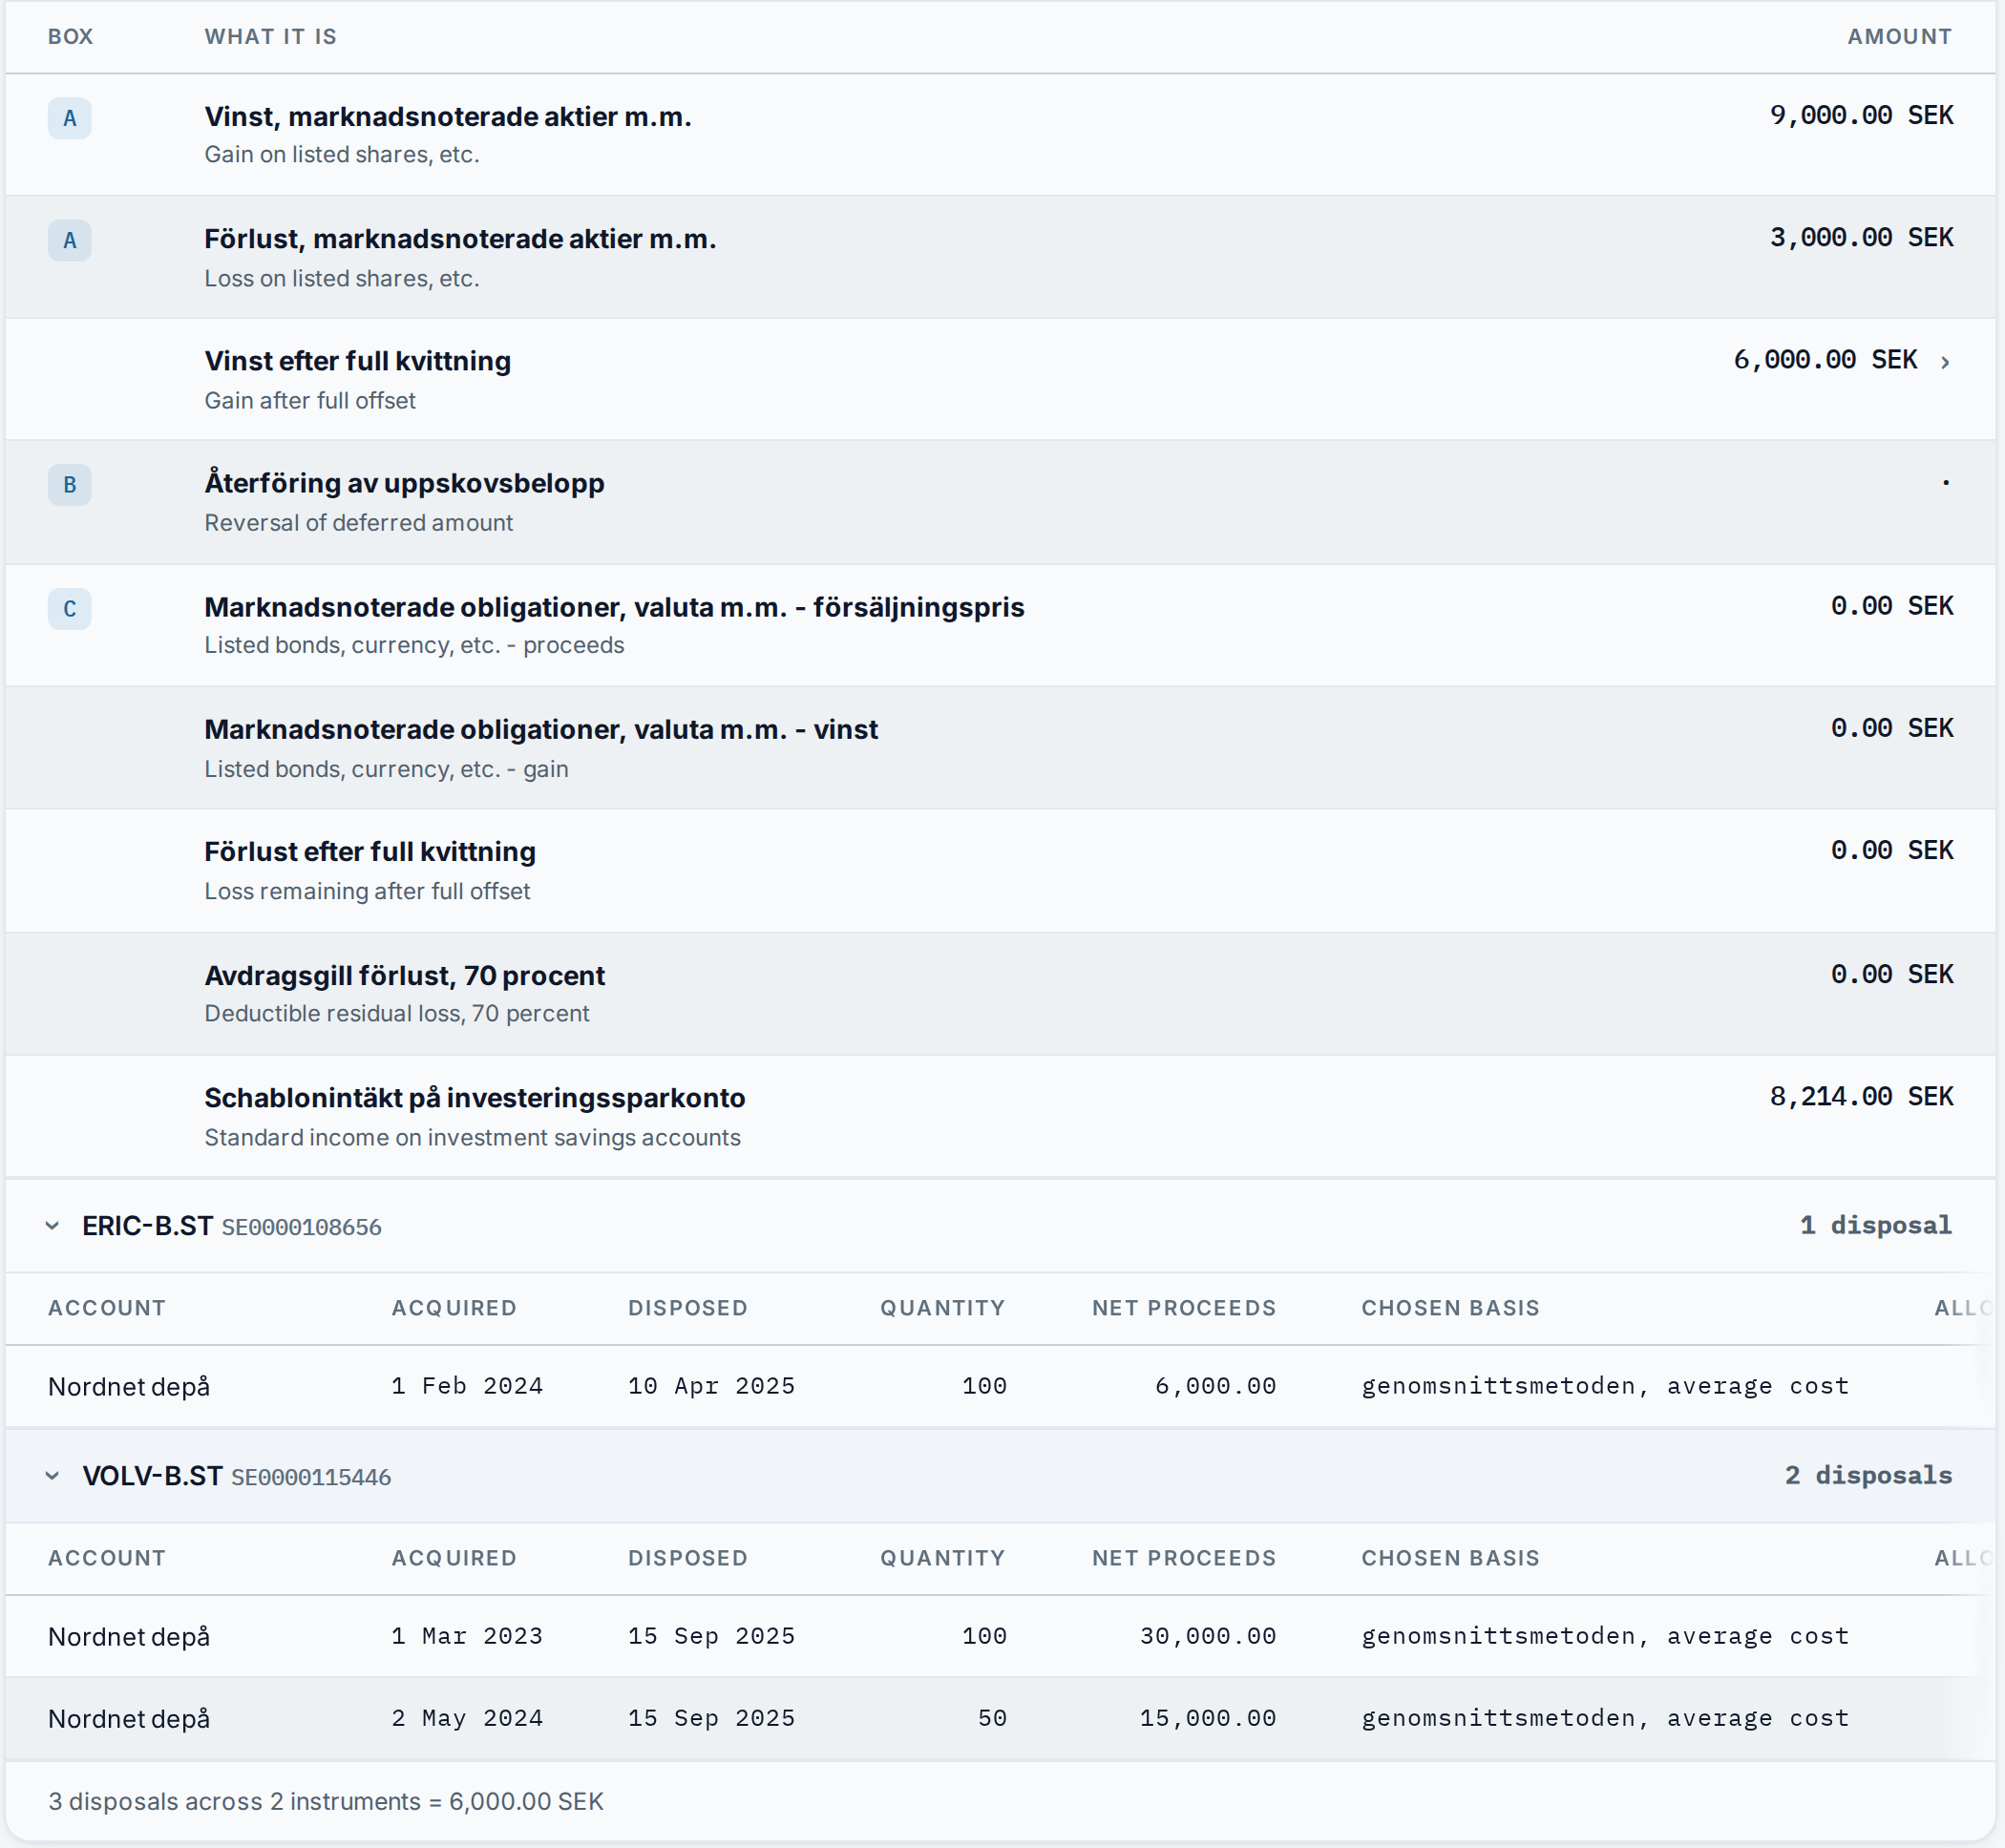
The Swedish filing pack, run on the example above.
Put each broker in as its own account and the pack keeps one average cost per share class across all of them, with every purchase and sale converted to SEK on its own day, at the Riksbank rate or at the SEK amount your broker actually settled. You can switch any eligible sale to the 20% method, and losses on listed shares cancel gains in full before the 70% rule. It ends with the section A, B and C figures and every disposal behind them, ready to export.
See the multi-broker tax report AllInvestView
Mark an account as an ISK and it stays out of K4. Enter the four quarter-start values and your deposits and the pack works out the capital base, the shared tax-free amount and the standard income. It then adds that to the depå result for one capital income estimate.
Compare trackers for Swedish investorsAllInvestView
Accounts from Avanza, Nordnet and your foreign brokers side by side, with real returns, dividends and a Swedish tax pack that keeps the ISK off K4.
An investeringssparkonto (ISK) is a Swedish account for shares and funds where selling and dividends aren't taxed. Instead you pay a yearly tax on what the account holds: for 2026 that's 1.065% of the amount above SEK 300,000. You can't deduct a loss made inside an ISK.
30% of the gain, in an ordinary account. For shares you take the sale price minus your average cost across every account, or minus 20% of the sale price on listed shares if that leaves a smaller gain. A loss on listed shares is first set against gains on listed shares, and 70% of whatever loss is still left can be deducted.
An ISK usually comes out ahead when your investments grow faster than the standard rate, 3.55% for 2026, and the first SEK 300,000 costs nothing at all. A depå suits money you expect to grow slowly or lose, because only there can you deduct a loss. The calculator on this page runs your own numbers.
Partly. Swedish banks and brokers report the number of shares and the sale price, so those arrive filled in. The cost is yours to check or add, and it has to be your average across every account that holds the share. Sales at a foreign broker you usually add yourself.
Convert the purchase at the rate on the day you bought and the sale at the rate on the day you sold, normally the Riksbank's rate for that day. Use the rate you actually got instead when currency was exchanged on the trade day, or when you changed the sale money into SEK within 30 days. Working out the gain in dollars and converting it once at the end gives the wrong number.
Yes. The move counts as a sale at market value, so the gain or loss goes on that year's K4, and what you moved in counts as an ISK deposit.
Income year 2025 was due on Monday 4 May 2026. For income year 2026 the deadline is Monday 3 May 2027, because 2 May falls on a Sunday.
Checked on 23 October 2026.
This page explains the rules for individuals resident in Sweden. It isn't personal tax advice.