The put expires and you keep the premium
Nothing else happens. The $13,000 is free again, and you can sell another put or move on.
Kept: $95 on $13,000
Shares bought: none
Shares bought: none
A cash-secured put means you sell a put option and keep enough cash to buy the shares if they're put to you: the strike price times 100 for each contract. You're paid a premium up front. If the stock stays above the strike, the put expires and the premium is yours. If it ends below, you buy 100 shares at the strike, and the premium you kept lowers what they cost you.
On 23 October 2026 PepsiCo closed at $135.77. Selling the 20 November $130 put paid $95 at the bid, with $13,000 set aside: 0.73% in 28 days. If PepsiCo finished below $130 you'd normally be assigned, and the shares would cost you $129.05 each, 4.9% under that day's close.
$130 × 100 = $13,000
$130 − $0.95 = $129.05
$95 ÷ $13,000 = 0.73% in 28 days
PepsiCo had reported its quarter on 8 October, so no earnings fell inside this trade, and its next dividend date came after expiry. Move the slider to see what you'd have at expiration against simply buying the shares that day.

Bid $0.95, ask $1.15 at the close. The cash can usually sit in Treasury bills or a money market fund meanwhile: at the 4-week bill rate of 3.94% that's about $39 more over the 28 days.
| PepsiCo on 20 Nov | What happens to the put | Put seller | Bought the shares on 23 Oct |
|---|---|---|---|
| $145.00, up 6.8%Expires worthless | Expires worthless | +$95 | +$923 |
| $135.77, unchangedExpires worthless | Expires worthless | +$95 | $0 |
| $131.00, down 3.5%Expires worthless | Expires worthless | +$95 | −$477 |
| $127.00, down 6.5%Assigned: you buy 100 at $130 | Assigned: you buy 100 at $130 | −$205own 100 shares at $129.05 | −$877 |
| $115.00, down 15.3%Assigned: you buy 100 at $130 | Assigned: you buy 100 at $130 | −$1,405own 100 shares at $129.05 | −$2,077 |
That's the trade in one table. The put seller wins in three of the five cases and loses less in the other two, but gives up everything above $95. If PepsiCo had jumped 10%, the shareholder would have made about $1,360 and you'd still have $95.
The same PepsiCo expiry, four strikes, all at the bid on 23 October 2026. A strike closer to the price pays more because you're more likely to end up owning the shares.
| Strike | Below the price | Bid | Premium | Return, 28 days | Same rate a year | Delta | Breakeven |
|---|---|---|---|---|---|---|---|
| $120 | 11.6% | $0.12 | $12 | 0.10% | 1.3% | 0.04 | $119.88 |
| $125 | 7.9% | $0.35 | $35 | 0.28% | 3.6% | 0.09 | $124.65 |
| $130 | 4.2% | $0.95 | $95 | 0.73% | 9.5% | 0.22 | $129.05 |
| $135 | 0.6% | $2.51 | $251 | 1.86% | 24.2% | 0.43 | $132.49 |
Delta is how much the put's price moves for each $1 in the stock (negative for a put; the table shows its size), and traders use it as a rough guide to the chance of finishing below the strike. Many put sellers aim for about 0.20 to 0.30. Pick the strike from the price you'd be happy to pay for the stock, not from the premium: the $135 put pays most, and it's also the one most likely to hand you 100 shares at $132.49. The annual figures show the 28-day return kept up for a year without compounding; nobody gets the same premium every month. Deltas are from AllInvestView's options Greeks calculator, with volatility taken from each put's midpoint price.
US stock options can be assigned on any day up to expiry, though it's rare while a put still has time value left. Most assignments come at expiration, when the put finishes below the strike.
Nothing else happens. The $13,000 is free again, and you can sell another put or move on.
Your broker takes $13,000 from the cash you set aside and puts 100 PepsiCo shares in your account. From there you can hold them, sell them, or sell a covered call on them, which is the next step of the wheel.
You can buy the put back at any time. Many sellers close once they've kept about half the premium. To roll, you buy it back and sell a later or lower put in one order. Many sellers only roll when it brings in a net credit.
Keep the premium while you wait.
Buy 100 shares at the strike.
Earn premium on the shares you now own.
The shares are sold, the cash is back, start again.
That loop is the wheel strategy. Each turn adds premium, but the shares can fall further than the premiums cover, so the stock you pick still matters most.
Cboe's S&P 500 PutWrite Index sells a one-month at-the-money S&P 500 put every month and keeps the full strike value in Treasury bills: a cash-secured put run by the book. Cboe launched it in 2007 and has calculated it back to 1986. Here it is year by year against the S&P 500 with dividends reinvested.
Tap or hover a year. 2026 runs to 23 October. S&P 500 measured with SPY, dividends reinvested. Index values from Cboe.
The pattern is the one the PepsiCo table showed. Selling puts gave up a lot in rising markets, 2013, 2019 and 2020 most of all, and lost less in most falling ones, 2018 being the exception. It isn't a safer way to own stocks so much as a smoother one with a lower ceiling. Over the past year the two were close: 13.9% against 14.4%.
Three ways to act on the same stock. A cash-secured put and a covered call at the same strike and expiry have almost the same payoff: one starts in cash, the other in shares.
| Cash-secured put | Covered call | Limit order to buy | |
|---|---|---|---|
| You start with | Cash: strike × 100 | 100 shares | Cash |
| Paid up front | The put premium | The call premium | Nothing |
| If the stock rises | Keep the premium, no shares | Gains capped at the strike plus premium | Order may never fill |
| If the stock falls | Buy at the strike, cost cut by the premium | Lose on the shares, cushioned by the premium | Buy at your price, no cushion |
| Dividends | None until you own shares | Yours while you hold the shares | Only once filled |
The IRS treats the premium differently depending on how the put ends, per Publication 550. Other countries have their own rules.
The premium is a short-term capital gain on the expiry date, however long you held the put.
The difference between what you got and what you paid is a short-term gain or loss when you close. Rolling counts as closing one put and opening another.
No gain yet. The premium lowers the cost basis of the shares you buy, and their holding period starts the day you buy them, not the day you sold the put.
If you roll a put a few times and then get assigned, only the premium of the put that was assigned goes into the share cost. The ones you bought back were already their own gains or losses. AllInvestView books assignments the same way, so the premium isn't counted twice.
A put is a promise to buy. If the only reason for the trade is a fat premium, assignment leaves you holding a stock you never wanted, usually right after it fell.
An earnings report can move a stock more in a night than a month of premium covers. The PepsiCo example starts after its 8 October report for that reason.
In a broad sell-off several puts can be assigned in the same week. Keep some cash outside the trades so you aren't fully invested at the worst moment.
A put that pays far more than its neighbours is pricing in a bigger move. Compare the premium with the size of the drop that would hurt, not with other stocks.
Rolling a losing put again and again keeps your cash tied up and the risk open. Roll when the new strike and expiry are a trade you'd happily open today; if not, take the shares or close it.
Selling puts across a few accounts gets messy fast: premiums, rolls, assignments, and the shares that come with them. AllInvestView keeps the whole cycle together with the rest of your portfolio.
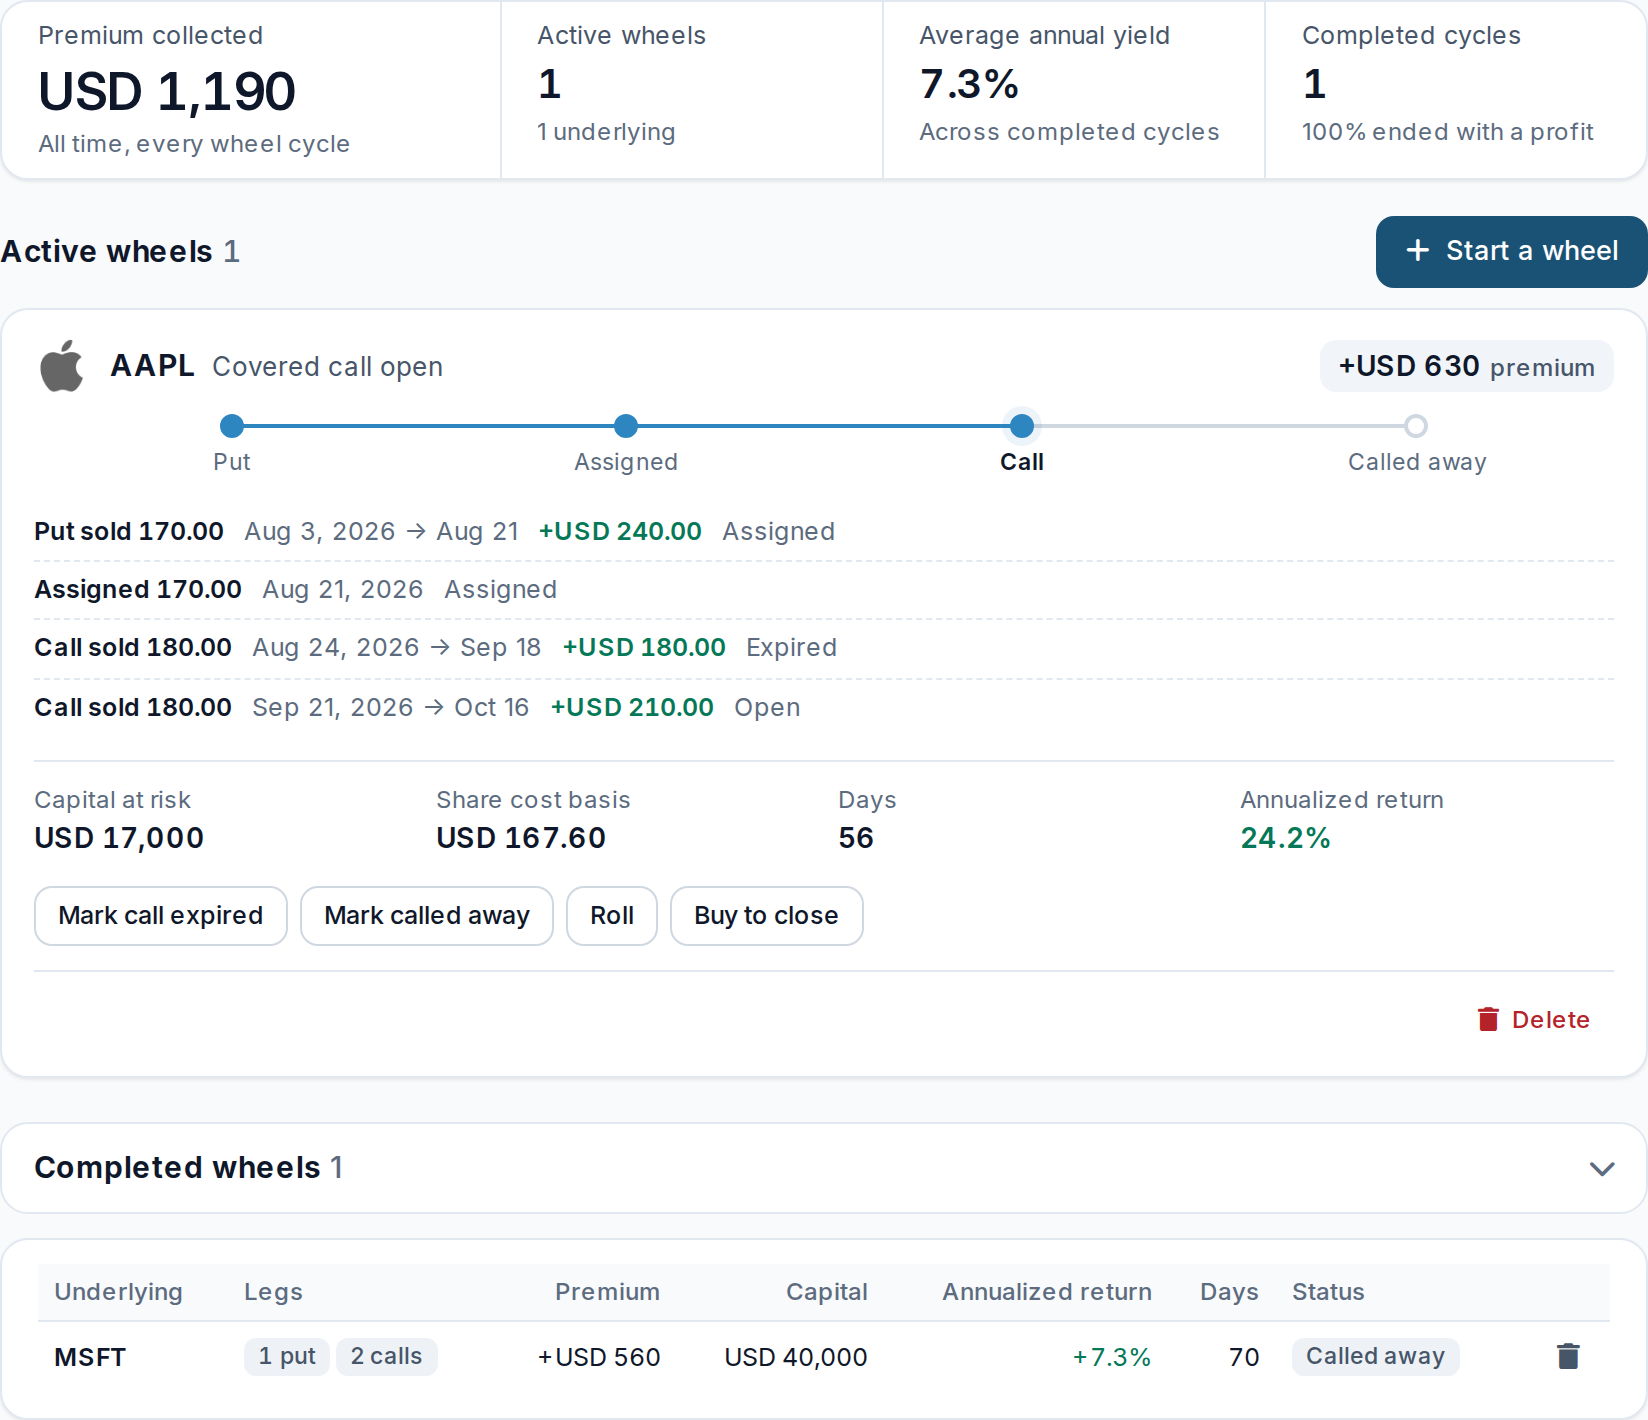
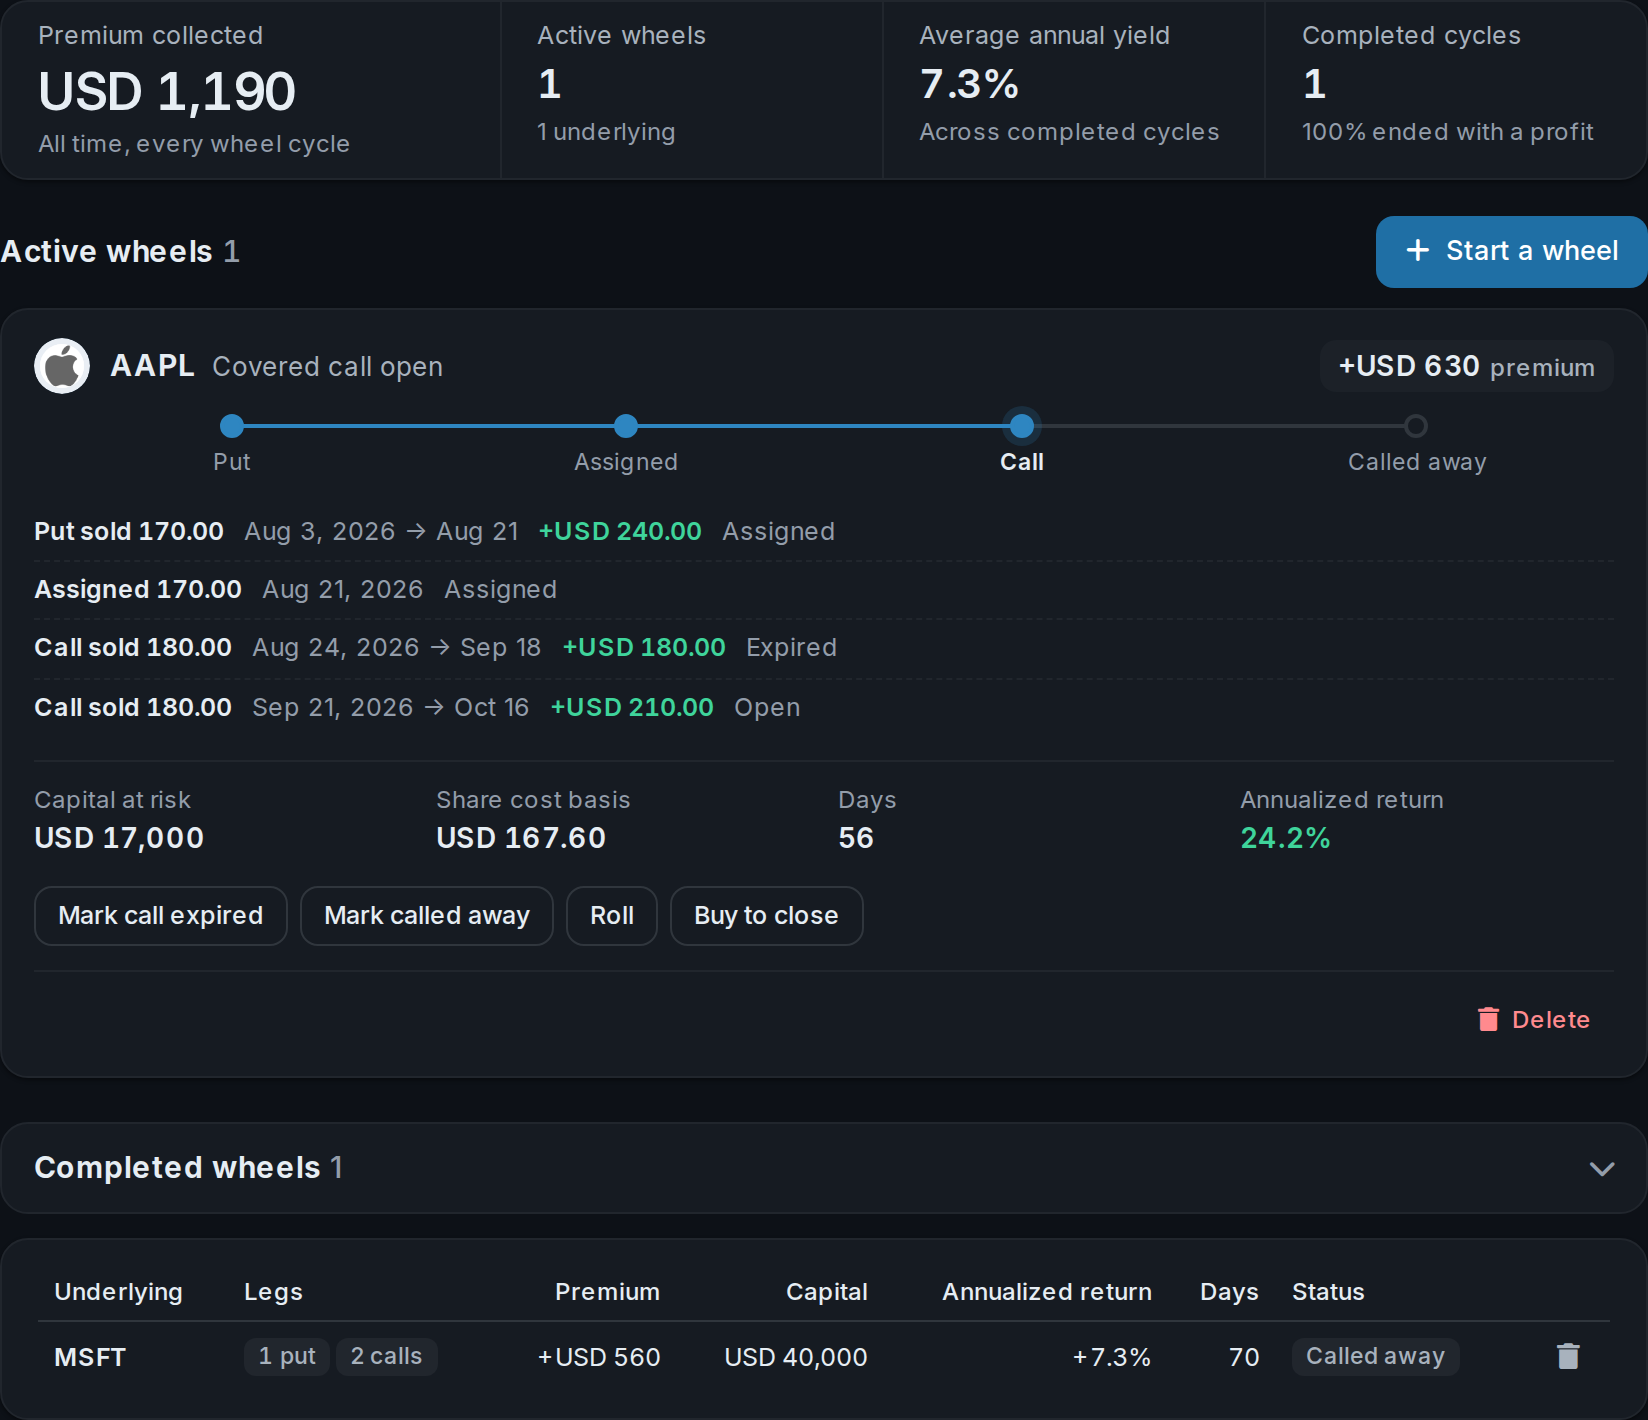
Each wheel shows the premium you've collected, your cost per share after assignment and the annualized return on the cash you set aside.
 AllInvestView
Track options next to your stocks, ETFs, bonds and dividends, from broker sync or a file import, with premium income, wheel cycles and the Greeks of every open position.
You sell a put option on a stock and keep enough cash to buy 100 shares at the strike price. You're paid a premium up front. If the stock stays above the strike, the put expires and you keep the premium. If it ends below, you buy the shares at the strike, and the premium lowers what they cost you.
The strike price times 100 for each contract. A $130 put needs $13,000 and a $25 put needs $2,500. Your broker holds that cash until the put expires, is bought back or is assigned. You also need options approval for selling cash-secured puts, which most brokers include in their first or second level.
You buy 100 shares at the strike price with the cash you set aside. The premium you kept lowers your cost per share: sell a $130 put for $0.95 and the shares cost you $129.05. From there you can hold them, sell them, or sell covered calls on them, which is the wheel strategy.
Yes. If the stock falls below the breakeven, the strike minus the premium, you're losing money on the shares you have to buy. The most you can lose is the strike minus the premium, times 100, if the stock goes to zero. That's less than buying the shares at today's price would lose, but your gain is capped at the premium.
It suits someone who wants to own a stock at a lower price and is happy to be paid while waiting. Over the 10 years to 23 October 2026, Cboe's S&P 500 PutWrite Index, which sells cash-secured S&P 500 puts every month, returned 8.5% a year against 15.3% for the S&P 500 with dividends. It fell less in 2008, 2020 and 2022 and lagged badly in strong years.
In the US, per IRS Publication 550, the premium of a put that expires is a short-term capital gain on the expiry date. If you buy the put back, the difference is a short-term gain or loss. If you're assigned, there's no gain yet: the premium lowers the cost basis of the shares, and their holding period starts the day you buy them.
A cash-secured put starts with cash and may end with shares. A covered call starts with 100 shares and may end with cash if they're called away. At the same strike and expiry their payoffs are almost the same. The wheel strategy uses both: puts until you're assigned, then calls until the shares are sold.
Checked on 24 October 2026.
Returns on the PepsiCo puts are before commissions. Deltas come from AllInvestView's Black-Scholes engine with a 3.94% rate, no dividend before expiry, and each put's implied volatility solved from its midpoint price. PutWrite and S&P 500 statistics are our calculations from the daily index values and SPY's dividend-adjusted closes.