A stock you'd hold through a bad year
The moment you're assigned, the wheel is plain stock ownership with a premium on top. If you wouldn't buy the shares and keep them, the premium isn't a reason to sell the put.
The wheel strategy is a loop of two option trades. You sell cash-secured puts on a stock you'd like to own until one is assigned and you buy 100 shares. Then you sell covered calls on those shares until they're called away, and the cash goes back to selling puts. You're paid a premium at every step. What you give up is most of the gain when the stock runs.
On 23 October 2026 Bank of America closed at $50.56. The first step of a wheel, selling the 20 November $48 put, paid $43 with $4,800 set aside. If BAC finished below $48 you'd own 100 shares at an effective $47.57 each and start selling calls on them.
$48 × 100 = $4,800
$48 − $0.43 = $47.57
($48 − $47.57) × 100 = $43, plus the call premium
The wheel is a cash-secured put and a covered call run one after the other. Steps 1 and 4 leave you holding cash, steps 2 and 3 holding shares. Here's each step with the Bank of America numbers.
Pick a stock you'd own, sell a put below the price and keep the strike × 100 in cash. If it expires, sell another.
If the stock ends below the strike, you buy 100 shares at the strike. The put premium lowers what they cost you.
Sell a call at or above your cost. You keep the premium, plus the dividend if you own the shares before the ex-dividend date.
If the stock ends above the call strike, your shares are sold at the strike and the cash is free for a new put.
The first put is a real trade at the 23 October close. Choose where BAC ends on each expiry, or pick one of the three stories, and compare the wheel with buying 100 shares the same day.

Bid $0.43, ask $0.47 at the close. BAC reported its quarter on 14 October. Its next dividend, $0.32 a share, goes to holders of record on 4 December: after this put expires, during the call that may follow.
$4,800 from the cash set aside. With the $43 kept, they cost you $47.57 each.
You sold the 18 Dec $48 call for about $0.67 ($67) and are owed the $32 dividend, paid 24 Dec. The shares go at $48 and the $4,800 is free again.
Step 1 is the real quote. Later trades are estimates, priced with Black-Scholes at the 26% implied volatility of BAC's November puts and allowing for the dividend; real premiums move with the market. The next put goes about 5% below the price, the call at $48 so it can't lock in a loss. Before commissions.
Nobody publishes a wheel index, but Cboe runs both halves by the book on the S&P 500. The PutWrite Index sells a one-month at-the-money put every month and keeps the strike value in Treasury bills. The BuyWrite Index holds the S&P 500 and sells a one-month at-the-money call against it. Here's what $10,000 in each became, against the S&P 500 with dividends reinvested.
Hover or tap the chart. Month-end values to 23 October 2026. S&P 500 measured with SPY, dividends reinvested. Index values from Cboe.
Over the decade both halves of the wheel earned about half what the S&P 500 did, and from 2016 to 2025 they beat it in one calendar year: 2022, when PutWrite lost 7.7% and BuyWrite 11.4% against 18.2%. What they gave in return was a smoother ride, with smaller falls and roughly 30% less volatility. Over the past year the gap closed: PutWrite 13.9%, BuyWrite 15.8%, S&P 500 14.4%. A wheel on one stock carries that company's risk on top, so the stock you pick matters more than the premium.
Each row is the 20 November put closest to a 0.25 delta, at the bid on 23 October 2026. These are stocks wheel traders often use, not recommendations. Cash needed is what one contract ties up.
| Stock | Put strike | Return, 28 days |
|---|---|---|
 INTCIntelEarnings 29 Oct | $77.50delta 0.24 | 3.19%on $7,750 |
 FFordEarnings 28 Oct | $11delta 0.31 | 2.91%on $1,100 |
 SOFISoFiEarnings 27 Oct | $13delta 0.22 | 2.69%on $1,300 |
 PFEPfizerEarnings 3 Nov | $29delta 0.31 | 1.72%on $2,900 |
 TAT&TReported 21 Oct | $20delta 0.27 | 1.35%on $2,000 |
 KOCoca-ColaEarnings 27 Oct | $90delta 0.29 | 1.12%on $9,000 |
 VZVerizonEarnings 26 Oct | $42delta 0.22 | 1.02%on $4,200 |
BACBank of AmericaReported 14 Oct | $48delta 0.21 | 0.90%on $4,800 |
The four richest premiums all had an earnings report inside the trade: Intel, Ford, SoFi and Pfizer. That extra premium is the market pricing a bigger move, and the move can go against you. Bank of America and AT&T had already reported. Price matters as much: a Ford contract ties up $1,100, a Coca-Cola one $9,000. Dividend yield is the last 12 months of dividends over the price.
The moment you're assigned, the wheel is plain stock ownership with a premium on top. If you wouldn't buy the shares and keep them, the premium isn't a reason to sell the put.
Busy strikes have tight spreads, so you get close to a fair price going in and out. The BAC $48 put had a 4-cent spread and 2,858 contracts open.
One contract is 100 shares. Keep enough cash spare that a few assignments in the same week don't leave the account sitting in one or two stocks.
There's no single right setting, but most wheel traders land near these. The strike ladder in our cash-secured put guide shows the premium and risk trade-off strike by strike.
| Decision | What most wheel traders do | In the BAC example |
|---|---|---|
| Put strike | About a 0.20 to 0.30 delta, below the price | $48, delta 0.21, 5.1% below |
| Expiry | About 30 to 45 days out | 28 days, the 20 November monthly |
| Call strike | At or above your cost per share | $48 against a $47.57 cost |
| Closing early | Buy back at about half the premium, then sell the next one | Buy the put back near $0.21 |
| Earnings | Let the report pass before opening a trade | Reported 14 October, next in January |
This is where most wheel losses come from. Say you were assigned BAC at $48 and a month later it's at $42. Your shares cost $47.57, so you're down $557 on paper, and a call at your cost pays almost nothing.
| With BAC at $42 | Premium, 28-day call | If the shares are sold |
|---|---|---|
| Sell the $48 call | $4 | +$47 at $48 |
| Sell the $45 call | $30 | −$227 at $45 |
| Sell the $43 call | $83 | −$374 at $43 |
| Sell the shares now | None | −$557 at $42 |
Results include the $43 put premium through the $47.57 cost. Call premiums use the same 26% volatility, with no dividend before expiry; after a drop like this volatility usually rises, so real calls would pay somewhat more. Most wheel traders keep selling calls at or above their cost and wait, or decide the stock no longer deserves the money and sell. Either way, a falling stock can't be fixed with premium: $4 a month doesn't cover $557.
Under IRS Publication 550 each premium is taxed by how its option ends, and two of them change the share numbers instead of being taxed on their own. Other countries have their own rules.
You have a short-term capital gain equal to the premium, dated the day it expires.
Nothing to report yet. The premium comes off the cost basis of the shares, and their holding period begins on the purchase date.
The call premium is added to what you sold the shares for. The gain is short- or long-term depending on how long you held the shares.
A covered call is "qualified" only if it has more than 30 days to run when you sell it and isn't too deep in the money. One sold in the money pauses the holding period of shares you've held a year or less. Calls that don't qualify, like a 28-day call, bring in the straddle rules, which can restart that holding period and defer losses.
Rolled puts are settled one by one: each put you closed is its own gain or loss, and only the last one, the put that was assigned, reduces the share cost. AllInvestView books wheels that way too, so a premium never counts twice.
It feels like more income, but when the strike plus the premium is under what the shares cost you, being called away turns a paper loss into a real one. With BAC at $42, the $43 call paid $83 and would lock in a loss of $374.
A wheel that has collected $500 in premiums on shares down $1,500 is $1,000 behind. Judge each cycle on premiums plus the change in the shares.
An in-the-money call is most likely to be exercised just before the stock goes ex-dividend, when the dividend is worth more than the time value left in the call. Check the date before you sell a call across it.
One stock is one bad quarter away from a stuck wheel. Spread the cash over a few names or an ETF, so a single assignment doesn't take over the account.
0.90% in 28 days works out at 11.7% a year only if you get the same premium every 28 days and never get stuck. The fair test is the whole cycle against holding the shares over the same dates.
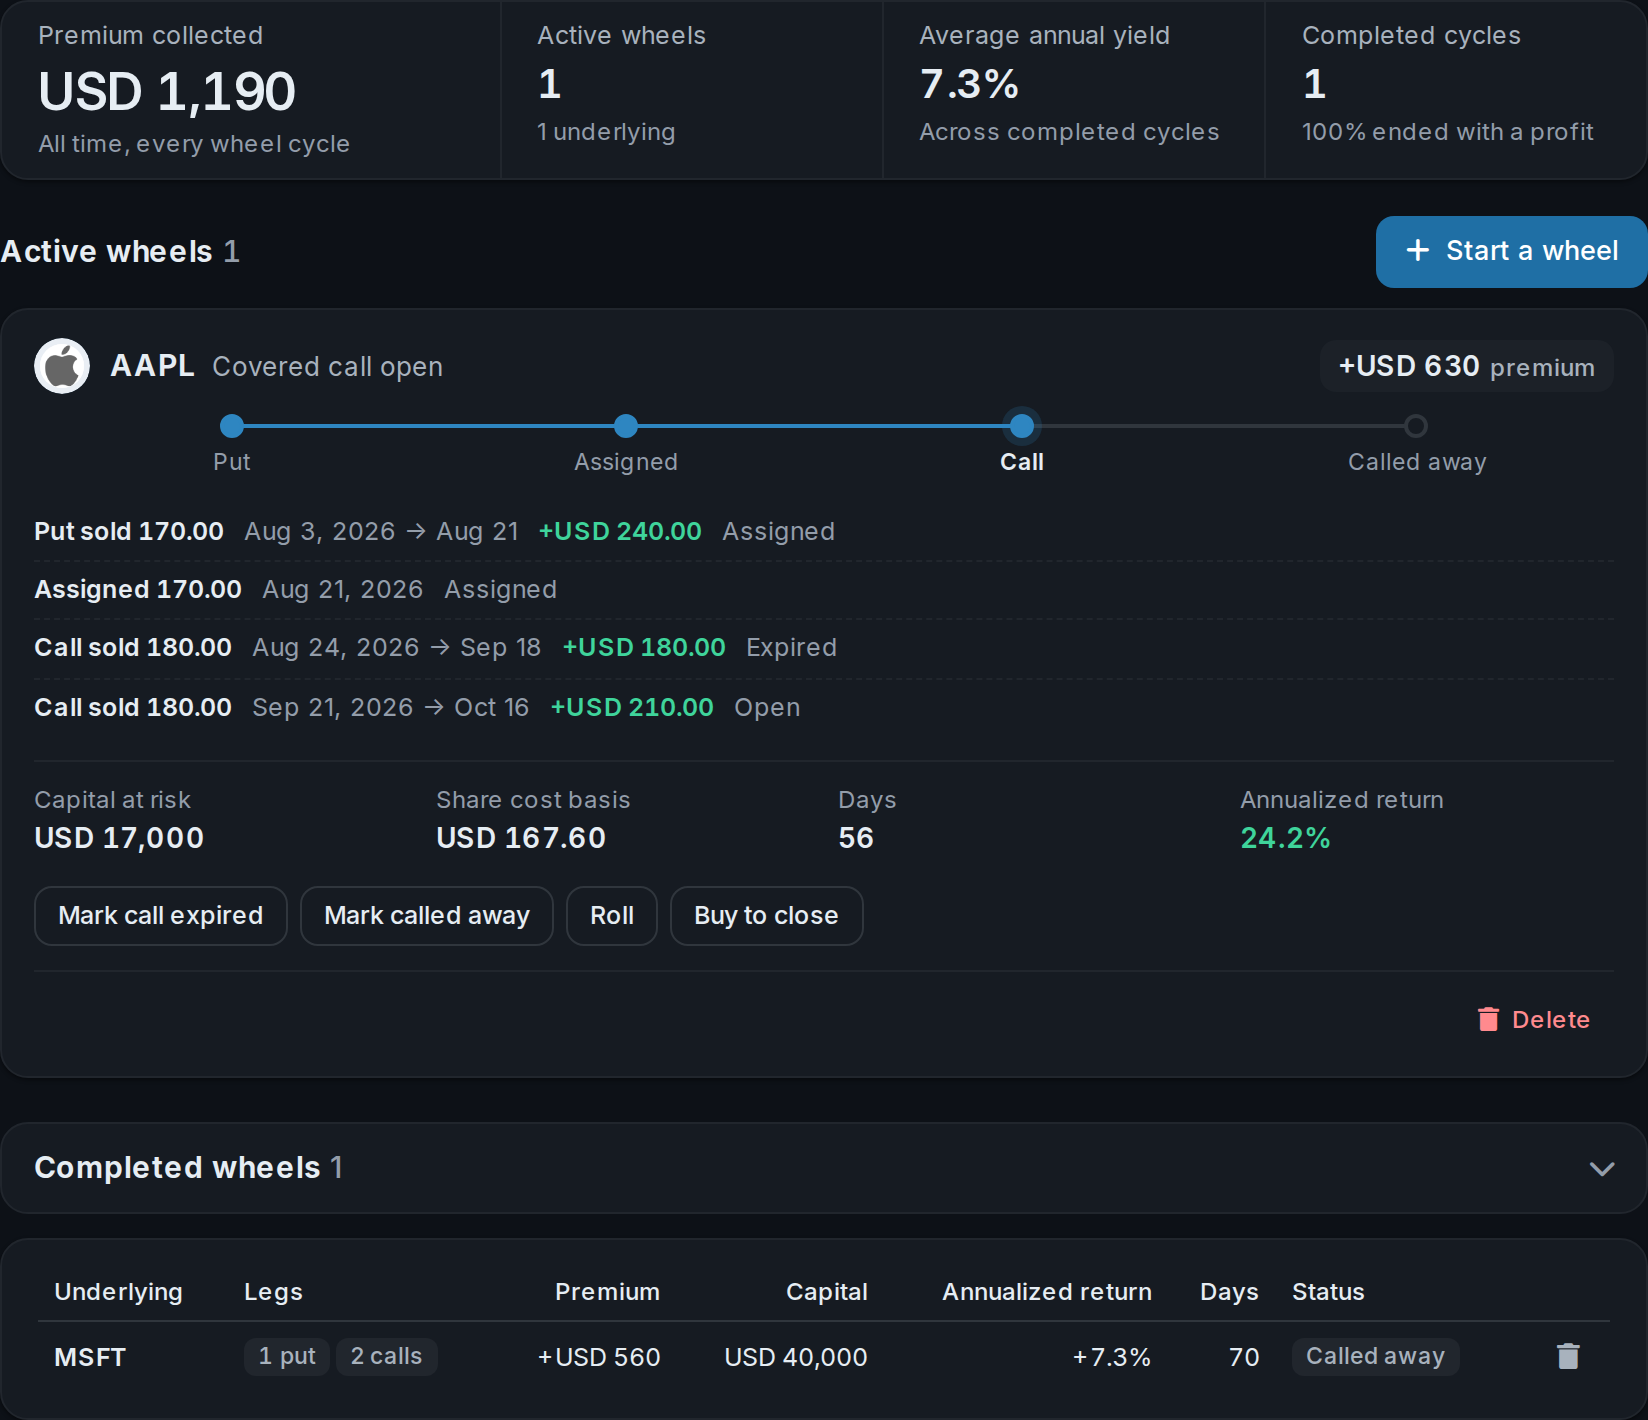
A wheel on a few stocks across a couple of brokers is a lot of moving parts: premiums, rolls, assignments and the shares in between. AllInvestView keeps each cycle together, next to the rest of your portfolio.
Every cycle carries its premium total, what the shares cost you after assignment and an annualized premium yield on the cash tied up.
 AllInvestView
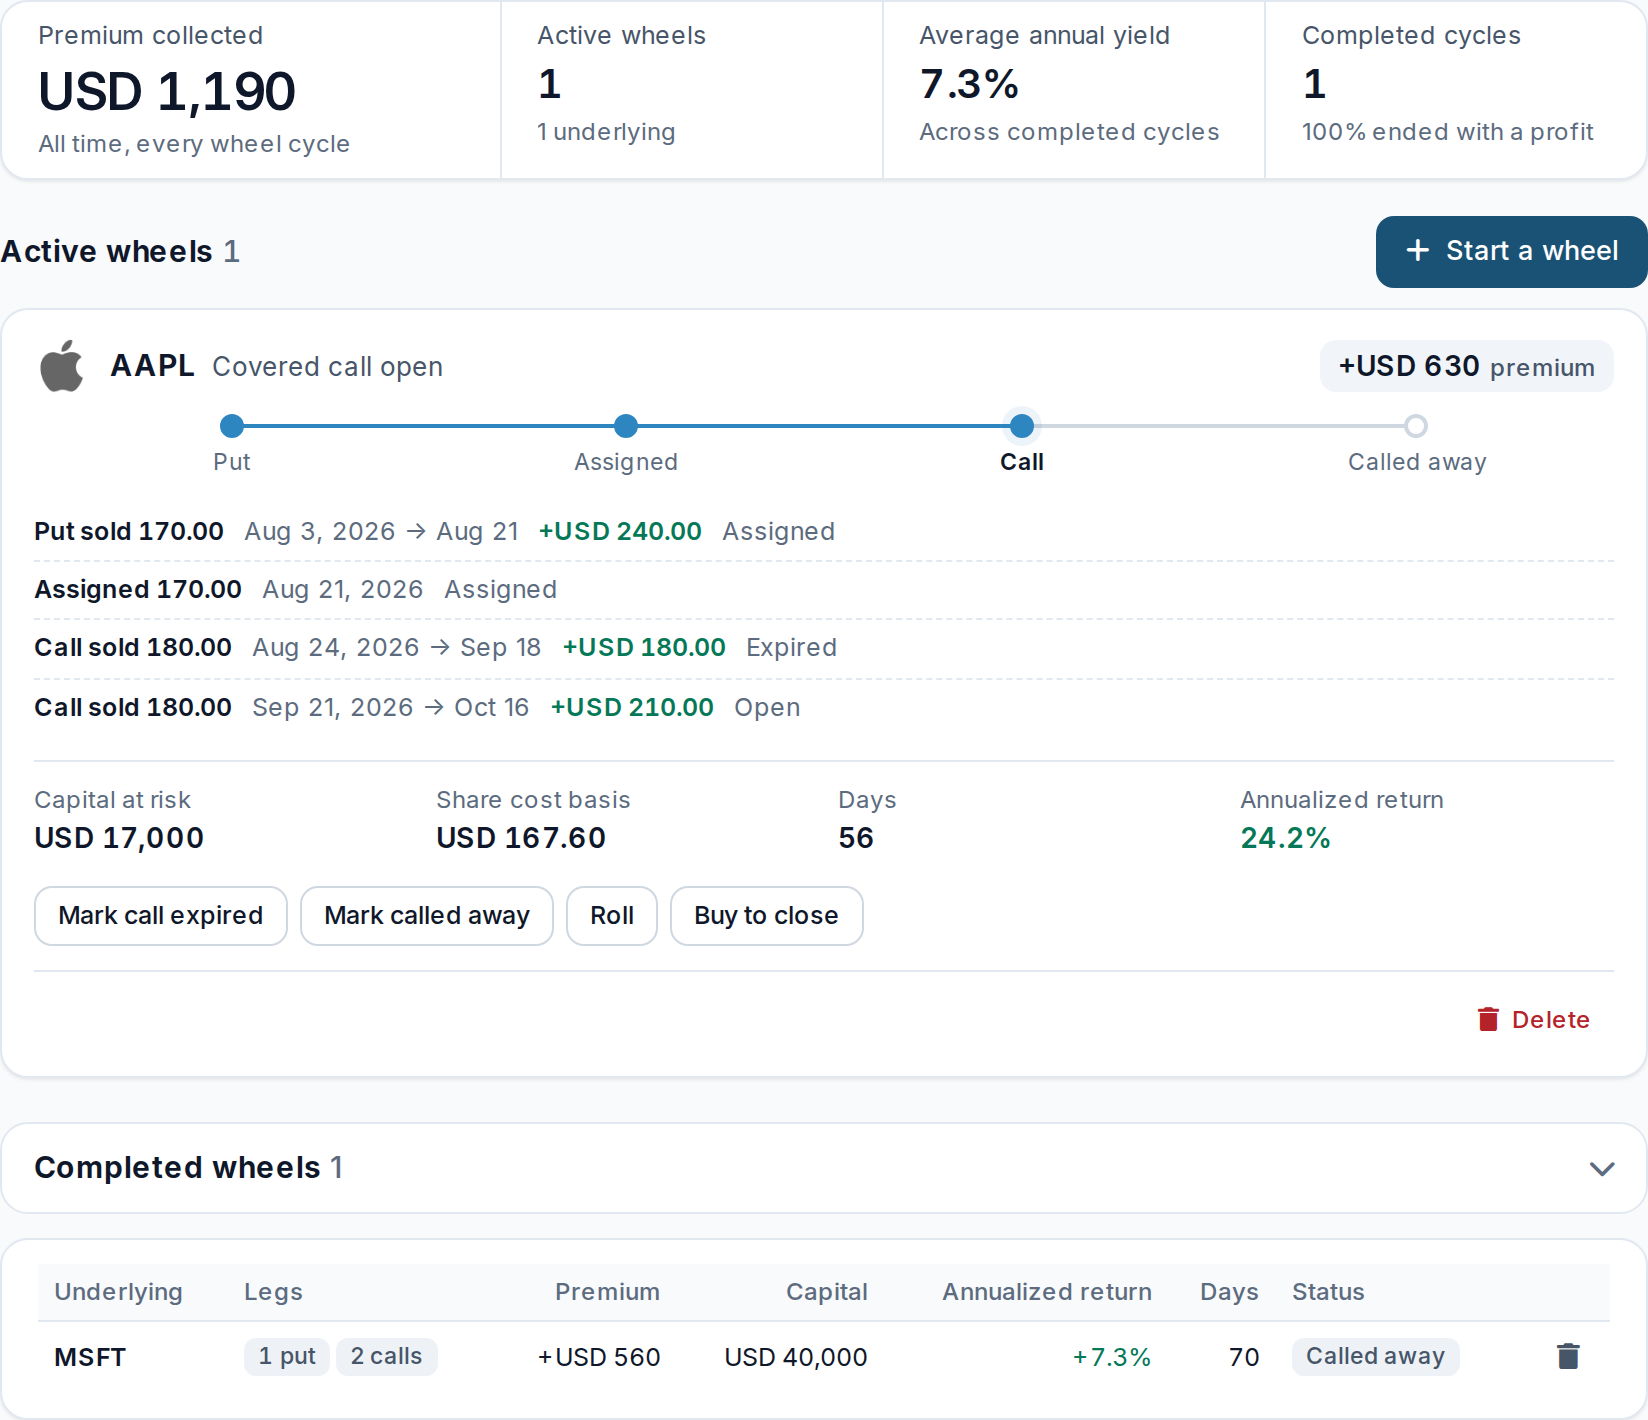
Wheels, stocks, ETFs, bonds and dividends on one dashboard, synced from your brokers or imported from a file, with monthly premium income and Greeks for each open option.
A repeating loop of two trades. You sell cash-secured puts on a stock until one is assigned and you buy 100 shares, then sell covered calls on those shares until they're called away. Then you start again with puts. Each step pays a premium; the trade-off is that you give up most of the gain if the stock rises sharply.
Enough to buy 100 shares at the put's strike for each contract: $4,800 for a $48 put on Bank of America, $1,100 for an $11 put on Ford, $9,000 for a $90 put on Coca-Cola. Your broker also has to approve you for cash-secured puts and covered calls, which most include in their first or second options level. Keeping some cash spare helps if several puts are assigned at once.
It earns steady premium, but it hasn't beaten simply owning the market over long periods. Over the 10 years to 23 October 2026, Cboe's PutWrite and BuyWrite indexes, which run the two halves of the wheel on the S&P 500, returned 8.5% and 7.9% a year against 15.3% for the S&P 500 with dividends. They fell less in crashes and trailed in strong years.
Stocks you'd be happy to own for years, with busy options and a share price your account can carry. Bank of America, AT&T, Pfizer, Verizon, Coca-Cola, Ford, SoFi and Intel are all popular with wheel traders. A high premium usually means an earnings report or a bigger expected move, not a better deal.
You own shares worth less than you paid. You can keep selling calls at or above your cost and wait, which pays little while the stock is down, sell calls at a lower strike for more premium, which locks in a loss if they're exercised and the strike plus the premium is below your cost, or sell the shares. Premium alone rarely makes up a large fall.
Many wheel traders sell puts at about a 0.20 to 0.30 delta, 30 to 45 days out, and calls at or above their cost per share. A higher delta pays more premium and makes assignment more likely. Many also buy the option back once about half the premium is earned.
In the US, per IRS Publication 550, premiums from options that expire are short-term capital gains. An assigned put's premium lowers the cost basis of the shares, and a called-away call's premium is added to the sale price, so both end up in the gain on the shares. Whether that gain is short- or long-term depends on how long you held the shares.
Checked on 24 October 2026.
Returns on the puts are before commissions. Deltas come from AllInvestView's Black-Scholes engine with a 3.94% rate and each put's implied volatility solved from its midpoint price. Index and S&P 500 statistics are our calculations from Cboe's daily values and SPY's dividend-adjusted closes.