The call expires worthless
You keep the $180 and the shares, and you can sell another call. If PG fell, the premium softens the loss but doesn't stop it.
At $150: shares −$1,102, covered call −$922
A covered call means you own 100 shares of a stock and sell a call option on them. The buyer pays you a premium now for the right to buy your shares at the strike price until the option expires. If the stock stays below the strike, you keep the shares and the premium. If it ends above, your shares are sold at the strike. You've swapped the gains above the strike for cash today.
On 23 October 2026 Procter & Gamble closed at $161.02. Selling the 20 November $165 call on 100 shares paid $180. If PG ends below $165 you keep the shares and the $180. If it ends above, the shares go at $165 and you make $578 in 28 days.
($165 − $161.02) × 100 + $180 = $578
$161.02 − $1.80 = $159.22
$159.22 × 100 = $15,922, if PG went to zero
The trade is real, at the 23 October close. Drag the price PG might close at on 20 November and compare selling the call with simply holding the 100 shares.
Bid $1.80, ask $2.04 at the close. PG went ex-dividend on 23 October ($1.0885 a share) and its next earnings report is due in January, so nothing scheduled falls inside this call.
You keep the $180 and the shares, and you can sell another call. If PG fell, the premium softens the loss but doesn't stop it.
The shares barely move and the $180 is yours. This is the market covered calls are built for: flat or slowly rising.
They're sold at $165 whatever the price. You keep the premium and the gain up to the strike, and miss everything above it.
The same 20 November expiry, four PG strikes, all at the bid on 23 October 2026. A strike closer to the price pays more, and leaves less of the upside for you.
| Call strike | Premium | If PG doesn't move | If called away |
|---|---|---|---|
| $160in the money | $410delta 0.58 | $3081.91%, called | $3081.91% |
| $165the example | $180delta 0.35 | $1801.12% | $5783.59% |
| $170 | $58delta 0.16 | $580.36% | $9565.94% |
| $175 | $17delta 0.07 | $170.11% | $1,4158.79% |
Delta tells you how far the call moves with the stock: at 0.35 it gains about 35 cents when PG rises $1. Traders also read it as a rough chance of the call finishing in the money. Many covered call sellers stay between 0.20 and 0.35: enough premium to matter, with the strike above the price. The $160 call pays the most, but PG is already above its strike: $1.02 of the $4.10 is value you already owned, and unless PG falls the shares go. Returns are on $16,102 of shares, before commissions.
The PG $165 call at five expiries, at the 23 October bid. Shorter calls mean more trades, and the spread takes a bigger bite of each one.
| Expiry | Days | Premium | Return | Same rate for a year |
|---|---|---|---|---|
| 30 Oct 2026weekly | 7 | $35 | 0.22% | 11.3% |
| 6 Nov 2026 | 14 | $90 | 0.56% | 14.6% |
| 20 Nov 2026monthly | 28 | $180 | 1.12% | 14.6% |
| 18 Dec 2026 | 56 | $305 | 1.89% | 12.3% |
| 15 Jan 2027 | 84 | $440 | 2.73% | 11.9% |
The 14- and 28-day calls paid the most per day here, about $6.43 against $5 for the weekly. And the weekly is worse than it looks: its 14-cent spread is 40% of the bid, so getting out early costs a lot. Most sellers settle on 30 to 45 days. In the US a call with more than 30 days to run (and a strike that isn't deep in the money) counts as a qualified covered call, which keeps the tax simple; the 28-day call doesn't.
You don't have to wait for expiry. Each choice below uses the PG quotes from the 23 October close to show the trade-off; a real roll happens later, at that day's prices. The rolling options guide walks through every kind of roll with real Apple quotes.
Once the call has lost most of its value, buying it back frees the shares for a new call. Many sellers close at about half the premium, so the last few cents don't keep the shares tied up.
Buy back the call and sell a later one at the same strike. You collect more premium and push the date back, but the cap on the shares stays where it was.
When the stock is pushing through the strike, move to a higher strike further out. It often costs a little now, and lifts the price you'd sell at.
Early assignment is rare while a call still has time value, because the buyer would get more by selling it. The exception is the day before a stock goes ex-dividend: if the call is in the money and the dividend is worth more than the time value left, the buyer may exercise to collect the dividend, and your shares leave a day early. PG's next ex-dividend date is due in late January, after every expiry in the tables above, so these trades are clear of it.
Cboe runs three covered call indexes on the S&P 500. Each holds the index and sells a one-month call every month: at the money (BuyWrite, BXM), 2% out of the money (BXY) or at a 0.30 delta (BXMD). Pick one and compare it with the S&P 500, year by year.
Hover or tap a year. The 30-delta index beat the S&P 500 in 5 of the 18 full years from 2008 to 2025. 2026 runs to 23 October. S&P 500 measured with SPY, dividends reinvested. Index values from Cboe.
Two things stand out. Covered calls trailed the S&P 500 in most years and won mainly when stocks fell or stalled: 2008, 2011, 2015 and 2022, plus 2009 for the two out-of-the-money indexes, which had fallen less before the March low. And the strike made the biggest difference: selling at the money gave up so much of the rally that it earned 7.9% a year over the decade, while a call 2% out or at a 0.30 delta earned about 11%. They fell less in the crisis, but a covered call isn't a hedge: in 2008 all three still lost close to 30%.
These funds own the stocks, sell calls on them and pay out every month. The yield is the last 12 months of payouts over the 23 October 2026 price. Total return counts the payouts reinvested.
| Fund | Yield, 12 months | Return a year, 3 years |
|---|---|---|
 JEPIJPMorgan Equity Premium Income | 8.0% | 11.2%vs SPY 23.3% |
 XYLDGlobal X S&P 500 Covered Call | 10.3% | 14.4%vs SPY 23.3% |
 SPYINEOS S&P 500 High Income | 12.0% | 18.0%vs SPY 23.3% |
JEPQJPMorgan Nasdaq Equity Premium Income | 11.8% | 20.3%vs QQQ 26.3% |
QYLDGlobal X Nasdaq-100 Covered Call | 11.8% | 16.2%vs QQQ 26.3% |
Every fund paid a yield many times the index's (SPY 1.0%, QQQ 0.4%), and every one trailed its plain index fund over three years, because part of each payout is upside sold to someone else. The strike isn't the whole story: JEPI also picks its own, more defensive stocks, and it trailed SPY by the widest gap. Over the past 12 months, a year when stocks rose more slowly, QYLD returned 18.0% against 15.9% for QQQ and XYLD 15.2% against 14.4% for SPY. A fund saves you the trading; doing it yourself lets you choose the stock, the strike and the tax timing.
Three ways to collect call or put premium on the same stock, priced on PG at the 23 October close.
| Strategy | What you hold | Money tied up | The catch |
|---|---|---|---|
| Covered call | 100 shares, short one call | $16,102 in shares, earning $180 and any dividends | Gains capped at the strike; the shares can still fall |
| Cash-secured put | Cash, short one put | Strike × 100 in cash until expiry | Same shape as a covered call at the same strike, but no dividends until you own the shares |
| Poor man's covered call | A long-dated call instead of the shares, short a near-term call | $4,000 for the PG January 2028 $130 call (delta 0.77), selling the same $165 call: $180 is 4.5% of it | No dividends, the long call loses time value, and a 10% fall in PG costs it about $1,300, a third of what you paid |
The poor man's version is a diagonal spread: the premium looks bigger against the money you put up, and so does every move. Run the covered call calculator with your own shares and strike before you sell one.
Under IRS Publication 550 the premium isn't taxed when you sell the call. It's taxed when the call ends, and how depends on how it ends. Other countries have their own rules.
You've made a short-term capital gain of the full premium, booked the day the call expires, however long you've owned the shares.
The difference between what you sold it for and what you paid to close is usually a short-term gain or loss, on the day you close.
The premium is added to what you got for the shares, and the gain is short- or long-term by how long you held the shares.
A call with more than 30 days to expiry that isn't deep in the money is "qualified" and taxed as above. Write one that doesn't qualify, like the 28-day PG call, and the straddle rules can reset a short holding period on the shares and defer losses. A qualified call that's in the money still pauses the holding period of shares you've owned a year or less.
Brokers and trackers often show a called-away call as two results, the option and the share sale. For US tax the premium still belongs in the sale proceeds of the shares, so it takes their holding period.
If being called away would upset you, don't sell the call. Buying it back after a jump costs more than you were paid, and that's the price of changing your mind.
$180 covers a $1.80 drop in PG, about 1%. Below $159.22 the covered call loses money almost dollar for dollar with the shares.
Of the strikes above the price, the closest one pays the most and leaves you the least room. The ten years above show what that cost: 7.9% a year at the money against about 11% a little further out.
Premium is high before earnings because a big move is likely, in either direction. And an in-the-money call the day before an ex-dividend date can be exercised early, taking the dividend with the shares.
A short call on shares you've held almost a year can reset or pause that holding period, turning a long-term gain into a short-term one. Check whether the call is qualified before you sell it.
A covered call is two positions that only make sense together. AllInvestView keeps both in one portfolio, across every broker you use.
The Wheel view keeps covered calls and the shares under them in one cycle, with the premium collected, your cost per share and an annualized yield. In the options book, short calls on stocks you hold are labelled as covered calls, with Greeks on every open option.
 AllInvestView
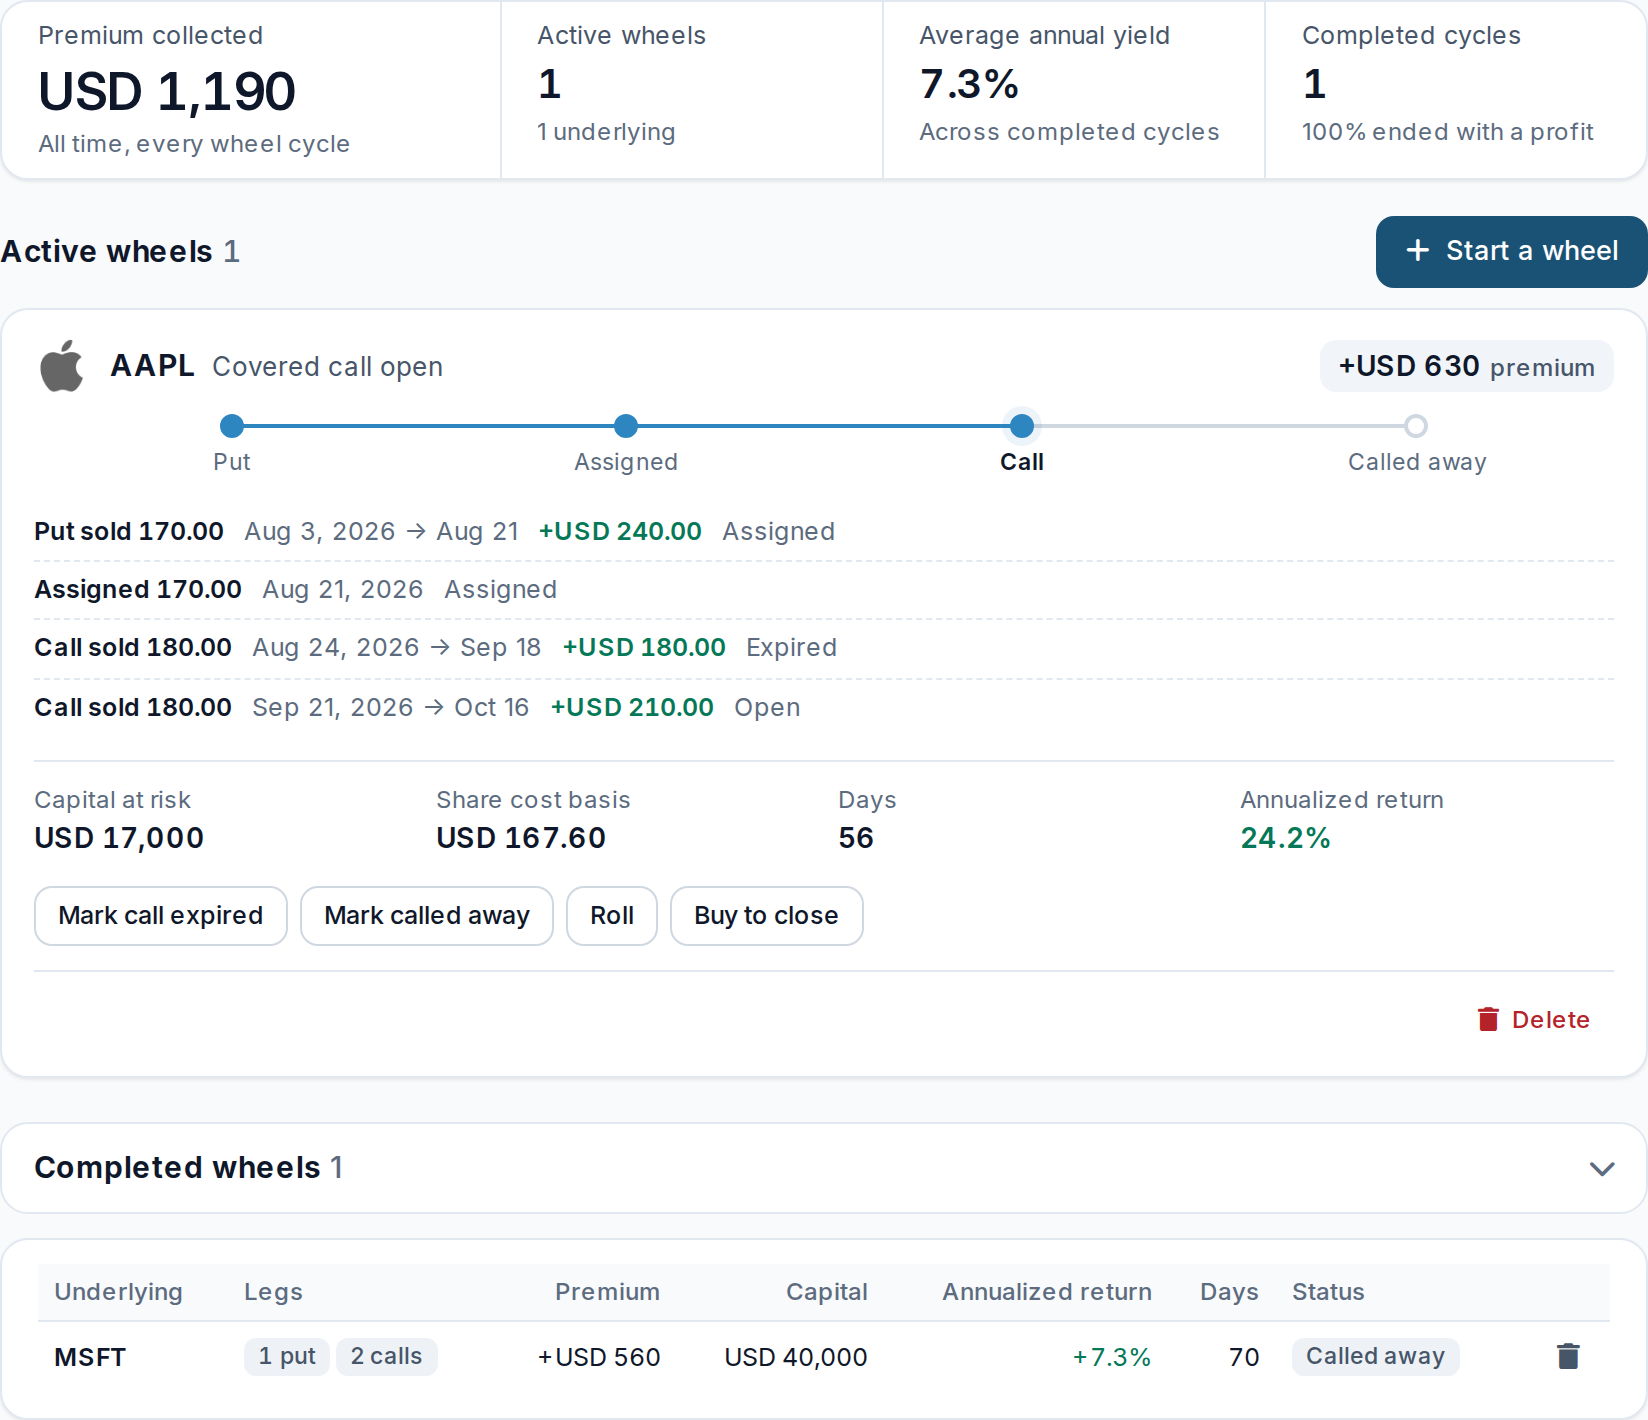
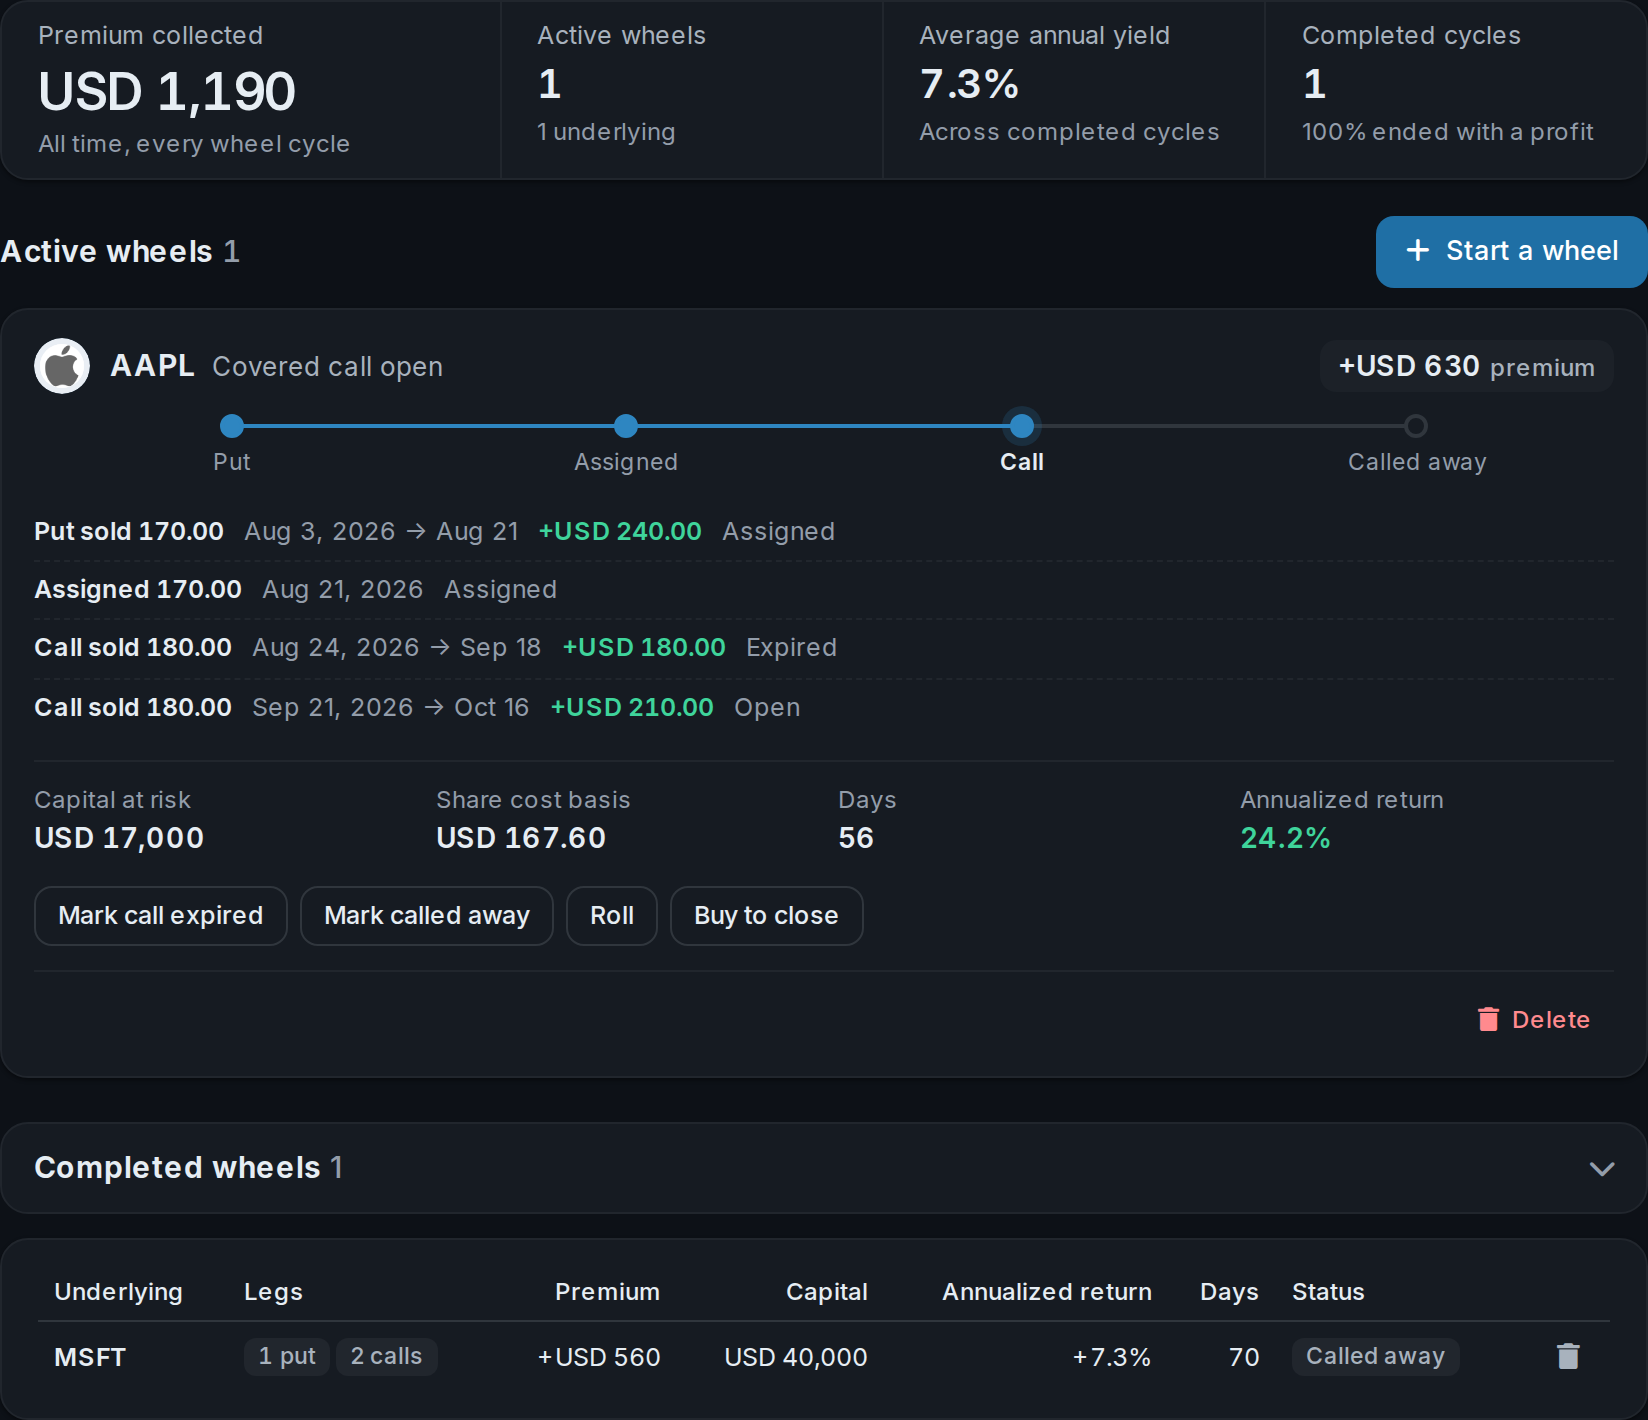
Calls, shares, ETFs, bonds and dividends on one dashboard, synced from your brokers or imported from a file, with the premium you've collected each month.
You own 100 shares of a stock and sell someone the right to buy them from you at a set price, the strike, until a set date. They pay you a premium for that right. If the stock stays below the strike, you keep the shares and the premium. If it ends above, your shares are sold at the strike and you keep the premium too.
On one trade, the premium plus any rise up to the strike. Selling a $165 call on 100 Procter & Gamble shares at $161.02 paid $180 on 23 October 2026, 1.12% in 28 days, and up to $578 (3.59%) if the shares were called away. Over the 10 years to October 2026, Cboe's 30-delta BuyWrite Index returned 10.9% a year against 15.3% for the S&P 500 with dividends.
Yes. The call doesn't protect the shares; the premium only lowers your breakeven. With PG bought at $161.02 and $1.80 of premium, you lose money below $159.22, almost dollar for dollar with the stock. You can also miss gains: if PG jumped to $175, the covered call made $578 against $1,398 for the shares alone.
Your 100 shares are sold at the strike price and you keep the premium. It usually happens at expiry when the stock is above the strike, but US stock options can be exercised early, most often the day before the stock goes ex-dividend. After that you can buy the shares back, sell a cash-secured put, or move on.
Many sellers pick a strike above the price at a delta of about 0.20 to 0.35, 30 to 45 days out. A closer strike pays more but leaves less room for the stock to rise. Over 10 years, Cboe's index selling at-the-money calls returned 7.9% a year, while its 2% out-of-the-money and 30-delta versions returned 10.6% and 10.9%.
They do the same job for you and pay out monthly. Their yields were 8% to 12% over the 12 months to 23 October 2026, but over three years every one returned less than its plain index fund: JEPI 11.2% a year and SPYI 18.0% against 23.3% for SPY, QYLD 16.2% and JEPQ 20.3% against 26.3% for QQQ.
In the US, per IRS Publication 550, the premium from a call that expires is a short-term capital gain on the expiry date. A call you buy back usually gives a short-term gain or loss. If your shares are called away, the premium is added to the sale price, and the gain is short- or long-term by how long you held the shares. Calls with 30 days or less to run, or deep in the money, can bring in the straddle rules.
Checked on 24 October 2026.
Returns are before commissions. Deltas come from AllInvestView's Black-Scholes engine with a 3.94% rate and each call's implied volatility solved from its midpoint price. Index statistics are our calculations from Cboe's daily values and SPY's dividend-adjusted closes.