1. Home
  2. Australian tax
  3. Franking credits calculator

Franking Credits Calculator

Enter a dividend and its franking. You see the credit attached, the grossed-up amount the ATO taxes you on, and whether that credit comes back to you as a refund or still leaves tax to pay.

Your dividend

Enter the dividend as
A$
Enter an amount above zero, up to A$10 billion.
100%
Company tax rate it was franked at

Your dividend statement shows the franking credit and the rate used.


Franking credit
 
Grossed-up dividend
 
Tax at your rate
 
You keep


Same dividend, two tax rates

A$1,000 fully franked at a 15% marginal rate

The company paid 30% tax on the profit, and you pay 15%. The credit is worth more than your tax on the dividend.

Franking credit
A$428.57
Tax at 15%
A$214.29
Refund
A$214.29

You are taxed on A$1,428.57, the credit covers all of it, and the A$214.29 left over is paid to you. A$1,000 of dividend ends up as A$1,214.29 in your pocket.

A$1,000 fully franked at the 45% top rate

Here your rate is above the company rate, so the credit pays most of the tax and you top up the rest.

Franking credit
A$428.57
Tax at 45%
A$642.86
Top-up tax
A$214.29

Tax on the A$1,428.57 grossed-up dividend is A$642.86. The credit leaves A$214.29 to pay, so you keep A$785.71.

Calculate fully and partially franked dividends

A$700 fully franked at 30%

The credit is A$700 × 30/70 = A$300. Add it to the cash dividend for A$1,000 of grossed-up income. At a selected 30% personal tax rate, the A$300 tax is covered by the credit, so you keep A$700.

The same A$700 dividend, 60% franked

Only A$420 is franked. Its credit is A$420 × 30/70 = A$180. The other A$280 carries no credit. Grossed-up income is A$880, giving A$264 tax at 30%. Subtract the A$180 credit and you pay A$84, keeping A$616.

A refund when the holder owes no income tax

An eligible Australian resident individual receives the fully franked A$700 dividend above and owes no income tax or Medicare levy. At a 0% rate the calculator gives A$300 refunded and A$1,000 kept. The credit is refundable even though the holder owes no tax. For the 60% franked dividend, the refund is A$180 and the holder keeps A$880.

These examples use the 30% company rate and leave the Medicare box unticked. The dividend statement supplies the actual franking amount and company rate.

How franking credits work

An Australian company pays tax on its profit before it pays you a dividend. Franking passes that tax on to you as a credit, so the same profit is not taxed twice. You add the credit to the cash you received, pay tax on the total at your own rate, and the credit comes off that tax.

Franking credit = cash dividend × franking % × company rate ÷ (1 − company rate)

At 30%, every dollar of fully franked dividend carries about 43 cents of credit. At the 25% base rate entity rate it is about 33 cents.

  • Fully franked means the whole dividend carries a credit at the company's rate.
  • Unfranked means no company tax was attached, often because the profit was earned overseas or was not taxed in Australia. The whole cash amount is taxed as ordinary income.
  • Partially franked splits the payment. The franked part earns a credit and the unfranked part does not, and your statement shows the split.

The 45-day rule and your tax return

Holding long enough to claim the credit

Hold ordinary shares at risk for 45 continuous days, not counting the days you buy and sell, within the period that ends 45 days after they go ex-dividend. Preference shares need 90 days within a 90-day window. Buying just before the ex-dividend date and selling straight after does not earn the credit.

The small shareholder exemption covers you when your franking credits for the year come to A$5,000 or less and no related payment passes the dividend's benefit to someone else.

Item 11 on the individual return

11S
Unfranked amount
11T
Franked amount
11U
Franking credit

You report the cash dividend and the credit separately. The ATO adds them together as income and gives you the credit back as an offset, which is where a refund comes from.

Questions about franking credits

How do I track franking credits across several holdings?

Keep the cash dividend, franked and unfranked amounts, and attached credit from each dividend statement. AllInvestView keeps franking with each company dividend and the Australian filing pack totals the amounts for item 11 alongside your capital gains.

What is a franking credit?

It is the company tax already paid on the profit behind a dividend. A company taxed at 30% that pays you A$70 fully franked attaches a A$30 credit, and you are treated as receiving A$100 of income with A$30 of tax already paid on it.

Can I get a franking credit refund if I pay no income tax?

Yes, if you are an eligible Australian resident individual. When you owe no income tax or Medicare levy and have no other tax debt to offset, the whole credit can be refunded. A fully franked A$700 dividend at a 30% company rate carries A$300 of credit, so you keep A$1,000 including the refund.

What does partially franked mean?

Only the franked part carries a credit. A 60% franked A$700 dividend at a 30% company rate has A$420 franked, A$280 unfranked and A$180 of credit. Your taxable dividend income is A$880: the whole cash payment plus the credit.

Why would a fully franked dividend carry a smaller credit?

A company franks at its tax rate for imputation, which is 25% for many smaller companies that qualify as base rate entities. A fully franked A$1,000 dividend carries A$333.33 of credit at 25%, or A$428.57 at 30%. Your statement shows the credit and the rate used.

What is the 45-day rule?

To claim the credit you must hold ordinary shares at risk for 45 continuous days, not counting the days you buy and sell, within the period that ends 45 days after they go ex-dividend. Preference shares need 90 days. The small shareholder exemption covers you when your franking credits for the year come to A$5,000 or less and no related payment passes the dividend's benefit to someone else.

Where do franked dividends go on my tax return?

Item 11 of the individual return: unfranked amounts at 11S, franked amounts at 11T and franking credits at 11U. Check any prefilled figures against your dividend statements.

Does the Medicare levy apply to franked dividends?

The grossed-up dividend is included in your taxable income, and franking credits can offset the Medicare levy. Tick the box if you pay the standard 2% levy; lower incomes pay less or none.

Track franking credits across your whole portfolio

Track franking credits alongside the cash dividend from each Australian company you hold. AllInvestView keeps the cash and the franking credit together for every payment, then the Australian filing pack totals the year into 11S, 11T and 11U, next to your capital gains at item 18 and foreign dividends at item 20.

  • Franking recorded per dividend, or set once for a holding
  • Items 11, 18 and 20 in AUD, with the evidence behind each figure
  • Broker sync and file imports, so nothing is typed twice
See the Australian tax report

Start free. No card required.

Open the Australian filing pack

AllInvestViewAustralian filing pack
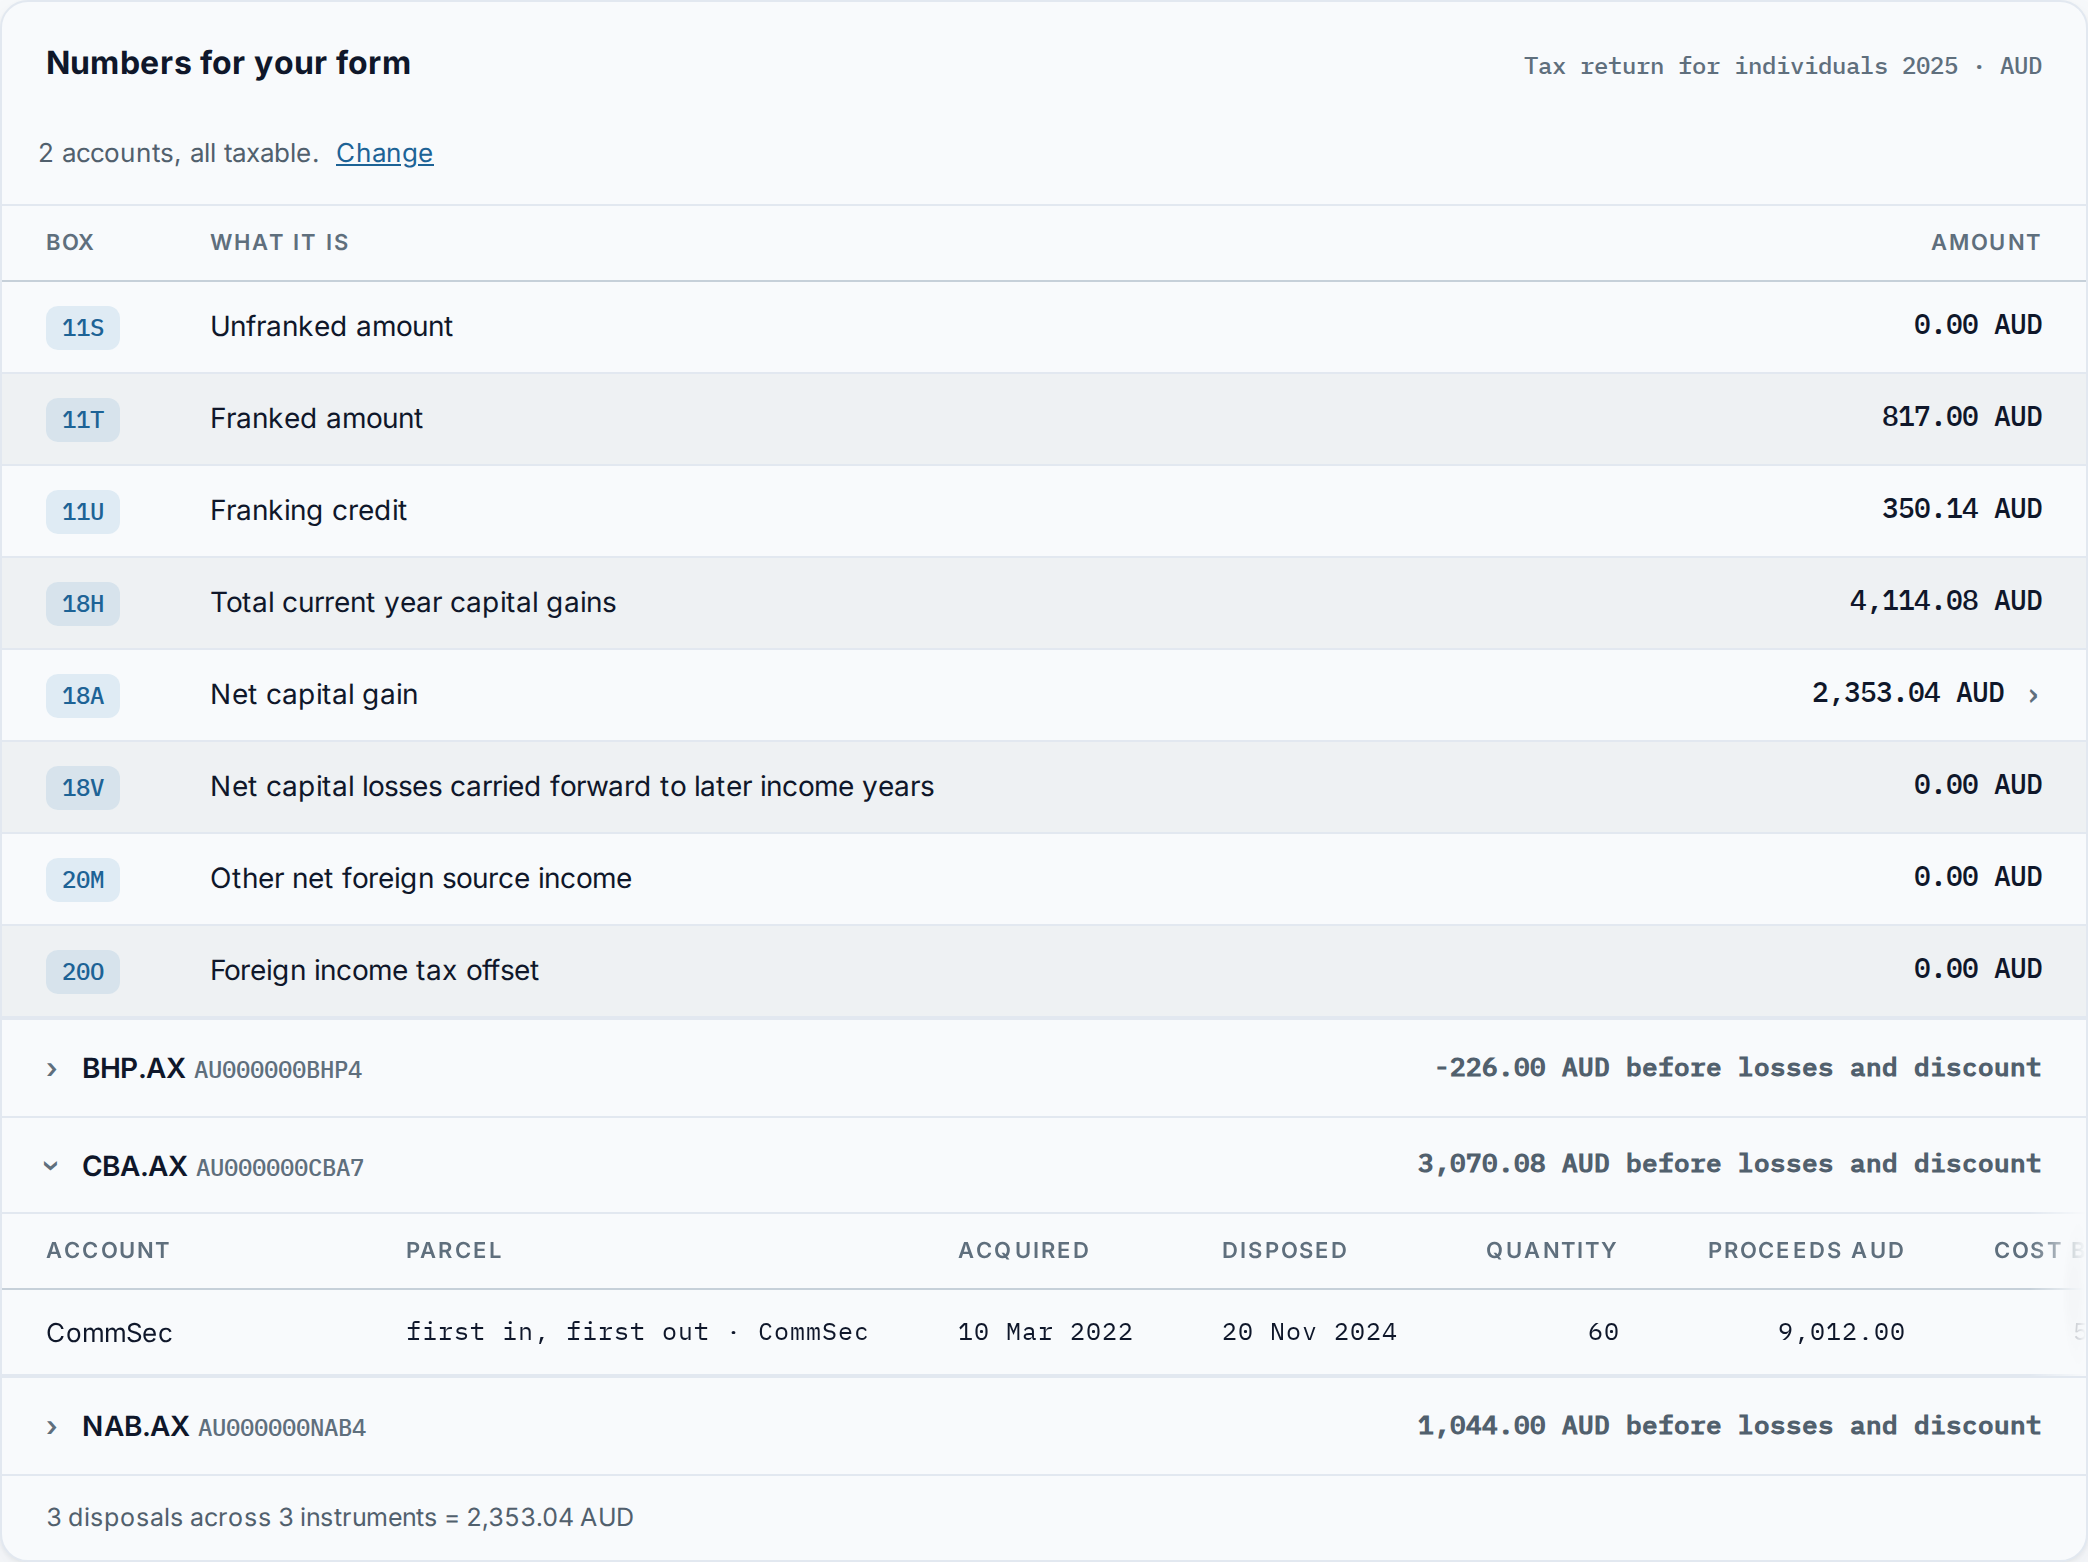
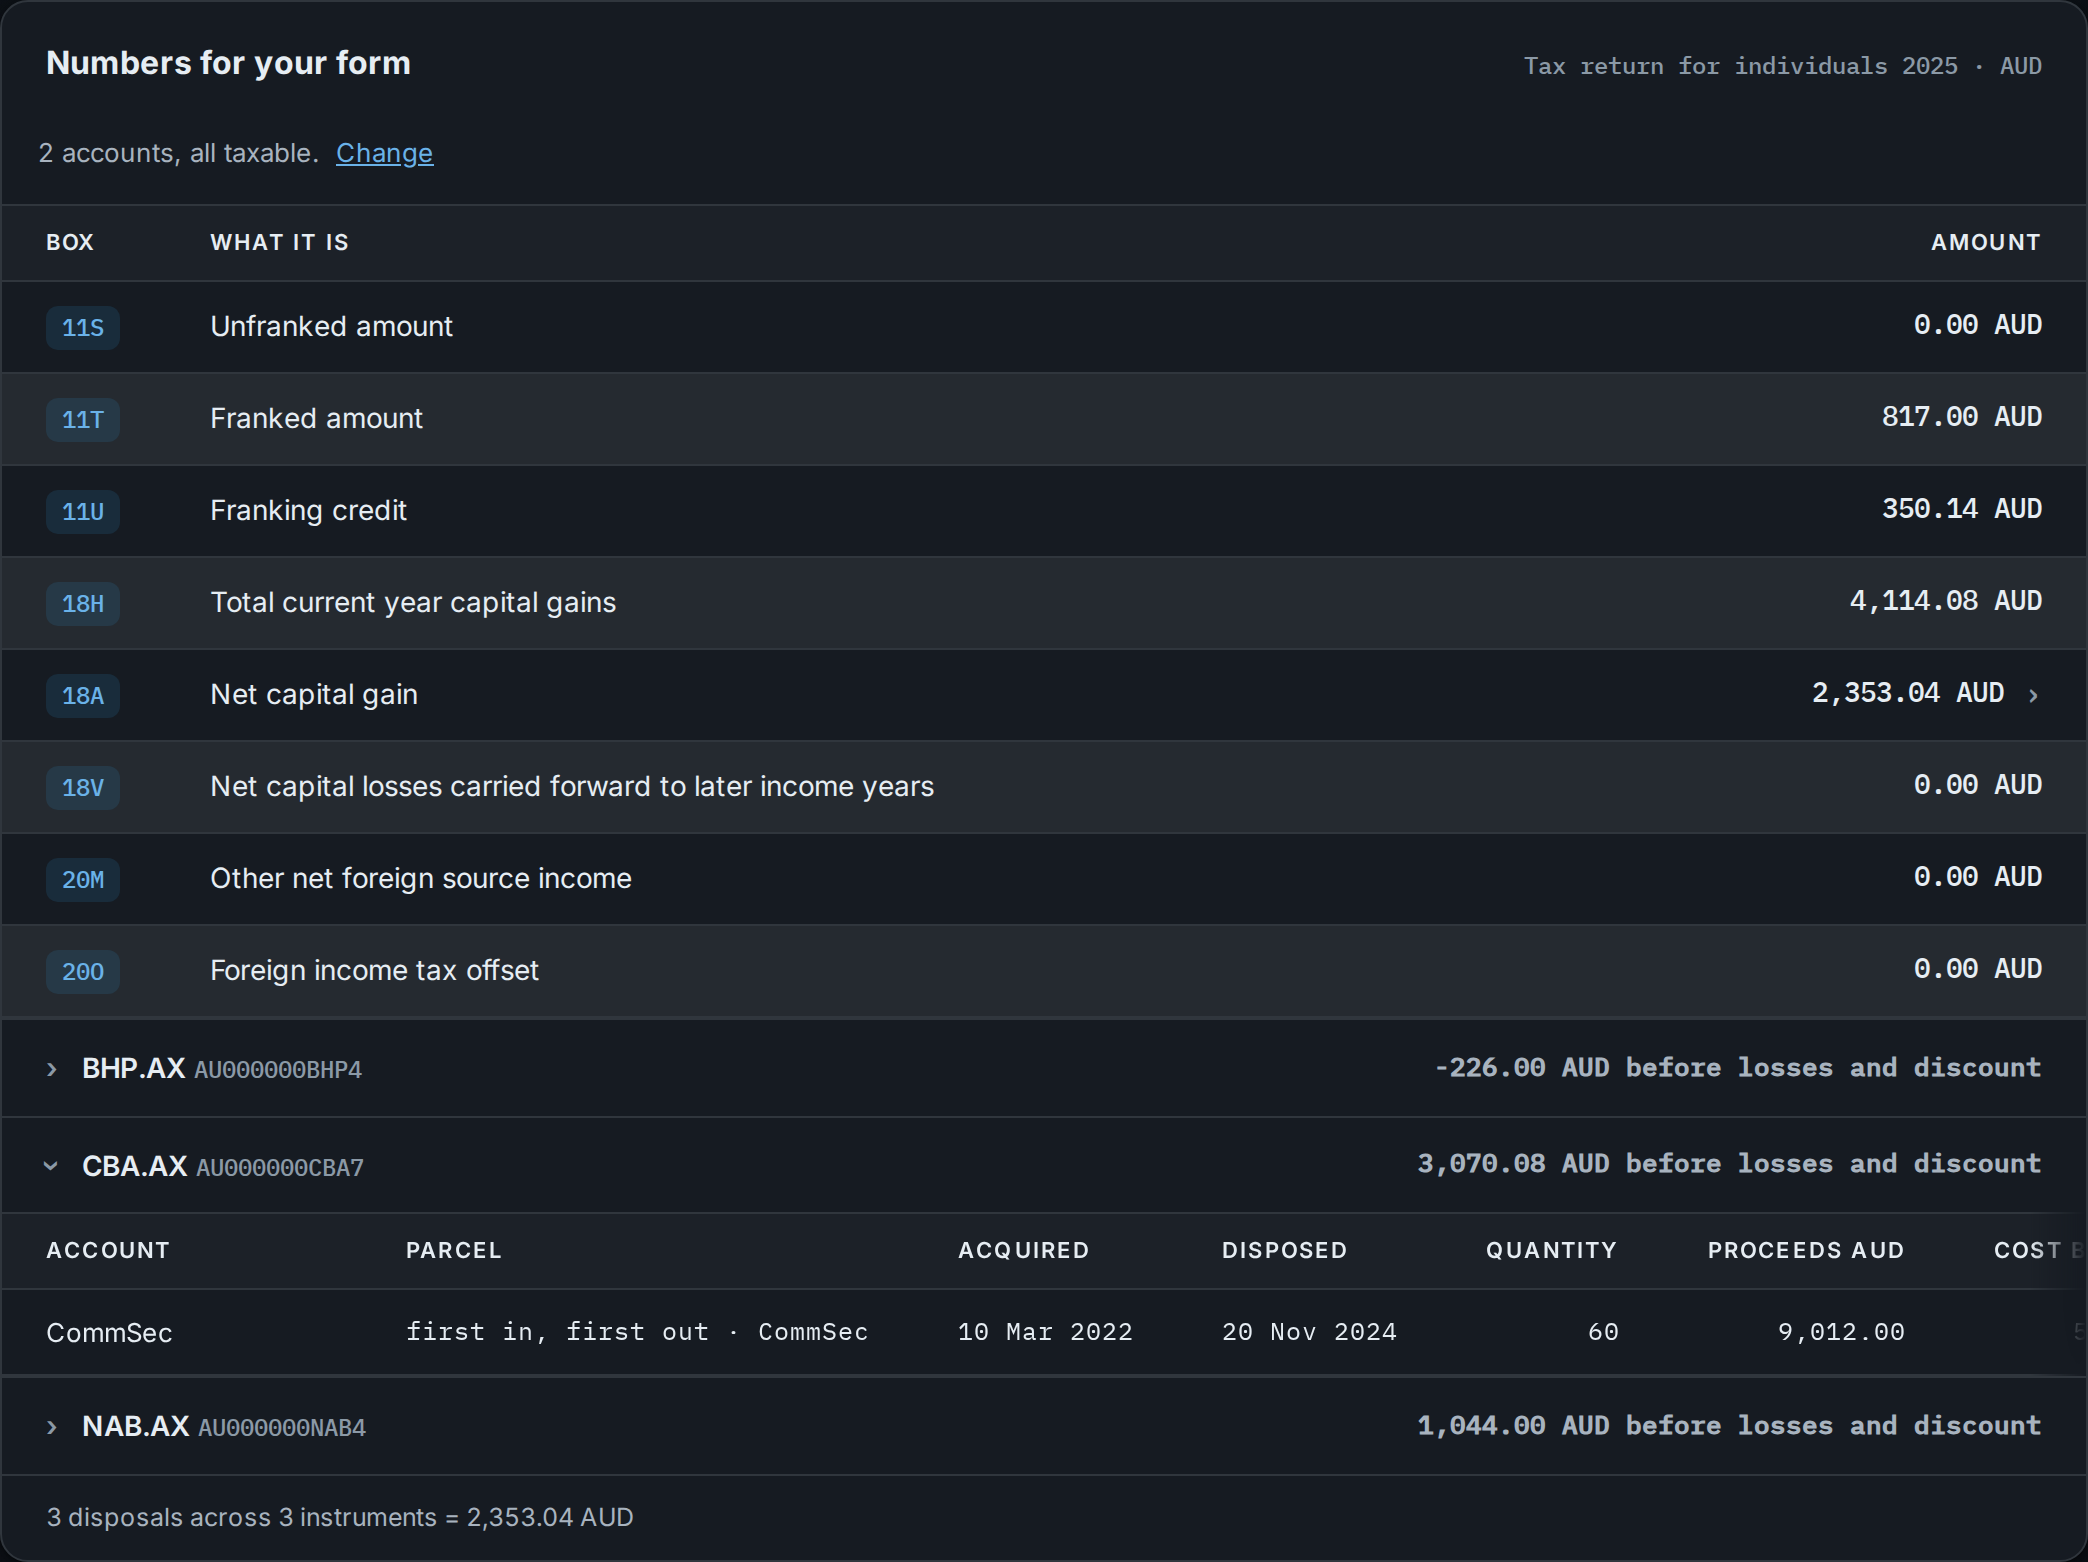
Australian filing pack showing items 11S, 11T and 11U, 18H, 18A and 18V, 20M and 20O in AUD, with a CommSec parcel sold under first in, first out Australian filing pack showing items 11S, 11T and 11U, 18H, 18A and 18V, 20M and 20O in AUD, with a CommSec parcel sold under first in, first out
817.00 AUD of franked company dividends with 350.14 AUD of franking credits, and a 2,353.04 AUD net capital gain after a loss and the discount. Fixture filer, invented figures.View full sizeView full size

Keep going

Sources: ATO, resident tax rates, company tax rates and refund of franking credits. Rates are for Australian residents in the income year you pick. The calculator treats the dividend as the only income at your rate. Other tax you owe, or offsets you hold, change how much of the credit comes back in cash. This is an estimate, not tax advice.