Free dollar cost averaging calculator

DCA Calculator: Dollar Cost Averaging With Real Prices

Dollar cost averaging means investing the same amount on a schedule, whatever the price. $500 at the start of every month into an S&P 500 fund over the last 20 years was 240 buys and $120,000 in. With dividends reinvested it was worth $564,527 on 16 October 2026, a return of 13.7% a year on the money as it went in.

Real weekly prices back to 1993 Dividends reinvested Compared with a lump sum

Your plan

How often
From
To
Worth on 16 Oct 2026
$564,527
from $120,000 put in over 240 buys
Gain+$444,527+370.4% on what you put in
Yearly return13.7%Money-weighted, each buy from its own date
Average cost$203.58a share, against an average price of $283.91
Worst moment-43.8%on 6 Mar 2009, against the money in so far
The whole amount on day oneInvesting the $120,000 in one go in November 2006 would be worth $967,461.

Value against money put in

Weekly, from the first buy to the last close.

  • Your plan
  • Money put in
  • Lump sum on day one
Year by year
YearPut inTotal inValue at year endGain

How dollar cost averaging works

The same $500 buys more shares when the price is low and fewer when it's high. Six months of an ETF whose price moves around:

$500 a month for 6 months

Shares bought each month

5.00Jan, $100
5.56Feb, $90
6.67Mar, $75
6.25Apr, $80
5.26May, $95
4.55Jun, $110
Put in$3,000
Shares33.28
Average cost$90.14
Worth at $110$3,660.89
Average cost

Why your average cost sits below the average price

Average cost = money put in / shares bought
$3,000 / 33.28 = $90.14 a share

The six prices average $91.67, but you paid $90.14 a share, because March and April's low prices bought the most shares. With a fixed amount and no fees, your average cost always comes out at or below the average price.

That doesn't mean DCA beats investing at once. It means you never bought the most shares at the top. Over long rising stretches the gap gets big: the 20-year S&P 500 plan above paid $203.58 a share on average while the price averaged $283.91.

DCA vs lump sum: 394 one-year tests in the S&P 500

Every month since January 1993, $12,000 either went in at once or as $1,000 at the start of each of the next 12 months. Both were valued a year after the start, with dividends reinvested and the waiting cash earning nothing.

Lump sum ahead311 of 39479% of the windows, by 9.1% of the $12,000 on average
DCA ahead83 of 39421%, by 7.2% on average; 46 of them started in 2000 to 2002 or 2007 to 2008
Widest gaps+43.9% / +30.3%Lump sum from March 2009; DCA from September 2008
  • Lump sum ended ahead
  • DCA ended ahead

Vanguard's 2023 study tested a shorter split, a lump sum against three monthly buys, in global stocks from 1976 to 2022. The lump sum came out ahead 68% of the time, with similar results in the US, UK, Canada, Europe and Australia. The market rises more often than it falls, so money that waits usually misses some of the rise.

Where DCA earns its keep: starting just before a fall

The lump sum's bad years are the ones that begin just before a fall. Two of the worst starts, with the same total either bought in one go or spread month by month.

S&P 500 from October 2007

$500 a month vs $114,500 in October 2007

Worst, DCA
-39.8%
Worst, lump
-54.5%

Both hit bottom in March 2009. The monthly plan was back above the money put in by September 2009; the lump sum only got back to even in August 2012. By 16 October 2026 the plan was worth $522,978 and the lump sum $793,902, because the lump sum still had more years in the market.

Nasdaq-100 from March 2000

$500 a month vs $160,000 in March 2000

Worth now, DCA
$1,905,547
Worth now, lump
$1,214,685

The lump sum fell 81.7% by October 2002 and stayed below $160,000 until November 2014. The monthly plan bought through the whole fall, and its 320 buys made 15.5% a year against the lump sum's 7.9%.

Daily, weekly or monthly: how often to buy

The same $120,000 spread evenly over each period, bought at the close, with dividends reinvested.

PlanEvery trading dayWeeklyMonthlyQuarterly
S&P 500, 20 yearsNov 2006 to Oct 2026$563,998$564,674$564,470$560,349
S&P 500, 10 yearsNov 2016 to Oct 2026$269,123$269,577$270,225$269,323
BitcoinJan 2020 to Oct 2026$339,149$342,734$340,599$373,146

In the S&P 500, daily, weekly and monthly buying ended within 0.2% of each other over 20 years. In bitcoin the quarterly plan won by about 10%, and that's luck: its 28 buy dates happened to miss some of the highs. Buy when your pay arrives. What does matter is cost: a $1 fee on a $50 weekly buy is 2% of every purchase, so put the fee in the calculator if your broker charges one.

For the plan you're running

Every recurring buy, with your real average cost and return

Sync a supported broker and each automatic buy lands in AllInvestView by itself, or import the history from a file. Each holding shows the shares you own, your average cost and its return, and every buy stays on record as its own lot for tax time. Stocks, ETFs, crypto, bonds and options from every broker sit in one portfolio.

See your portfolio
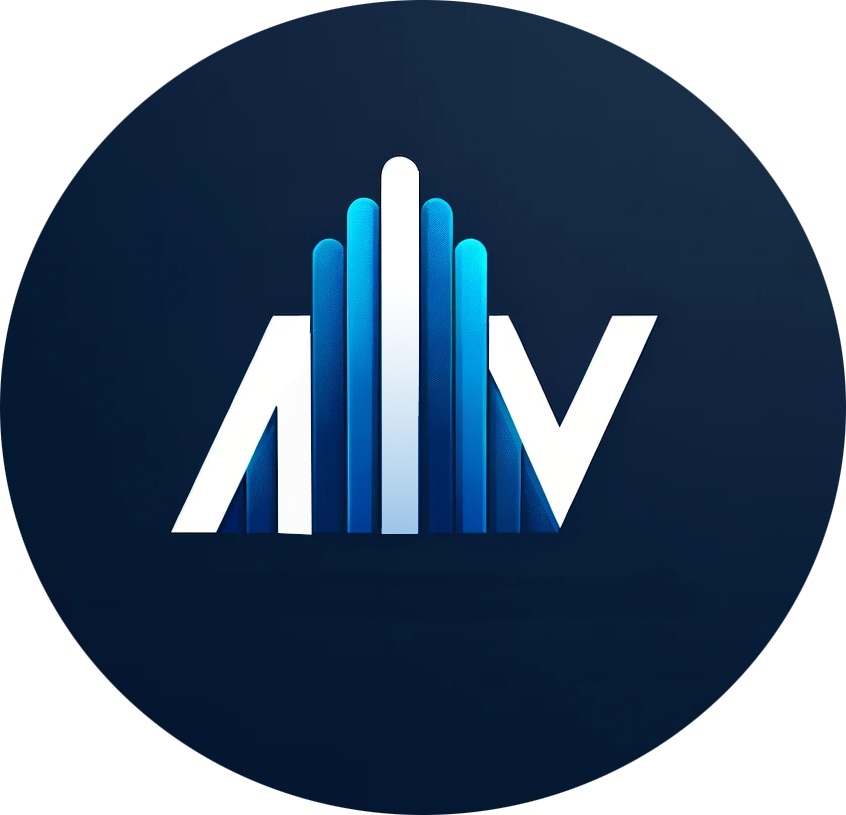
AllInvestView AllInvestView holding page for the Vanguard S&P 500 ETF built from 32 monthly buys of $500: 29.06 shares at an average cost of 550.66 USD, cost basis 16,000.00 USD, value 20,406.12 USD, total return 27.54%, XIRR 16.84%, and the first six of 32 tax lots, each a $500 buy with its own price and gain AllInvestView holding page for the Vanguard S&P 500 ETF built from 32 monthly buys of $500: 29.06 shares at an average cost of 550.66 USD, cost basis 16,000.00 USD, value 20,406.12 USD, total return 27.54%, XIRR 16.84%, and the first six of 32 tax lots, each a $500 buy with its own price and gain
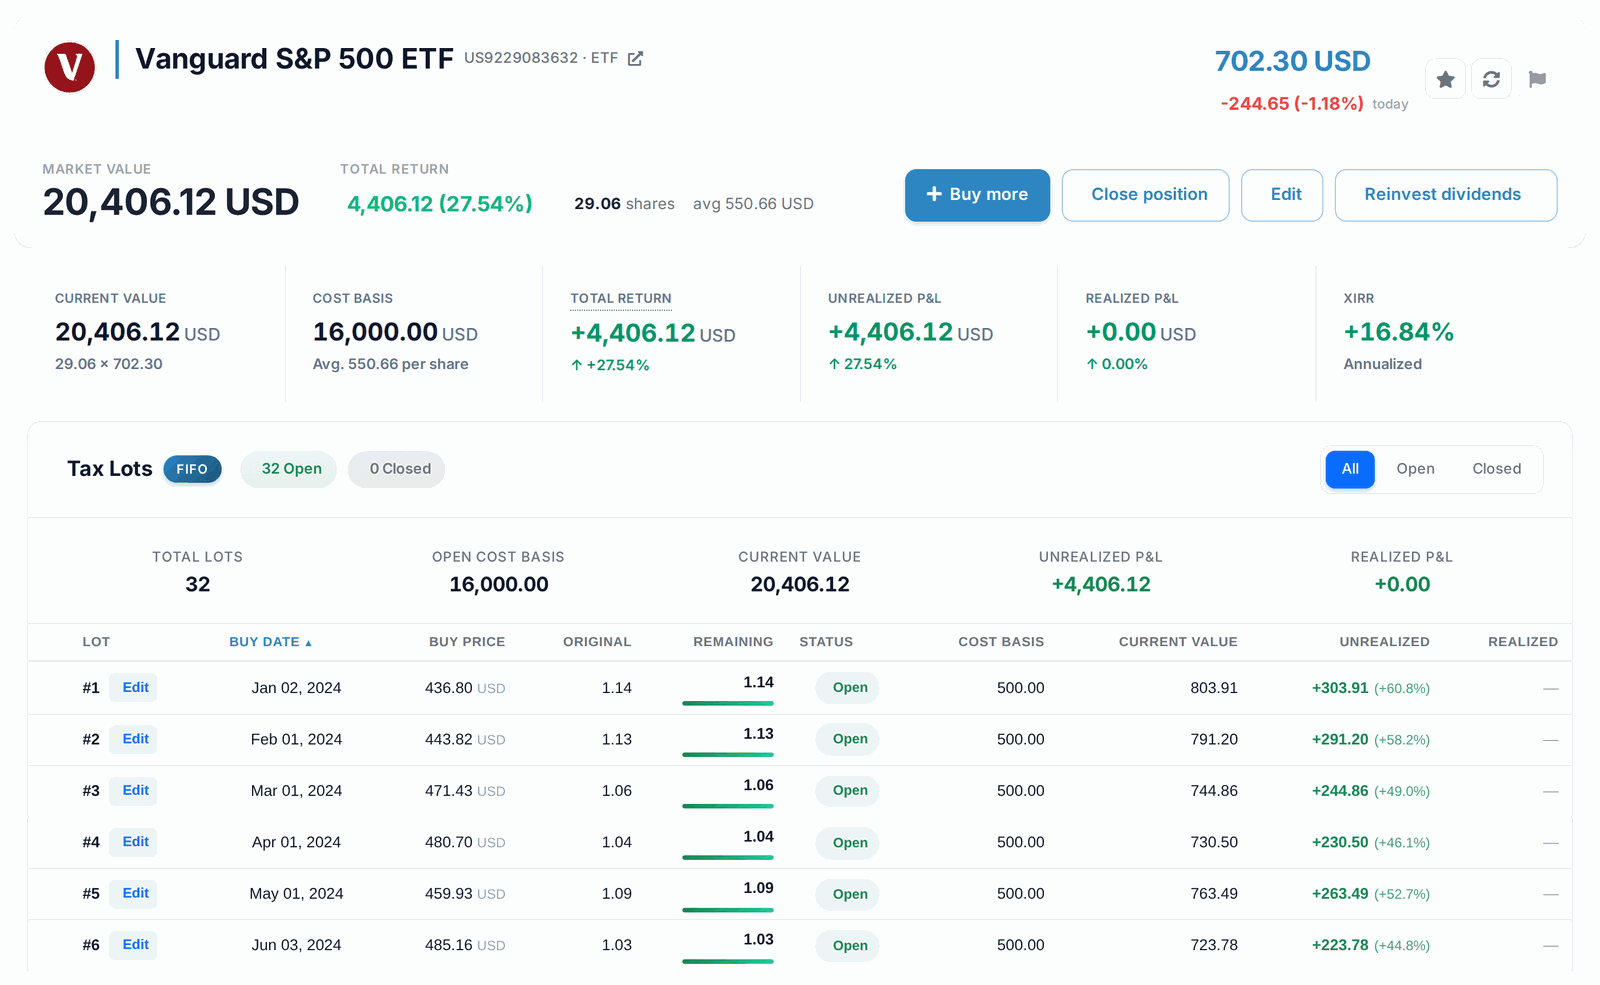
One VOO holding built from 32 monthly $500 buys since January 2024: 29.06 shares at an average 550.66 USD, 16.84% a year on the money as it went in, and each buy kept as its own lot. Demo portfolio; the header, summary and tax lots of the same page stacked into one image.View full-size View full-size
Tracking your own DCA

See what your plan has really made

This calculator runs one asset on paper. AllInvestView follows the buys you actually made, across all your accounts, and tells you what each holding has returned on the money you put in.

Every buy kept as its own lot Average cost and money-weighted return Free for up to 10 holdings

Dollar cost averaging questions

Is dollar cost averaging better than investing a lump sum?

Usually not, if you already have the money. In the S&P 500 since 1993, putting $12,000 in at once beat spreading it over 12 months in 311 of 394 one-year windows, 79% of the time, because the market rose more often than it fell while the cash waited. Vanguard's 2023 study found the same pattern in global stocks, with a lump sum ahead about two times in three. More than half of DCA's wins started in 2000 to 2002 or 2007 to 2008, just before or during a fall. And if the money arrives with each paycheck, DCA is simply how you invest.

How often should you dollar cost average?

As often as the money comes in. $120,000 spread over the 20 years to October 2026 in an S&P 500 fund ended at $563,998 bought every trading day, $564,674 every week and $564,470 every month, less than 0.2% apart. Fees matter more than frequency: a $1 fee on a $50 weekly buy takes 2% of every purchase.

Should I stop buying when the market crashes?

Keep going if you can. $500 a month into the S&P 500 from October 2007, days before the peak, was 39.8% down at the March 2009 low, and back above the money put in by September 2009, because the buys near the bottom bought the most shares. The whole amount invested that October in one go took until August 2012 to get back to even.

What return does a DCA calculator show?

Two numbers worth keeping apart. Total gain compares what you have with what you put in, and ignores that the last buys only had weeks to grow. The yearly return here is money-weighted (an IRR): each buy counts from its own date, so you can compare a DCA plan with a lump sum or a savings rate. The 20-year S&P 500 example made 13.7% a year that way.

Does dollar cost averaging work for bitcoin?

It spreads your buys over bitcoin's swings, which is what most people want from it. $100 a week from January 2020 was 355 buys and $35,500 in, worth $100,331 on 16 October 2026, or 30.6% a year. The same $35,500 bought in the first week of 2020 would be worth $393,918, because bitcoin rose so far after that.

Is every DCA buy a taxable event?

No. A buy doesn't create a capital gain, though buying UK company shares usually costs 0.5% stamp duty. Each buy becomes its own tax lot with its own cost and date, and the gain or loss comes when you sell. Which lots count as sold depends on where you live: the US uses first in, first out unless you name the lots; the UK matches a sale with buys on the same day, then buys in the next 30 days, then the average cost of everything else; Canada uses an adjusted cost base. Dividends are usually taxed in the year they're paid, reinvested or not. AllInvestView keeps every buy as a lot and its tax report works out the gain under your country's rules.

Sources and how the calculator works

Prices are the funds' and bitcoin's closing prices in US dollars, one per week (the last close of each week), from the first week of each price history to 16 October 2026. Weekly plans buy every week, every-2-weeks plans every other week, monthly plans in the first week of each month and quarterly plans in the first week of January, April, July and October. Dividends are reinvested at the close of the week they go ex-dividend, before tax. Share counts allow for later splits. The fund prices include each fund's own fees. The how-often table and the 394 lump sum tests use daily closes: daily plans buy every trading day, weekly ones on the first trading day of each Saturday-to-Friday week, monthly ones on the first trading day of each month. Checked on 22 October 2026; past returns don't tell you future ones.