Price to earnings (P/E)
price ÷ earnings per share
How many years of today's profit you pay for. Misleads when earnings are about to fall or include one-off gains. See the P/E ratio.
 Meta8.5
 Walgreens7.1
Value investing means estimating what a company is worth from its earnings, assets and cash, and buying only when the share price is well below that. The gap is your margin of safety. Cheap on paper isn't enough, though: on 3 November 2022 Meta and Walgreens both traded at under 9 times earnings. One rose about seven-fold; the other was taken private for less than a third of that day's price.
Walgreens looked cheaper on earnings and book value. The difference was the business: Meta's profits more than doubled by 2024, while Walgreens' turned into losses. Value investing is about finding that difference before the price does.
Enter a stock's price and its per-share figures from the latest annual or last-12-month results. You get a discounted cash flow value, the Graham number, the usual ratios and your margin of safety. Start with one of the two examples.
| Rate \ after |
|---|
The cash flow value grows today's free cash flow per share for five years, adds a terminal value for the years after, and discounts both back at your rate, the same method as the DCF on our stock pages. It's an estimate built on your assumptions: change the growth or the rate by a point and the value moves a lot, which is why value investors insist on a wide gap. Meta's figures are from its third-quarter 2022 report, Walgreens' from its fiscal 2022 annual report.
Each ratio compares the price with one thing the business produces or owns. None works alone; together they show whether a low price is a bargain or a warning. Here they are on the two stocks from November 2022.
price ÷ earnings per share
How many years of today's profit you pay for. Misleads when earnings are about to fall or include one-off gains. See the P/E ratio.
Meta8.5Walgreens7.1price ÷ book value per share
The price against the net assets on the balance sheet. Says little about brands, software and goodwill-heavy companies. See price to book.
Meta1.9Walgreens1.2free cash flow per share ÷ price
The cash the business actually generated, as a yield on the price. The hardest to flatter, and where the two stocks split apart.
Meta11.0%Walgreens7.0%yearly dividend ÷ price
Cash paid to you while you wait. A very high yield often means the market expects a cut. See dividend yield.
MetaNoneWalgreens5.4%√(22.5 × EPS × book value per share)
A modern shortcut from Graham's limits of 15 times earnings and 1.5 times book; he applied the 15 to average earnings of the last three years. Ignores growth, debt and cash.
Meta$105Walgreens$57free cash flow ÷ earnings
If reported profit runs well ahead of the cash coming in, find out why before trusting the P/E. Walgreens' cash covered half its earnings.
Meta93%Walgreens50%Per-share figures: Meta, the four quarters to 30 September 2022 (diluted earnings $10.49, free cash flow $26.3 billion over 2,687 million diluted shares, equity $124.1 billion on 30 September over 2,652 million shares outstanding); Walgreens, the fiscal year to 31 August 2022 (diluted earnings $5.01, free cash flow $2.2 billion, equity $25.3 billion over 865 million shares, dividend $0.48 a quarter). Prices are the closes on 3 November 2022.
Intrinsic value is what the business is worth to an owner: the cash it will hand over in the future, discounted to today. You can only estimate it, so value investors buy well below their estimate and leave room to be wrong.
"Confronted with a like challenge to distill the secret of sound investment into three words, we venture the motto, MARGIN OF SAFETY."Benjamin Graham, The Intelligent Investor, chapter 20
Benjamin Graham set out the method in Security Analysis (1934) and The Intelligent Investor (1949). His tests for a defensive investor buying individual stocks, from the 1973 edition:
Graham's picture of the stock market as a moody business partner who offers every day to buy your share or sell you his, at prices that swing with his mood. You don't have to trade with him. His bad days are when a value investor buys, as plenty did with Meta in late 2022.
"It's far better to buy a wonderful company at a fair price than a fair company at a wonderful price."Warren Buffett, Berkshire Hathaway letter to shareholders, 1989
Buffett started with Graham's very cheap, ordinary businesses and, with Charlie Munger, moved towards durable businesses bought at sensible prices and held for years. Both are value investing: paying less than the business is worth.
A value trap looks cheap because its past figures are good, while the business behind them is getting worse. Walgreens from November 2022 is a clear case: at $35.74, $10,000 bought about 280 shares.
P/E 7.1, a 5.4% dividend and the price 38% below its Graham number.
The quarter to November closed at a loss of $4.31 a share, mostly opioid litigation charges.
The quarterly dividend fell from $0.48 to $0.25. Fiscal 2024 ended with a loss of $10.01 a share.
The company stopped paying a dividend to keep cash for its turnaround.
Sycamore Partners paid $11.45 a share in cash, plus a right to up to $3 more from the sale of VillageMD.
Cheap stocks as a group have had a long, hard stretch. Each bar is how far Vanguard's Value ETF (VTV) finished ahead of, or behind, its Growth ETF (VUG) in a calendar year, dividends reinvested. For which style suits you, see growth vs value investing.
A value index fund holds the stocks that score cheapest on a set of ratios; VTV follows the CRSP US Large Cap Value Index. So it owns mostly big companies at lower multiples, not deep bargains, and it doesn't judge whether a business is getting better or worse. Picking your own stocks is where the business analysis above comes in, along with the risk of being wrong on a few names. Many investors hold a value fund as the core and a handful of researched picks around it.
Total returns from adjusted closing prices; 26 October 2026 is the last close used. Past returns don't tell you what either style will do next.
Four steps, from finding a candidate to knowing when you were wrong.
Start from stocks with low P/E or P/B ratios, such as our lowest P/E stocks, or from companies you know whose price has fallen hard.
Ten years of earnings, debt against assets, and free cash flow against profit. Ask why it's cheap and whether that reason will last. If you can't explain it, skip it.
Estimate a value with the calculator or the DCF on the stock's page, then decide your buy price with a margin of safety, say 25% to 40% below.
Write down why you bought. Re-check the case with each annual report; sell when the price passes your value or the reason no longer holds.
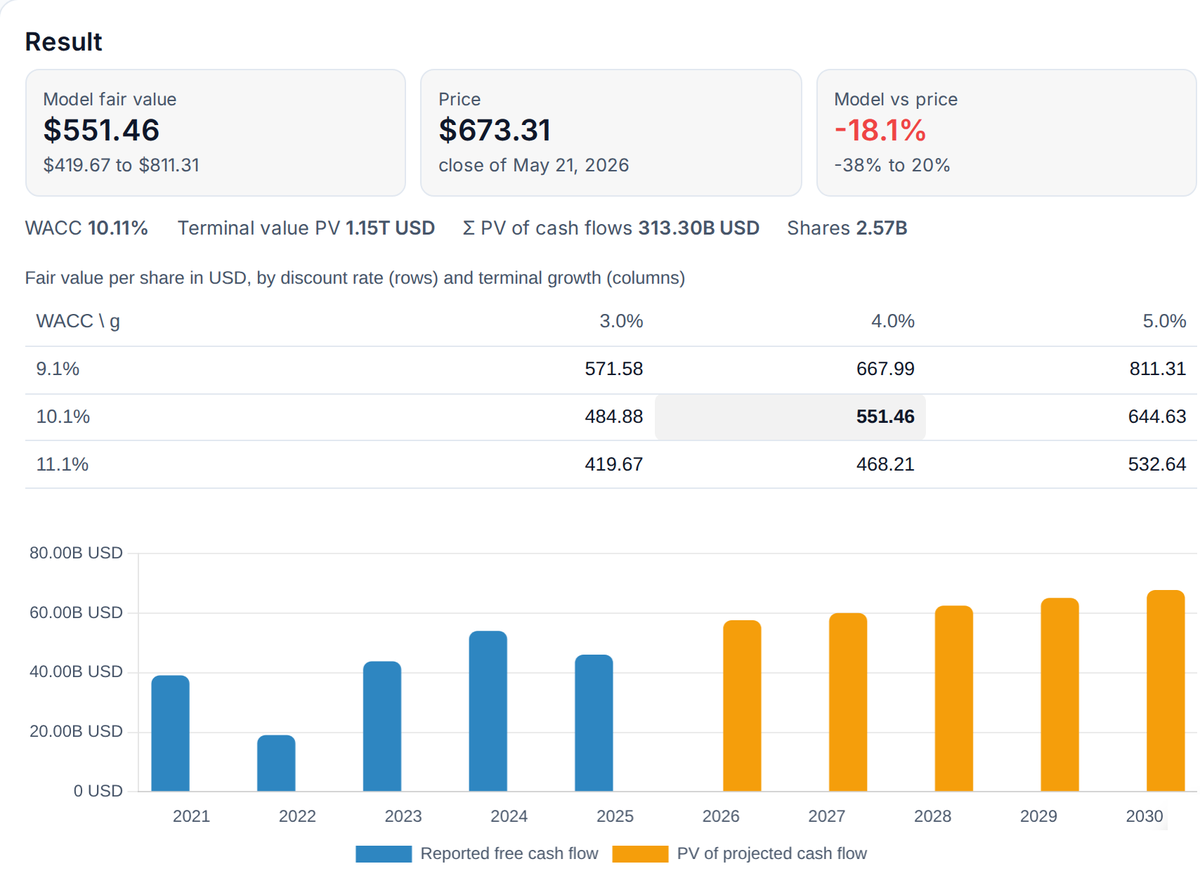
AllInvestView's stock pages show the price with P/E, forward P/E, book value and price to book. Signed in, you can run a DCF on the stock and change its growth, capital spending, tax, terminal growth and cost of capital.
Once you buy, add the holding or link your broker. Your return, dividends and cost basis stay up to date across all your accounts, so you can see whether the price is moving towards your value.
The DCF uses the same method as the calculator above: projected free cash flow and a terminal value, discounted to today.
Buying shares for less than you think the business is worth, and waiting for the price to catch up. You estimate the value from what the company earns, owns and pays out in cash, compare it with the share price, and only buy when there's a clear gap, the margin of safety, to cover the chance you're wrong.
It has gone through long dry spells. Measured by Vanguard's Value and Growth ETFs, growth stocks returned far more from 2005 to 2025, with value ahead in only six of those 21 calendar years. Value held up much better in 2022, when value lost 2.1% and growth lost 33.2%, and it is ahead again in 2026 so far (20.3% against 8.0% to 26 October). Picking individual stocks well is a different question from whether a cheap-stock index beats the market.
There's no single number. Benjamin Graham's test for a defensive investor was no more than 15 times average earnings over the past three years. A low P/E only means the price is low against last year's profit: Walgreens had a P/E of about 7 in November 2022 and its earnings then turned into large losses. Check whether the earnings are steady and backed by cash before trusting the ratio.
The gap between what you think a share is worth and the price you pay. If you value a stock at $100 and buy at $70, your margin of safety is 30%. Graham called it the central idea of sound investing because it leaves room for mistakes in your estimate and for bad luck in the business.
A rough ceiling on what a defensive investor should pay: the square root of 22.5 times earnings per share times book value per share. The 22.5 comes from Graham's limits of 15 times earnings (he used the average of the last three years) and 1.5 times book value; the formula is a later shortcut built from them. It ignores growth, debt and cash flow, so it's a first screen, not a valuation.
A stock that looks cheap on its ratios but keeps falling because the business is getting worse. The earnings behind the low P/E shrink or turn into losses, the dividend is cut, and the price never catches up. Falling sales, rising debt, profits that aren't backed by cash and a high yield the company can't afford are the usual signs.
Yes, though not in Graham's original style. He began by buying very cheap, ordinary businesses, then moved towards buying excellent ones at fair prices, as he put it in Berkshire Hathaway's 1989 letter: "It's far better to buy a wonderful company at a fair price than a fair company at a wonderful price."
Link your brokers or import your trades. AllInvestView keeps each holding's return, dividends and cost basis right across all your accounts and currencies.
Prices are official closing prices on the dates shown. Checked on 27 October 2026. This page explains value investing in general terms and isn't advice to buy or sell any stock.