Portfolio basics · updated October 2026

Asset allocation: what it is and how to choose yours by age

Asset allocation is how you split your money between stocks, bonds and cash. That split decides most of how much your portfolio grows and how far it can fall, more than any single fund you pick. A common starting point is 110 minus your age in stocks and the rest in bonds: 80% stocks at 30, 50% at 60. Then move it down if you'll need the money soon or would sell in a crash.

What four mixes did, 1987 to 2026S&P 500 and total bond market index funds, rebalanced each January
100 / 0all stocks11.2% a year

Worst fall -55.3% from a high

80 / 20stocks / bonds10.2% a year

Worst fall -45.3% from a high

60 / 40stocks / bonds9.0% a year

Worst fall -34.2% from a high

40 / 60stocks / bonds7.8% a year

Worst fall -21.9% from a high

Asset allocation calculator by age

Start from a rule, adjust the stock share to taste, and see what that mix did in the worst stretches since 1987, in dollars on your own amount.

Your starting point

Rule

The slider starts at your rule's answer, to the nearest 5%. Move it to try another split.

Your mix80 / 20
stocks / bonds
In stocks$80,000
In bonds$20,000

What 80/20 did from 1987 to 2026

A year, on average10.2%$10,000 became $473,284
Worst fall from a high-$45,300-45.3% of your amount
Worst calendar year-28.7%2008
Worst 10 years-1.4%a year, over the worst ten-year stretch

Splits between the tested ones use the nearest mix in steps of 10.

What every stock and bond mix did, 1987 to 2026

$10,000 at the end of 1986 in an S&P 500 index fund and a total bond market index fund, split each way and put back to its target every January, to 23 October 2026. More stocks grew more and, past the first 10%, fell further.

Each mix from 1987 to 23 October 2026
Stocks / bondsA year$10,000 becameWorst fallWorst year2022Worst 10 years, a yearLosing years of 39
100 / 011.2%$689,657-55.3%-37.0% (2008)-18.2%-3.5%7
90 / 1010.7%$574,480-50.4%-32.9% (2008)-17.7%-2.4%7
80 / 2010.2%$473,284-45.3%-28.7% (2008)-17.2%-1.4%7
70 / 309.6%$385,722-39.9%-24.6% (2008)-16.7%-0.4%6
60 / 409.0%$311,030-34.2%-20.4% (2008)-16.1%0.6%7
50 / 508.4%$248,172-28.1%-16.2% (2008)-15.6%1.5%6
40 / 607.8%$195,950-21.9%-15.1% (2022)-15.1%2.3%5
30 / 707.1%$153,104-18.5%-14.6% (2022)-14.6%3.2%5
20 / 806.4%$118,375-18.0%-14.2% (2022)-14.2%2.9%4
0 / 1005.0%$68,540-18.8%-13.2% (2022)-13.2%0.6%6

The trade-off

Above 40% in stocks, each 10 more points added about half a point a year and 5 to 6 points to the worst fall. 80/20 made 10.2% a year and fell 45.3%; 60/40 made 9.0% and fell 34.2%.

All bonds isn't the safest

When rates jumped in 2022 the bond fund lost 13.2%. A mix with 20% stocks fell less from its high (-18.0%) than all bonds (-18.8%) and made 6.4% a year instead of 5.0%.

Time changes the risk

All stocks lost 3.5% a year over its worst ten years in a row. 30/70 never made less than 3.2% a year over any ten. Money you need within ten years belongs in the lower rows.

Vanguard 500 Index Fund Investor Shares (VFINX) for stocks and Vanguard Total Bond Market Index Fund Investor Shares (VBMFX) for bonds, after fund costs, before tax, dividends reinvested. Worst fall is the deepest drop from a previous high on daily closes; worst year and losing years count the 39 full years 1987 to 2025. The year-by-year chart for 60/40 is on the 60/40 portfolio page.

Asset allocation by age

The three rules side by side, as the stock share at each age. The rest goes in bonds. They're starting points: the next section covers what should move yours up or down.

Stock share by age under the 100, 110 and 120 minus age rules
Age100 minus age110 minus age120 minus age
2575%85%95%
3565%75%85%
4555%65%75%
5545%55%65%
6535%45%55%
7525%35%45%

How target-date funds do it

A target-date fund follows a glide path: it moves from stocks to bonds on a schedule set by the year you plan to retire. Vanguard's Target Retirement funds, for example:

100%50%0% 90%~50%30% 25406572age, retiring at 65
  • To retirement glide paths stop moving at the retirement year.
  • Through retirement ones keep cutting stocks for some years after, as Vanguard's does.

When you need the money

Age is a stand-in for this. Money for a house in three years shouldn't be 80% stocks at any age; money you won't touch for 25 years can be, even at 50.

The fall you'd sit through

Look at the worst fall in dollars, not percent. At 80/20, $100,000 dropped to about $54,700 from 2007 to 2009. If you would have sold there, pick a lower row: a mix only works if you hold it through the fall.

Your other income

A pension or Social Security works like a bond: steady payments whatever the market does. With a big one you can hold more stocks; with none, lean the other way.

The building blocks: stocks, bonds, cash and the rest

Each part does a different job. The allocation is how much of each job you want done.

Stocks

The growth engine: 11.2% a year in the test above. Also the falls: more than half the value was gone between 2007 and 2009. Split them between your home market and the rest of the world.

Bonds

Interest income and a cushion when stocks fall: the bond fund gained 5.1% in 2008. Longer bonds move more with interest rates, as 2022 showed.

Cash

Savings, money market funds and short Treasury bills. They hardly move in price and barely grow after inflation. Keep what you'll spend in the next year or two here, outside the stock and bond split.

Real estate, gold and the rest

REIT funds, gold and commodities move differently from both. Most people hold none or a small slice, 5% to 10%; a few well-known portfolios hold much more.

Six well-known allocations

Strategic, tactical and dynamic asset allocation

Three ways to run an allocation once you have one. The first is what this page is about, and what most people need.

StrategicA fixed long-term targetTacticalShort bets around the targetDynamicThe target itself moves
How it worksPick a split, such as 70/30, and rebalance back to it.Lean away from the split for months when you expect one asset to do better, then return.Change the split as markets move, often by rules: cut stocks after falls in value, add after gains.
ExampleA three-fund portfolio rebalanced each year.60/40 moved to 50/50 for a year on a view about rates.A trend rule that holds stocks only above their 10-month average.
What it needsA rebalance once a year or at a drift band.Bets that earn more than they cost in trades and taxes.Rules you'll follow and more trades.
Who uses itMost individual investors, target-date funds, pension plans.Fund managers and advisers, around a strategic base.Some funds and rules-based investors.

Asset allocation

How much goes into stocks, bonds and cash. The decision this page is about.

Diversification

Spreading inside each part: many companies instead of five, several countries instead of one. A broad index fund does most of it for you.

Asset location

Which account holds what. Interest from a taxable bond fund is taxed every year, so it often sits in an IRA or 401(k), with stock index funds in the taxable account.

Check the allocation you really hold, across every account

Most people's allocation is spread over a 401(k), an IRA and a brokerage account, and the funds inside them overlap. Your real split is the total of all of them. AllInvestView adds every account together.

Target allocation

Your split against your target, and what to buy to get back

Give each holding a category and set a target for each one, and AllInvestView shows the drift from live prices. Ask for a plan and it lists the buys and sells, with or without selling, for new money or a withdrawal. Combine portfolios from several brokers and one target covers them all.

Read the rebalancing guide

AllInvestView AllInvestView rebalancing page for a four-ETF demo portfolio. Allocation breakdown: US Stocks 68.0% against a 60% target, Bonds 16.0% against 15%, International Stocks 12.0% against 20%, Real Estate 4.0% against 5%. Recommendations: sell US Stocks and Bonds, buy International Stocks and Real Estate, each landing on its target, with the estimated tax on the two sells AllInvestView rebalancing page for a four-ETF demo portfolio. Allocation breakdown: US Stocks 68.0% against a 60% target, Bonds 16.0% against 15%, International Stocks 12.0% against 20%, Real Estate 4.0% against 5%. Recommendations: sell US Stocks and Bonds, buy International Stocks and Real Estate, each landing on its target, with the estimated tax on the two sells
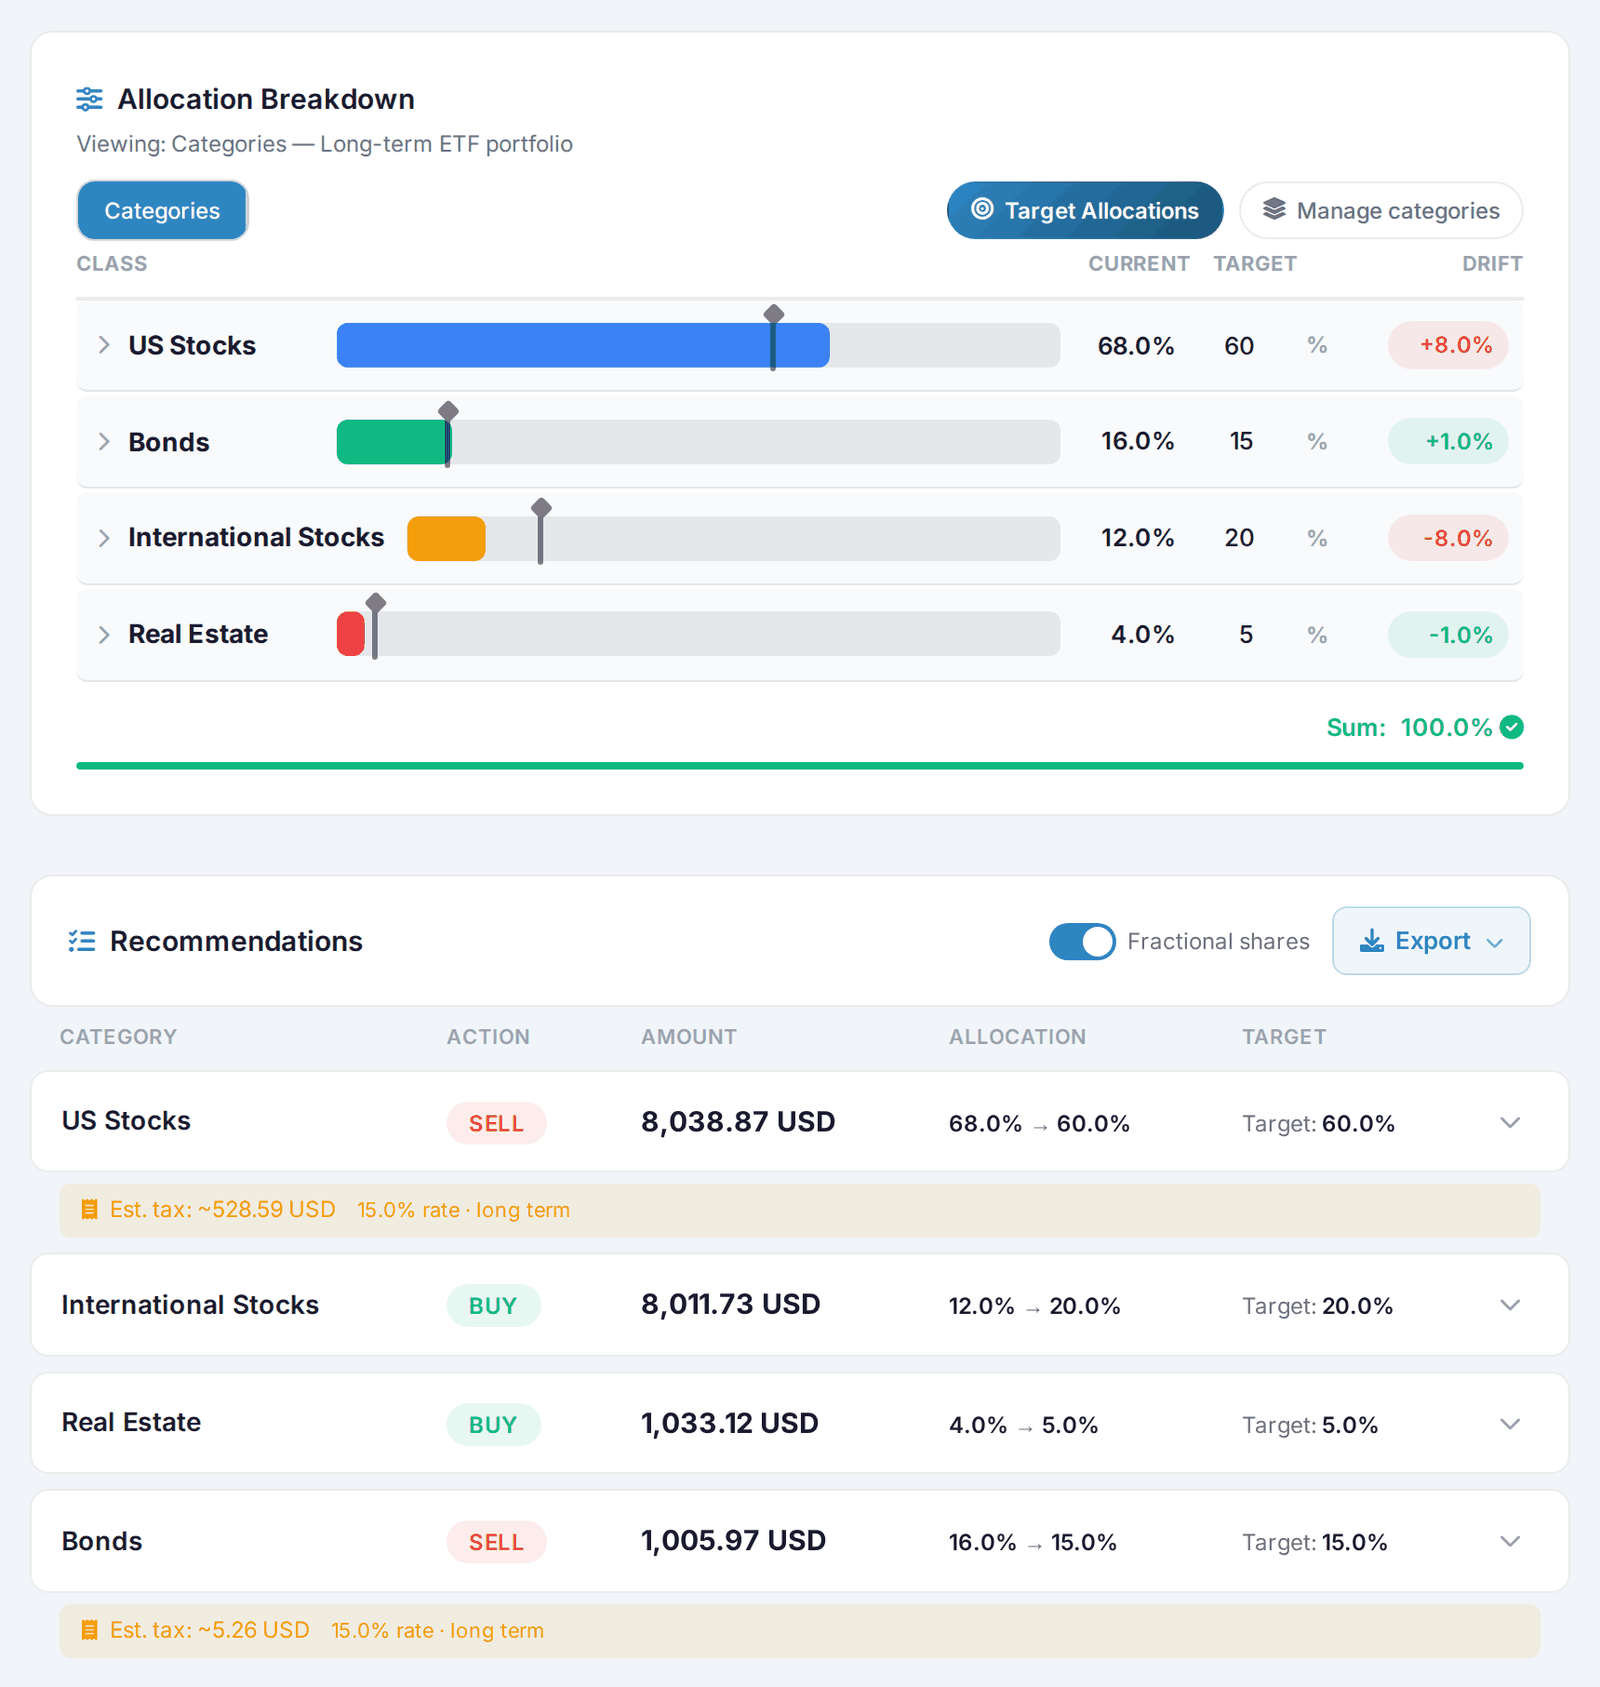
Four ETFs set to 60/15/20/5 that drifted to 68/16/12/4, and the four trades that put each category back on target. Demo portfolio with sample prices; two parts of the same page stacked.View full-size View full-size
Portfolio X-Ray

What your funds hold underneath

Two growth funds and a few shares can add up to one company being a third of your stocks. X-Ray opens each fund and adds its holdings to the shares you own directly, so concentration shows before it hurts. X-Ray is on the Starter plan and up.

Compare two ETFs' holdings for free
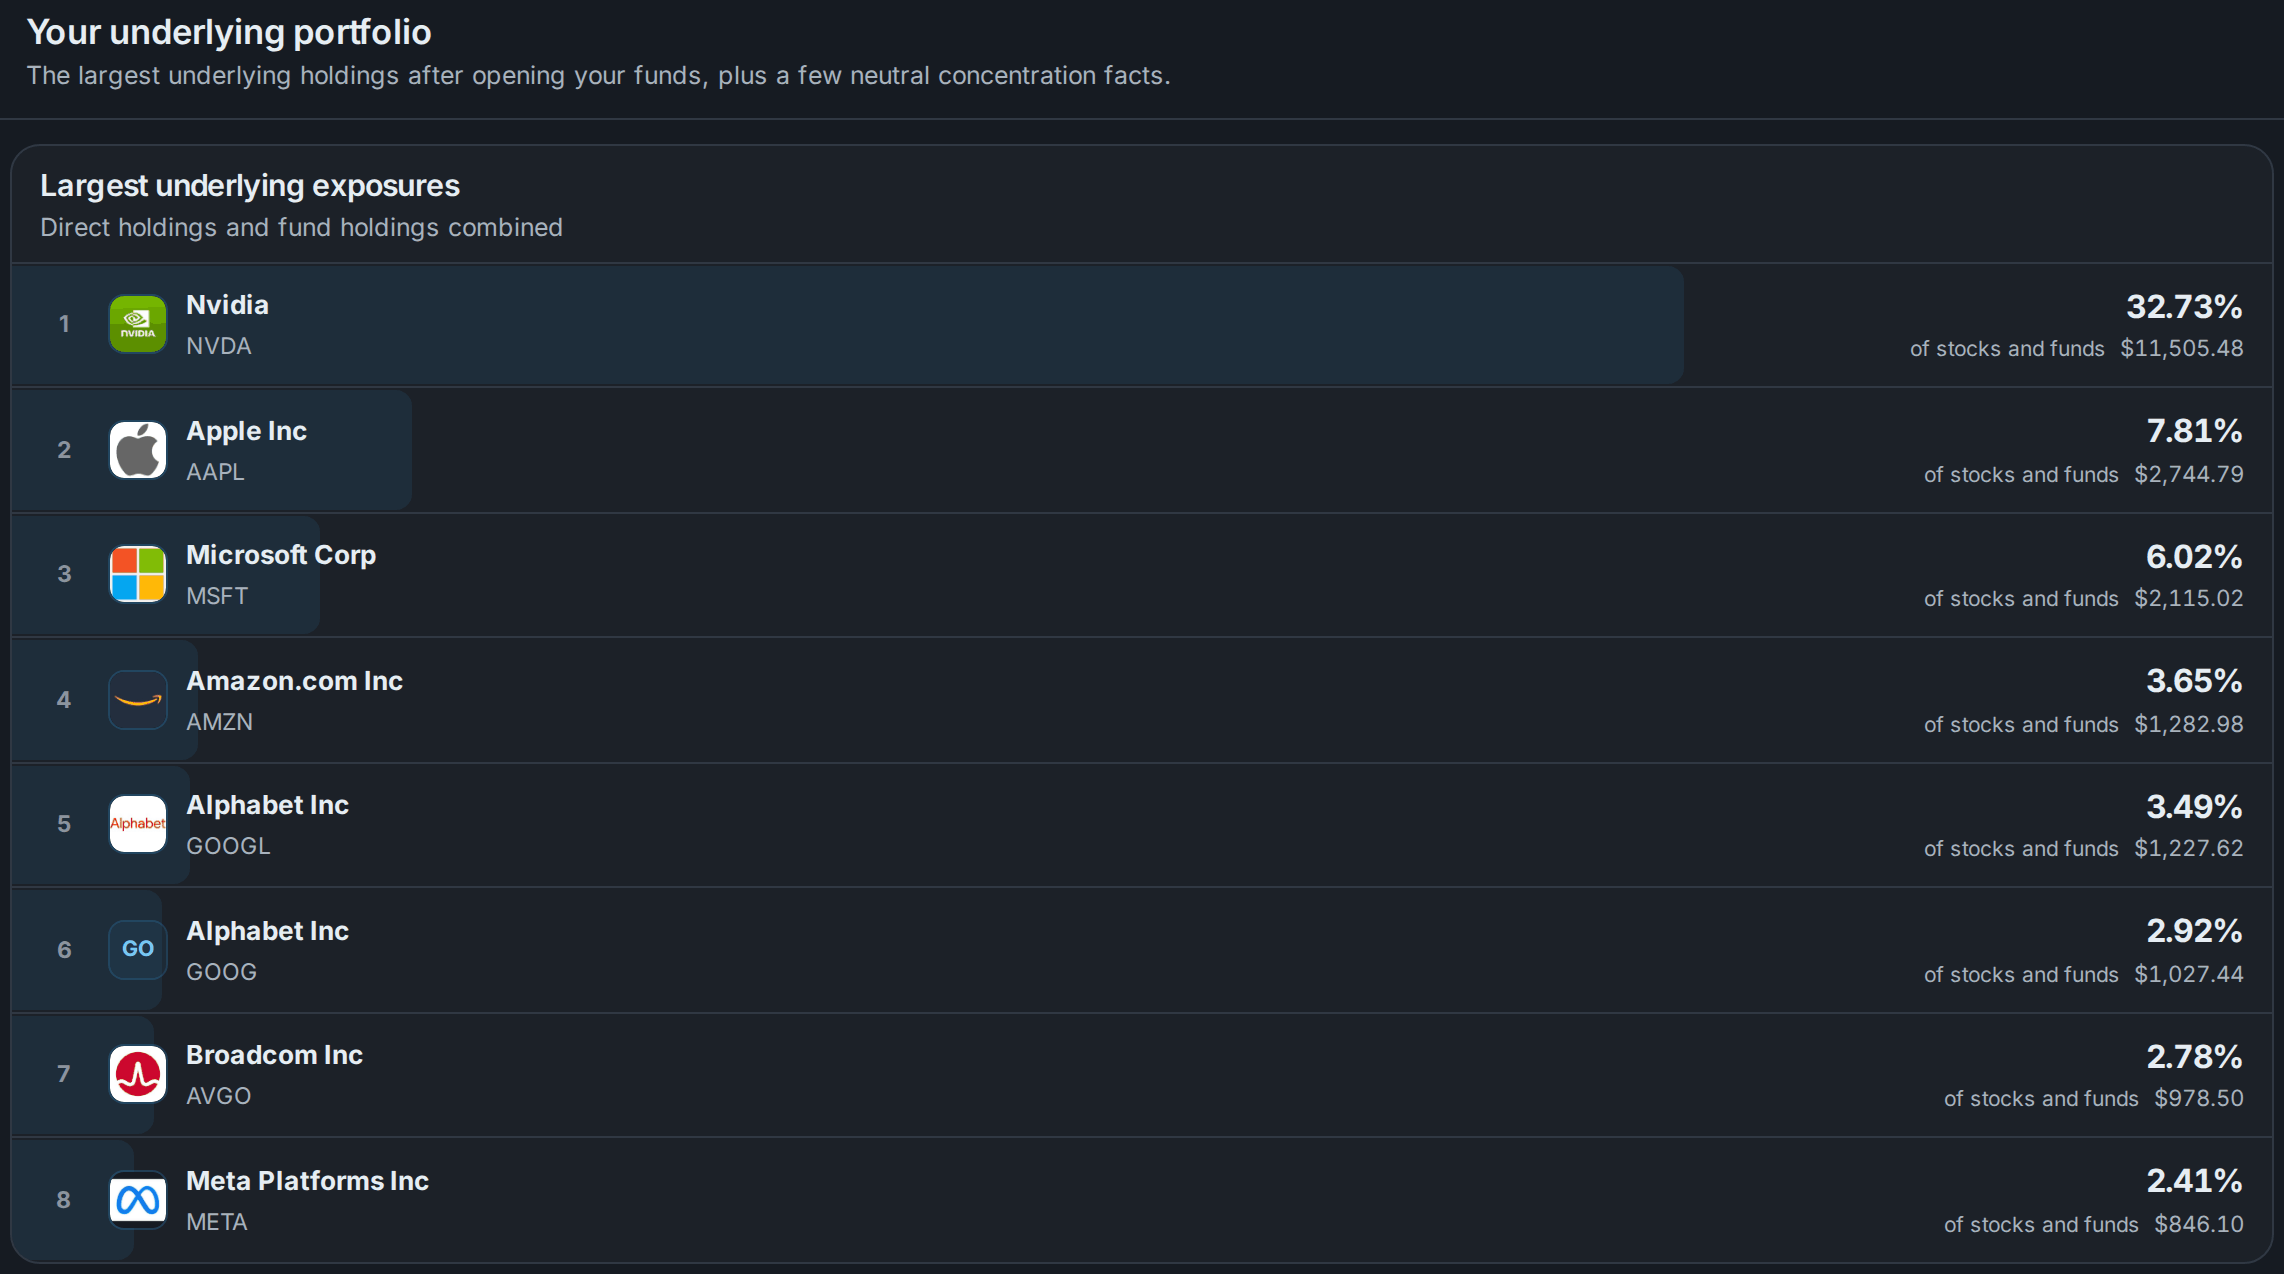
AllInvestView AllInvestView Portfolio X-Ray for a demo portfolio of VUG, QQQM and NVIDIA shares: the largest underlying exposures with direct and fund holdings combined, NVIDIA first at 32.73% of stocks and funds, then Apple 7.81%, Microsoft 6.02%, Amazon 3.65%, Alphabet, Broadcom and Meta AllInvestView Portfolio X-Ray for a demo portfolio of VUG, QQQM and NVIDIA shares: the largest underlying exposures with direct and fund holdings combined, NVIDIA first at 32.73% of stocks and funds, then Apple 7.81%, Microsoft 6.02%, Amazon 3.65%, Alphabet, Broadcom and Meta
A demo portfolio of 30 VUG, 40 QQQM and 40 NVIDIA shares: NVIDIA ends up 32.73% of it. Sample prices, not today's.View full-size View full-size

Asset allocation questions

What is asset allocation?

It is how you split your money between stocks, bonds and cash, and sometimes real estate or gold. The split sets most of how much a portfolio grows and how far it can fall, far more than which funds you pick inside each part.

What is a good asset allocation for my age?

A common starting point is 110 minus your age in stocks and the rest in bonds: 80% stocks at 30, 65% at 45, 50% at 60. Move it down if you need the money within a few years or would sell in a crash, and up if you have a pension or other steady income. Target-date funds start around 90% stocks and reach about half at the retirement year.

What is the 110 minus age rule?

Subtract your age from 110 and hold that percentage in stocks. It replaced the older 100 minus age rule because people live longer and need their savings to keep growing in retirement. 120 minus age is the bolder version, for someone with other income or a high tolerance for falls.

How much did a 60/40 portfolio lose in 2008?

20.4% over the calendar year, with an S&P 500 index fund and a total bond market fund rebalanced each January. From its high in 2007 to the low in 2009 it fell 34.2%. 100% stocks lost 37% in the year and 55.3% from the high.

Are bonds always safer than stocks?

Over a year or more, usually, but not always. When rates jumped in 2022 the total bond market fund lost 13.2%, its worst year since 1987, and a portfolio with 20% stocks fell less from its high than one with none: a small stock share made a bond portfolio fall less, not more.

What is the difference between strategic and tactical asset allocation?

Strategic allocation is a long-term target you keep and rebalance back to, such as 70/30. Tactical allocation moves away from it for a while to bet on a view of the market, then comes back. Most individual investors do well with a strategic target alone.

How often should I rebalance my asset allocation?

Once a year, or when one part drifts about 5 percentage points from its target, is enough for most people. Use new money and dividends first so you sell less in a taxable account.

See your real stock and bond split

Link your brokers or import your history, and AllInvestView shows one allocation across every account, how far it has drifted from your target and the trades to fix it.

Create a free account

Related guides and portfolios

Sources

Fund returns from 31 December 1986 to 23 October 2026, with dividends reinvested, rebalanced on the first trading day of each year. Checked on 26 October 2026. Past returns don't promise future ones; this page explains allocation in general terms.