Each sale, line by line
- Rule
- Date, quantity, gross price, selling expenses, unit cost, total acquisition price and the result.
- Box
- Formulaire 2074
- Pack
- Prepared. One row per disposal, labelled in French and English.
Fungible securities are costed at a weighted average across everything you hold, so the 2074 line for one sale depends on purchases made in another account years earlier. The French pack builds that pool, writes the per-disposal detail and fills the 2042 C recap.
What a securities disposal has to show, and how far the pack takes it before you sign.
| Item | The rule | Form and box | What the pack produces |
|---|---|---|---|
| Each sale, line by line | A disposal reports its date, quantity, gross price, selling expenses, unit cost, total acquisition price and the resulting gain or loss. | Formulaire 2074 | Prepared One row per disposal, each column labelled in French and in English. |
| The cost of a fungible security | Fungible titles use the weighted average acquisition price across the taxpayer's holdings, not the cost of a chosen lot. | Behind the 2074 unit cost | Calculated One pool per security across the accounts in scope, with identifiable instruments using their selected actual costs instead. |
| Foreign-currency sales | Amounts convert to euros on the date the transaction settled. | Inside every 2074 amount | Converted The settlement-date euro rate, or the trade date shown openly when settlement is unavailable. |
| Losses | Securities losses stay available for ten years and are applied against later gains of the same nature. | Reduces the 3VG amount | Applied Current and prior losses carried inside the pack's own loss calculation. |
| The annual recap | The year's taxable gain and the year's losses are summarised on the 2042 C. | 2042 C, cases 3VG and 3VH | Prepared Box 3VG for taxable gains and box 3VH for the year's losses. |
| Flat tax or the income-tax option | The PFU applies by default. Ticking 2OP taxes investment income at your household rate instead, for everything at once. | 2042, case 2OP | Compared on request An optional household comparison when you supply the inputs. It is neither a filing figure nor a recommendation. |
| Submitting the return | The 2074 and the 2042 C go with your French income tax return. | 2074 with 2042 C | You file Everything leaves as a file for you or your adviser. |
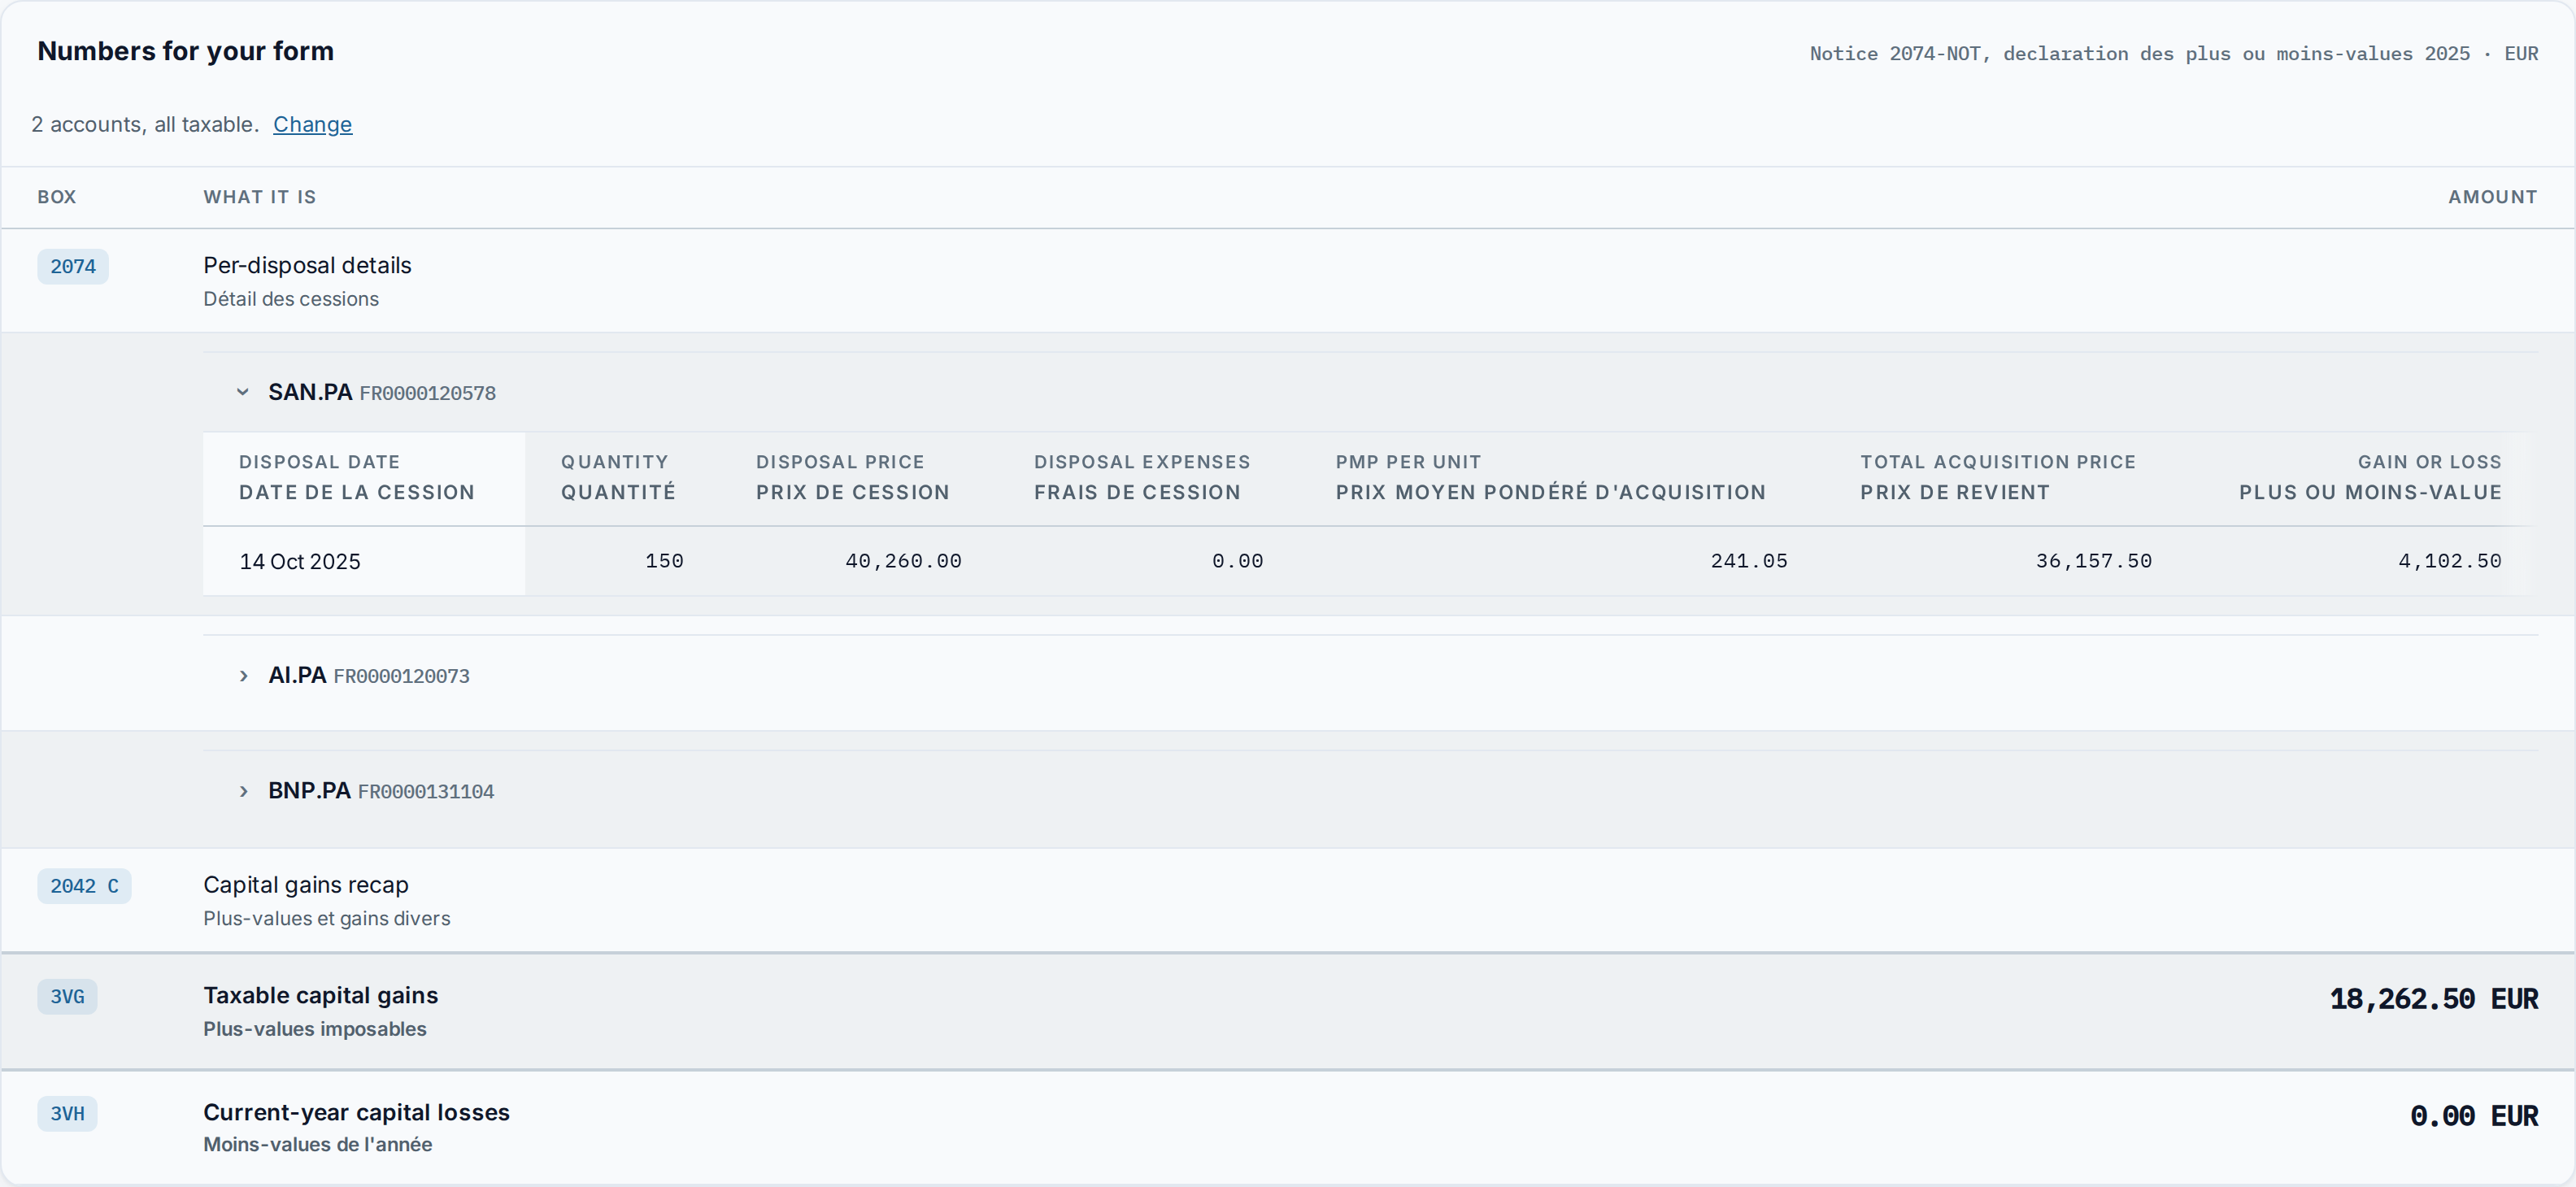
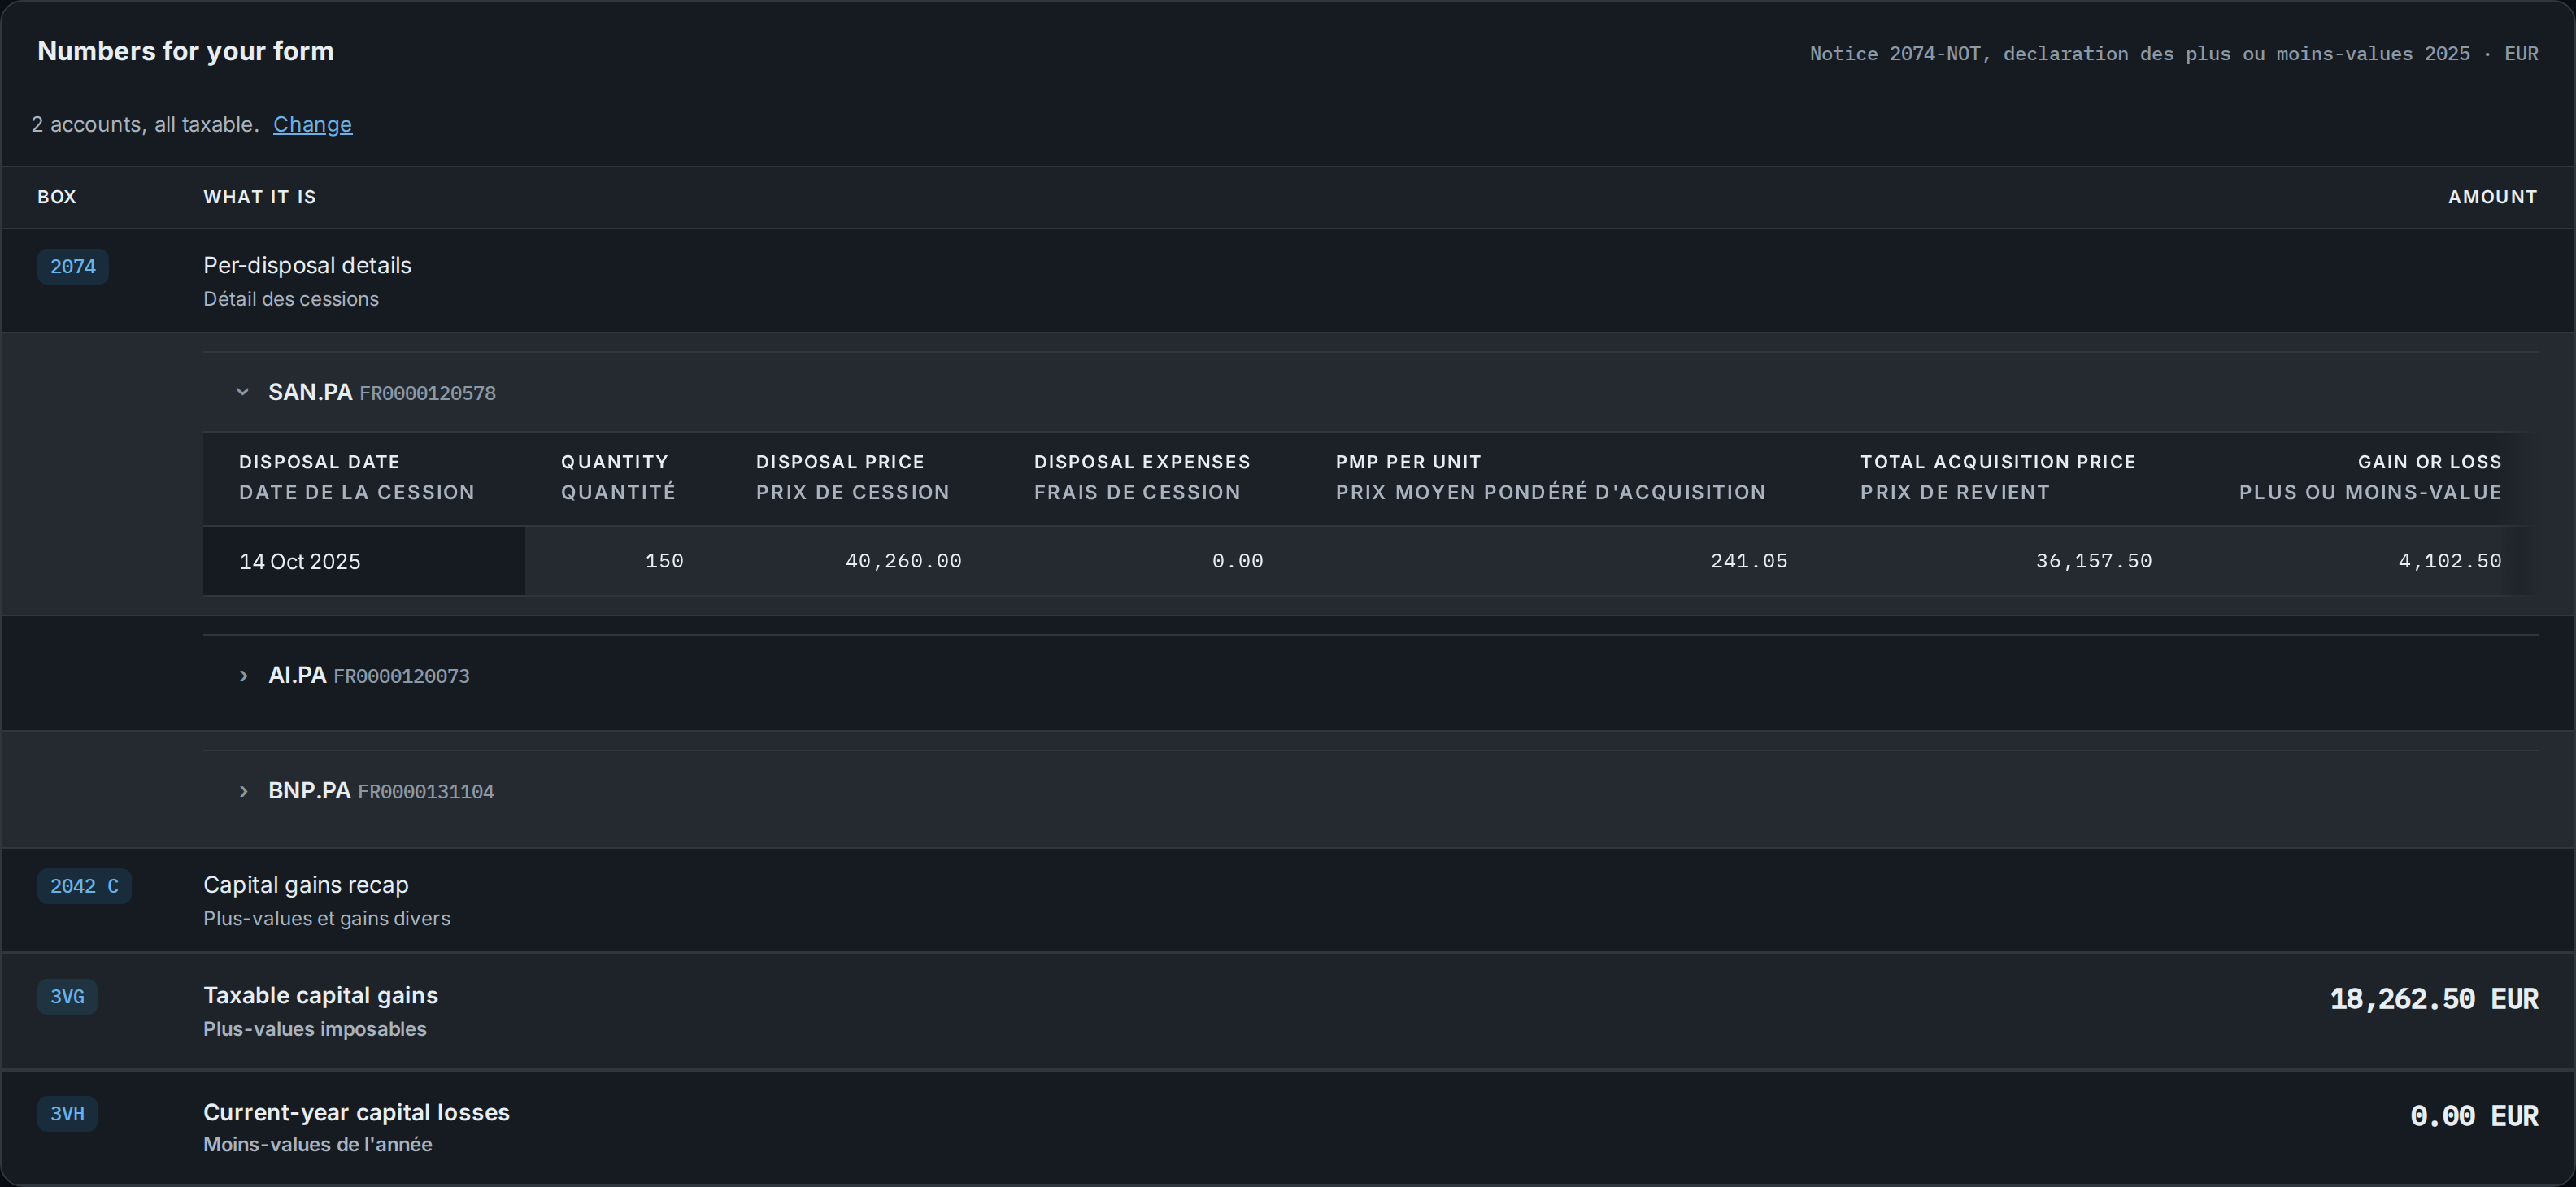
Each security opens into its own 2074 block, with the French column heading above the English one. A row carries the disposal date, quantity, gross price, selling expenses, the weighted average price per unit, the total acquisition price and the result. The 2042 C recap closes the sheet with box 3VG for the year's taxable gains and box 3VH for its losses.
Open the French pack AllInvestView
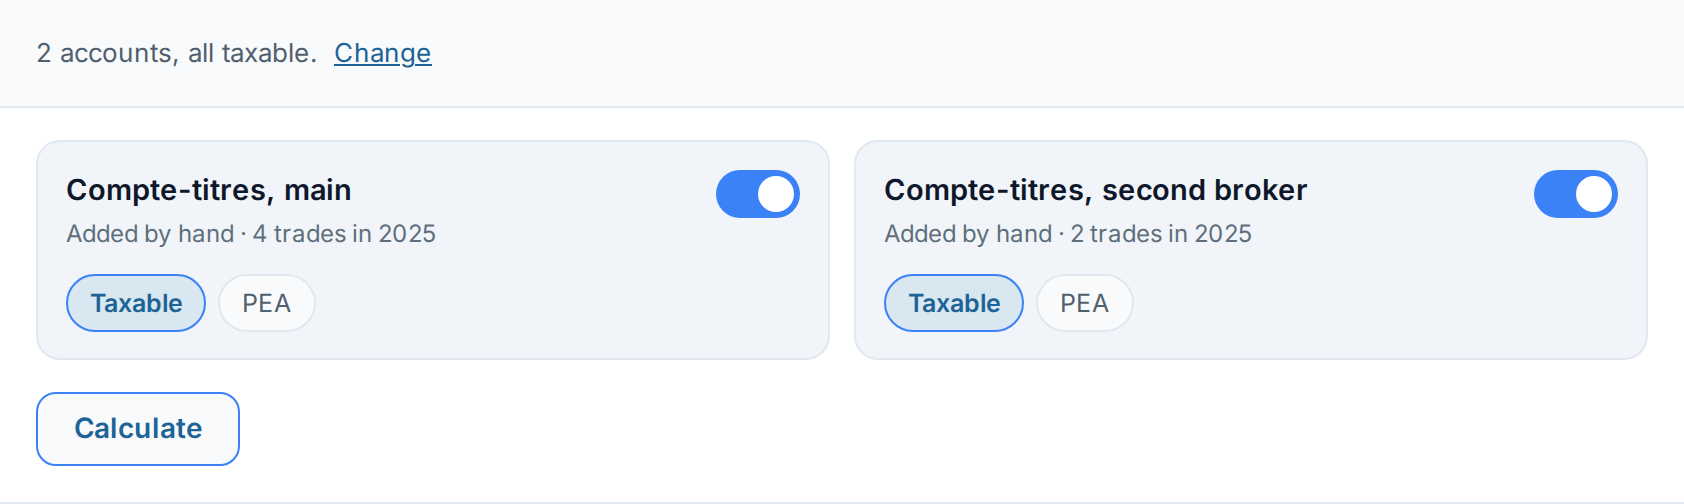
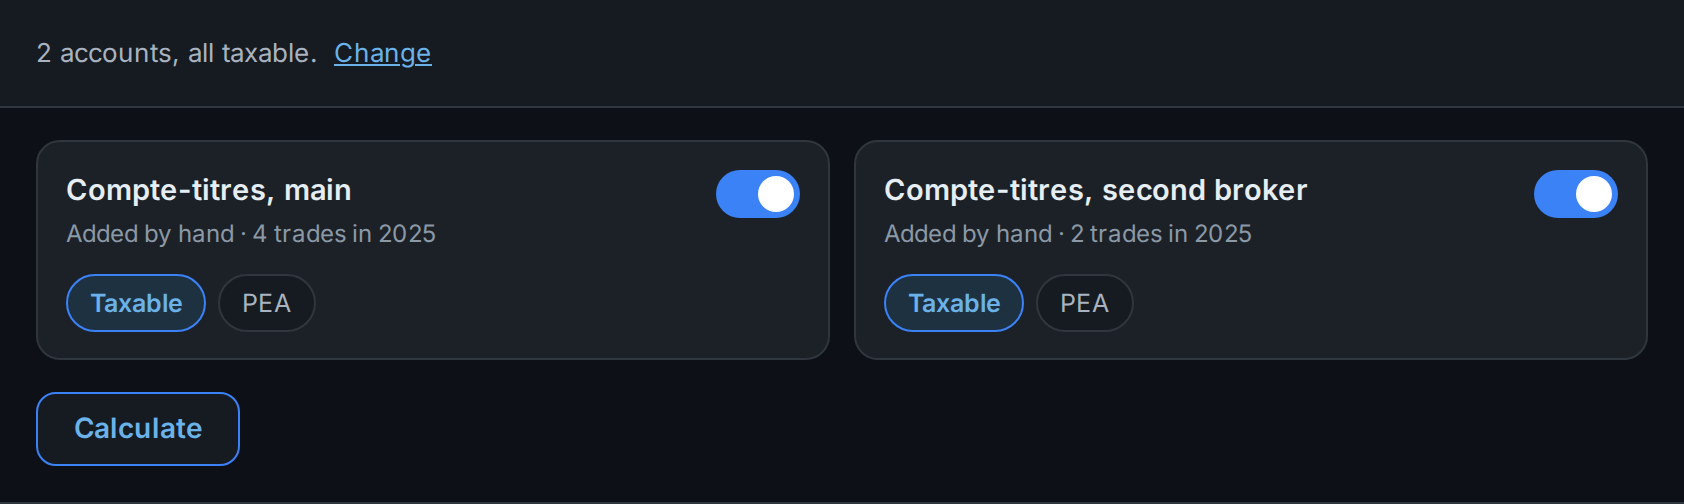
The weighted average pool is taxpayer-wide, so the pack asks which accounts belong in it before it calculates. Each card carries the wrappers a French investor really holds: an ordinary compte-titres, or a PEA. Mark an account as a PEA and it leaves the calculation, because that wrapper has its own regime rather than a 2074 line.
See the accounts stepAllInvestView
PDF, Excel and CSV take the 2074 rows and the 2042 C recap together, with the pool behind each unit cost. A missing settlement rate or an outstanding lot selection keeps the buttons off until you resolve it. Closing the year freezes the calculation revision, so the ten-year loss trail stays consistent from one return to the next.
See what exportsAllInvestView
It does not file the return, and the flat-tax figure is an estimate. For 2026 it combines 12.8% income tax with 18.6% social levies for 31.4%, or 20.3% where the calculator's qualifying health-regime case applies.
It uses the published 2025 Notice 2074 while it waits for the 2026 revision. A missing settlement rate, a cost basis it cannot reconstruct or a lot selection it still needs blocks the figures, and a PEA withdrawal inside the first five years stops the pack until that regime is built.
French reporting for fungible securities uses the prix moyen pondéré d'acquisition. The pack brings acquisitions and disposals from the included taxpayer accounts into a single pool, then carries that weighted cost into each 2074 disposal row. Where the titles sold can be identified individually, the calculation uses the selected actual costs instead, and it waits for that lot selection before releasing the amounts that depend on it.
Each completed row shows its date, quantity, gross price, disposal expenses, unit weighted average price, total acquisition cost and the resulting plus-value or moins-value. The annual recap then routes taxable gains to box 3VG and the year's losses to box 3VH.
Foreign-currency legs convert to euros using the settlement date. When that date is unavailable the calculation shows and uses the trade date, rather than silently choosing one. Prior securities losses remain available for ten years and are applied inside the pack's loss calculation.
The 2026 estimate uses a 12.8% income-tax component and 18.6% social levies, a combined 31.4%. Where the calculator's qualifying health-regime case applies it uses 7.5% social levies and a 20.3% combined rate.
Ticking box 2OP swaps the flat tax for your household's income-tax rate, and it applies to all your investment income at once rather than to one line. The pack can run that household comparison when you supply the figures, and it presents the outcome as a comparison rather than turning it into a filing number.
Not tax advice. You or your adviser must review the figures and file the return.
Build the taxpayer-wide pool once, review every 2074 row, and carry the finished recap into the 2042 C.
It produces Formulaire 2074 disposal rows and a 2042 C recap for boxes 3VG and 3VH, with figures in euros.
Fungible securities use a taxpayer-wide weighted average acquisition price, or PMP. Identifiable instruments use the actual selected costs.
Foreign-currency transactions use the settlement-date EUR exchange rate. If the settlement date is unavailable, the pack shows and uses the trade date.
The calculator uses 12.8% income tax plus 18.6% social levies for a combined 31.4% in 2026. The implemented health-regime exception has a 20.3% combined rate.
It can show an optional household-level 2OP comparison when the household inputs are supplied. The comparison is not a filing figure or a recommendation.
No. The premium pack prepares figures for review by you or your adviser. You remain responsible for completing and filing the return.