=SLOPE(B2:B61, C2:C61)Stock returns in column B, market returns in column C. The stock's column goes first: swap them and you get a different number.
Beta tells you how much a stock has tended to move when the market moves. A beta of 1 moves with the market. A beta of 2 has moved about twice as much, up and down, and 0.3 about a third as much. It's the slope of a line through the stock's returns plotted against the market's, usually five years of monthly returns against the S&P 500.
From October 2021 to September 2026, NVIDIA's beta against SPY, the S&P 500 fund, was 2.21 and Coca-Cola's 0.32. When SPY fell 18.8% from 19 February to 8 April 2025, NVIDIA fell 30.8% and Coca-Cola 1.6%.
The same thing written another way: correlation × the stock's volatility ÷ the market's volatility. In Excel or Sheets, =SLOPE(stock returns, market returns).
 NVIDIA
 The market (SPY)
 Coca-Cola
Each dot is one month from October 2021 to September 2026: SPY's return across, the stock's return up. Beta is the slope of the line that fits the dots best. The dashed line is a beta of 1, a stock that moves exactly with the market.
Coca-Cola swung about as much as SPY, 16.3% a year against 15.7%, yet its beta is 0.32. Its moves mostly had nothing to do with the market's, so the line through them is nearly flat. Beta measures how much of a stock's movement follows the market, not how much it moves.
Paste a stock's returns or prices and the market's for the same dates, or add up a portfolio's beta from its holdings. It opens with NVIDIA's five years from the chart above.
| If the market moves | Beta says, on average | On your total |
|---|
Six months is too short for a beta you'd rely on, but it's small enough to follow every number. Apple against SPY, monthly total returns from April to September 2026.
| Month, 2026 | Apple | SPY | Apple minus its average | SPY minus its average | Multiply the two | SPY's, squared |
|---|---|---|---|---|---|---|
| April | 6.92% | 10.51% | 2.04 | 7.66 | 15.62 | 58.63 |
| May | 15.11% | 5.26% | 10.23 | 2.41 | 24.62 | 5.79 |
| June | −7.27% | −1.03% | −12.15 | −3.88 | 47.18 | 15.08 |
| July | 6.76% | 0.03% | 1.88 | −2.82 | −5.31 | 7.97 |
| August | 2.66% | 2.68% | −2.22 | −0.17 | 0.38 | 0.03 |
| September | 5.10% | −0.33% | 0.22 | −3.18 | −0.70 | 10.13 |
| Average / sum | 4.88% | 2.85% | 81.80 | 97.63 |
=SLOPE(B2:B61, C2:C61)Stock returns in column B, market returns in column C. The stock's column goes first: swap them and you get a different number.
=COVARIANCE.S(B2:B61, C2:C61) / VAR.S(C2:C61)Gives exactly the same beta. In Sheets, COVARIANCE.S and VAR.S work the same way.
=B3/B2-1Turn month-end prices into returns first, then use SLOPE on the returns. Beta on the prices themselves means nothing. Adjusted closes count dividends.
A real test. Each beta here comes from the 60 months before the fall, February 2020 to January 2025 (Coinbase and Palantir from when they listed). Then, from SPY's record close on 19 February 2025 to its low on 8 April, it fell 18.8%. Beta × 18.8% is what beta pointed to for each one. Below it, what really happened.










The high-beta names fell hard and the low-beta ones much less, as their betas said. NVIDIA, beta 1.62, pointed to a 30.4% fall and fell 30.8%; AMD pointed to 31.1% and fell 31.8%. Across a portfolio of many holdings, that's what beta is good for.
Apple, beta 1.20, fell 29.6% against the 22.5% its beta pointed to, hit by tariff news aimed at its supply chain. Walmart fell 21.1%, twice its prediction. Berkshire Hathaway, expected to lose 16.5%, ended up 1.8%. A single stock's own news can outweigh its beta.
Each site chooses how many years to look back, whether to use daily, weekly or monthly returns, and which index to compare against. The same six stocks, all against SPY:
| Stock | 5 years, monthly60 returns to Sep 2026 | 2 years, weekly105 returns to 23 Oct 2026 | 1 year, daily251 returns to 27 Oct 2026 |
|---|---|---|---|
| NVDA | 2.21 | 1.86 | 1.93 |
| META | 1.18 | 1.65 | 1.51 |
| AAPL | 1.07 | 1.05 | 0.56 |
| WMT | 0.57 | 0.51 | −0.10 |
| KO | 0.32 | 0.09 | −0.28 |
| XOM | 0.22 | −0.04 | −0.70 |
Five years smooths things out; one year reflects what the stock has been doing lately. Over the year to October 2026, Exxon Mobil and Coca-Cola mostly rose on days the market fell.
Daily returns pick up every day's noise, and stocks that trade less react to the market a day late. Monthly returns are the most common choice for a stock's published beta.
Most US sites use the S&P 500. A UK or European site may use the FTSE 100 or the Euro Stoxx 50, and against a different market the same stock gets a different beta.
Leaving dividends out barely moves most betas, but it can for high-yield stocks around their ex-dividend dates. Use the same basis for the stock and the index.
Beta measures one kind of risk: how much a holding follows the market. It's blind to the rest.
Meta's beta of 1.18 says it moves a bit more than the market. In 2022 SPY lost 18.2% and Meta lost 64.2%. Its correlation with the market is only 0.43: the market explains about a fifth of its monthly moves, and beta doesn't see the rest. Its volatility, 42.8% a year, does.
The long-term Treasury fund TLT has a beta of 0.52, yet it fell 31.2% in 2022 as interest rates rose, far more than SPY. Verizon, beta 0.26, lost 20.0% the same year. A low beta only says it didn't move much with the stock market.
Coca-Cola's beta on each calendar year's daily returns:
Exxon Mobil went from 0.53 in 2022 to −0.83 in 2026. A beta is a measurement of the past; check it again before you lean on it. *To 27 October.
R-squared says how much of a stock's movement the market explains. For NVIDIA it's 48%, so its beta of 2.21 describes a real pattern. For Coca-Cola it's 9%: the market explains less than a tenth of its monthly moves, so its beta of 0.32 is a weak guide to what it does next.
There's no good or bad beta, only one that fits what you want from a holding. These bands use the five-year monthly betas on this page.
Below 0: moves against the marketRare over five years. More common over a single year of daily returns.XOM 1y daily −0.70
0 to 0.7: defensiveConsumer staples, healthcare, utilities, gold, Treasuries. They usually lag in strong markets and hold up better in falls.GLD 0.18JNJ 0.21KO 0.32PG 0.38MCD 0.44WMT 0.57
0.7 to 1.3: market-likeLarge, diversified companies and broad funds.JPM 1.02AAPL 1.07MSFT 1.10META 1.18QQQ 1.22
Above 1.3: aggressiveFast-growing tech, chip makers and crypto-linked shares. Bigger gains in rallies, bigger falls in sell-offs. More in the highest beta stocks list.AMZN 1.45PLTR 1.60TSLA 1.90NVDA 2.21AMD 2.45COIN 3.40
A 2.21 stock is a lot on its own and much less as a fifth of a portfolio. 40% SPY, 20% NVIDIA, 20% Coca-Cola and 20% Johnson & Johnson has a beta of 0.95, just under the market's. The calculator's portfolio tab does the sum.
A beta above 1 suits money you won't touch for many years and can leave alone through a 30% fall. Money you'll need soon belongs in low-beta holdings or cash, because a high-beta portfolio can be down a lot exactly when you need to sell.
The four numbers that usually sit next to each other on a risk report, and the question each one answers.
| Measure | The question it answers | NVIDIA against SPY, 2021 to 2026 |
|---|---|---|
| Beta | How much does it move when the market moves? | 2.21: about 2.2% for each 1% the market moves |
| Standard deviation | How much does it swing, for any reason? | 50.1% a year, against 15.7% for SPY |
| Correlation | How closely does it move in step with the market, from −1 to 1? | 0.69: same direction most months, not all |
| Alpha | How much did it earn beyond what its beta explains? | +2.49% a month: in a month when SPY was flat, the beta line puts NVIDIA up 2.49% |
Your broker shows the accounts you hold there. AllInvestView puts every account you add together and works out the portfolio's beta against the index you choose, with each stock's own beta one click away.
The Analytics tab works out your portfolio's beta from its daily returns against the index you pick, next to alpha, correlation and R-squared. It covers every account you add, so a low-beta account at one broker and a high-beta one at another come out as one number.
See the portfolio analyzer AllInvestView
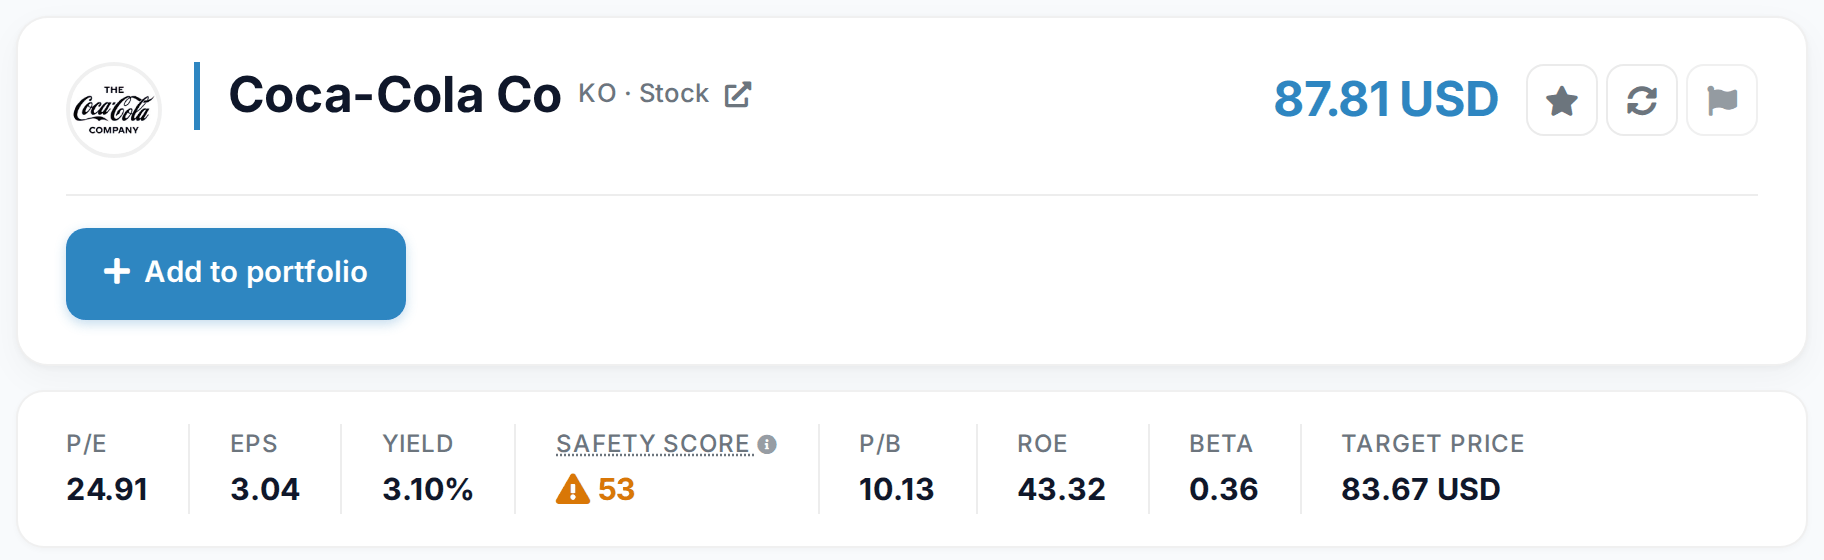
Each stock's page shows its beta beside the P/E, yield and other key figures, so you can see how much a stock has moved with the market before you buy it. The same figure sorts the highest beta stocks list.
See the highest beta stocksAllInvestView
Add every account you hold and see the beta, alpha, correlation and volatility of your stocks and funds against the index you pick. No spreadsheet of returns to keep up to date.
The stock has tended to move about one and a half times as much as the market: up about 15% when the market rose 10%, down about 15% when it fell 10%. It's an average over the period measured, not a promise. Over the five years before the 2025 sell-off NVIDIA's beta was 1.62. SPY then fell 18.8%, which pointed to about 30.4% for NVIDIA, and it fell 30.8%.
Neither. A high beta adds more of the market's ups and downs, so it suits money you won't need for years and can sit through a big fall. A low beta follows the market less, so it usually lags in strong markets and holds up better when the market falls, though it can still swing on its own news. What matters is the beta of the whole portfolio and whether you can live with it in a bad year.
Take the stock's returns and the market's returns over the same periods, usually 60 months. Divide the covariance of the two by the variance of the market's returns. In Excel or Google Sheets that's =SLOPE(stock returns, market returns), with the stock's column first.
Yes. A negative beta means the stock tended to move the other way from the market over that period. It's rare over five years of monthly returns, but it happens over shorter windows: on daily returns from October 2025 to October 2026, Exxon Mobil's beta was -0.70 and Coca-Cola's -0.28.
It depends on what the stock is for. Below about 0.7 is typical for consumer staples, utilities and healthcare, around 1 for big diversified companies, and 1.5 to 3.5 for fast-growing tech and crypto-linked shares. Pick the level that fits the portfolio you want, then check the portfolio's beta, not just the stock's.
Each site picks its own period, return frequency and index. Meta's beta against SPY was 1.18 on five years of monthly returns, 1.65 on two years of weekly returns and 1.51 on one year of daily returns. None of them is wrong; compare betas only when they were measured the same way.
Multiply each holding's beta by its share of the portfolio and add them up. 40% in SPY (1.00), 20% in NVIDIA (2.21), 20% in Coca-Cola (0.32) and 20% in Johnson & Johnson (0.21) gives 0.95. AllInvestView works it out from your portfolio's own daily returns against the benchmark you choose, across every account you add.
Checked on 28 October 2026.
Betas, correlations and volatilities are worked out by AllInvestView from month-end closing prices with dividends reinvested, October 2021 to September 2026 (the sell-off betas: February 2020 to January 2025, 45 months for Coinbase and 52 for Palantir), against SPY, using the sample covariance and variance; volatility is the standard deviation of the monthly returns × √12. Weekly and daily betas use Friday and daily closes over the windows shown. The 2025 moves run from the 19 February close to the 8 April close, with dividends. Betas are a measurement of the past, not a forecast, and none of this is investment advice.