1.10 × 0.95 − 1The investments made 10%, then lost 5%. That's the whole answer. Deposit $1 or $1 million on 1 July and the TWR is still 4.50%.
Time-weighted return (TWR) measures how your investments performed with the effect of your deposits and withdrawals taken out. You split the period at every cash flow, work out the return of each piece, then chain them: multiply (1 + each return) together and subtract 1. It's the return funds publish, and the one to put next to an index.
Its partner is the money-weighted return (MWR, the same thing as IRR or XIRR), which counts when you added money and how much. Three people who held the same S&P 500 fund from 2022 to 2025 all got a TWR of 52.41%. Their money-weighted returns were 5.81%, 11.11% and 16.13% a year, because they put money in and took it out at different times.
Each R runs from just after one cash flow to just before the next. Up 10%, then a deposit, then down 5%: 1.10 × 0.95 − 1 = 4.50%, whatever the size of the deposit.
One year, $10,000 to start and one $10,000 deposit halfway through. The deposit splits the year into two periods.
1.10 × 0.95 − 1The investments made 10%, then lost 5%. That's the whole answer. Deposit $1 or $1 million on 1 July and the TWR is still 4.50%.
$20,000 in, $19,950 at the endTwice as much money sat through the losing half as through the winning half, so in money terms the year was a small loss. The money-weighted return counts that; TWR leaves it out on purpose.
Enter the value at the start, each deposit or withdrawal with the value just before it, and the value at the end. You get the TWR, the same figure per year, and your money-weighted return beside it. It opens with Ben's four years in an S&P 500 fund from the example below.
Fill in the new cash flow to include it.
A new period starts at every cash flow. TWR multiplies them together, so no period counts more because more money was in it.
Ana, Ben and Cara each held an S&P 500 index fund from 1 January 2022 to 31 December 2025, with dividends reinvested. Only their deposits and withdrawals differ.
The fund did the same for all three, so their TWR is the same: 52.41%, or 11.11% a year. Ben added money after the 2022 fall and Cara took some out then, and the money-weighted return shows what that timing did to each of them. A plain gain on money put in misleads too: Ben's $20,000 grew to $33,852, a 69% gain, but that doesn't mean the fund beat the index.
Neither one is the right one. They answer different questions, and a good tracker shows both.
| Question | Time-weighted (TWR) | Money-weighted (MWR, IRR) |
|---|---|---|
| It answers | How did the investments do? | How did my money do? |
| Deposits and withdrawals | Taken out. Each one starts a new period. | Counted, by size and by date. |
| What you need | The portfolio value on every cash-flow date. | Only the cash flows, their dates and the end value. |
| Who uses it | Funds, fund managers and index providers. The GIPS standards for investment firms require it for most strategy returns. | Most brokers' "personal return", and XIRR in a spreadsheet. |
| Use it to | Compare your portfolio with an index, a fund or another portfolio, and judge what you picked. | See what your saving and timing earned you, and check progress toward a goal. |
| Annual figure | Chain the periods, then annualize the total. | XIRR gives a yearly rate directly. |
Big deposits or withdrawals, and a market that moved a lot in between. If more of your money was invested in the periods that did best, your money-weighted return ends up above the TWR; if more was in the weak periods, below it. With no cash flows at all, the two give the same yearly figure, like Ana's 11.11%.
Gain divided by money put in. Easy, but it ignores how long the money was invested: $1,000 added last week counts the same as $1,000 added five years ago. Use it for a quick look, not to compare anything.
The math is short, which is why the mistakes are easy to make.
(1 + TWR)365 ÷ days − 1. The S&P 500's 52.41% over the four years 2022 to 2025 is 11.11% a year, not 52.41 ÷ 4 = 13.1%. Don't annualize less than a year: three months at +5% isn't a 21.6% year, and the GIPS standards don't allow it.
+10% then −5% is not +5%. It's 1.10 × 0.95 − 1 = 4.50%. After a 50% fall, a 50% rise leaves you at 75% of where you started, not back to even.
Measure each period up to the value just before the money arrives. In the example, $21,000 ÷ $10,000 would turn a 10% half-year into 110%. The deposit belongs to the start of the next period.
A dividend paid into your account is return, so leave it in the value. A cash flow is cash or investments moving into or out of the portfolio you're measuring: a deposit, a withdrawal, shares transferred in. If you take dividends out to your bank, that's a withdrawal.
Exact TWR needs a valuation every time money moves. If you only have the start and end values, Modified Dietz gives an estimate from the cash flows alone.
The weight is the share of the period the money was invested. The example year: (19,950 − 10,000 − 10,000) ÷ (10,000 + 0.5 × 10,000) = −0.33%, the same as its money-weighted return.
Ben's four years, with his deposit in for three of them: (33,852 − 10,000 − 10,000) ÷ (10,000 + 0.75 × 10,000) = 79.15%, or 15.69% a year, close to his money-weighted 16.13% and far from the fund's 11.11%.
Modified Dietz weights money by time, so for a single period it estimates the money-weighted return, not the TWR: −0.33% here, against a TWR of 4.50%. Firms get close to a true TWR by working out Modified Dietz for each month, or each period between big flows, and chaining them.
Since 2010 the GIPS standards have required firms to value portfolios on the date of any large cash flow (private market portfolios have their own rules), so the periods split exactly where the money moved.
The "rate of return" on your statement is often money-weighted. That's why it rarely matches the fund's published return.
Your "Personal Rate of Return" is money-weighted. Fidelity reports its own funds with the time-weighted method.

Personal performance is an internal rate of return, so it counts your deposits and how long each was invested. Fund returns on the site are time-weighted.
MWR and TWR buttons switch between the two as the performance measure.

Both, across all your accounts at once, with the TWR set against a benchmark of your choice.
A broker's statement usually covers the accounts you hold with that broker. AllInvestView puts every account together, values the whole portfolio every day from your trades and prices, and takes out each deposit and withdrawal on the day it happens.
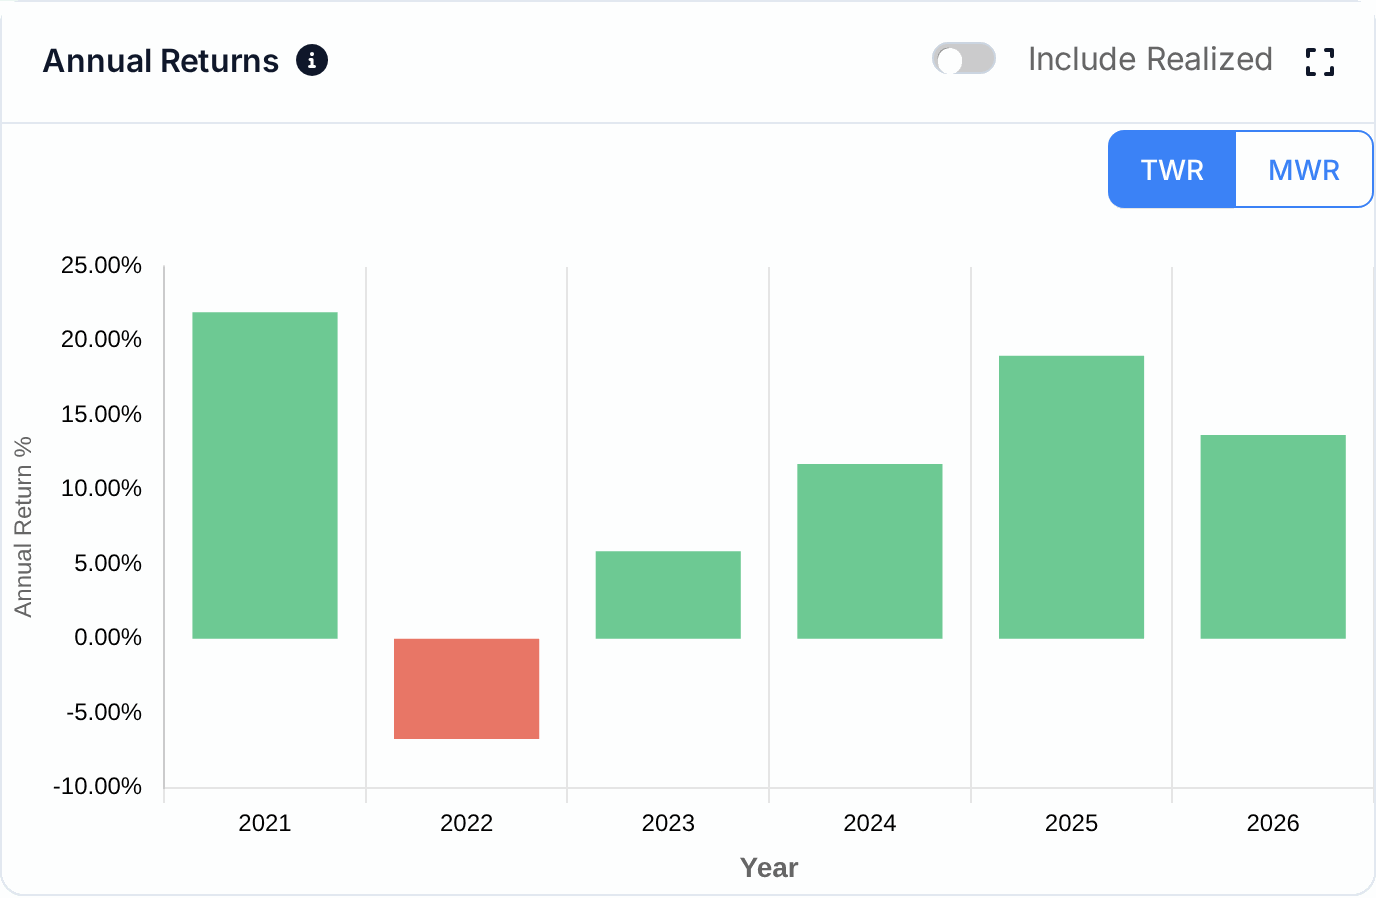
The dashboard shows every calendar year of your whole portfolio as a bar. TWR is the default; one click switches the same chart to the money-weighted return, so you can see where your deposits helped or hurt. Every account you add is counted together, so it's the return of everything you own.
Read the portfolio returns guideAllInvestView
CAGR (TWR) is your time-weighted return per year over the dates shown, with the benchmark's beside it. The TWR multiple shows how much $1 grew with your deposits taken out, and the wealth multiple what each dollar you put in is worth now. Max drawdown, volatility and beta are worked out from the same time-weighted returns, so a big deposit never looks like a gain.
See the portfolio analyzerAllInvestView
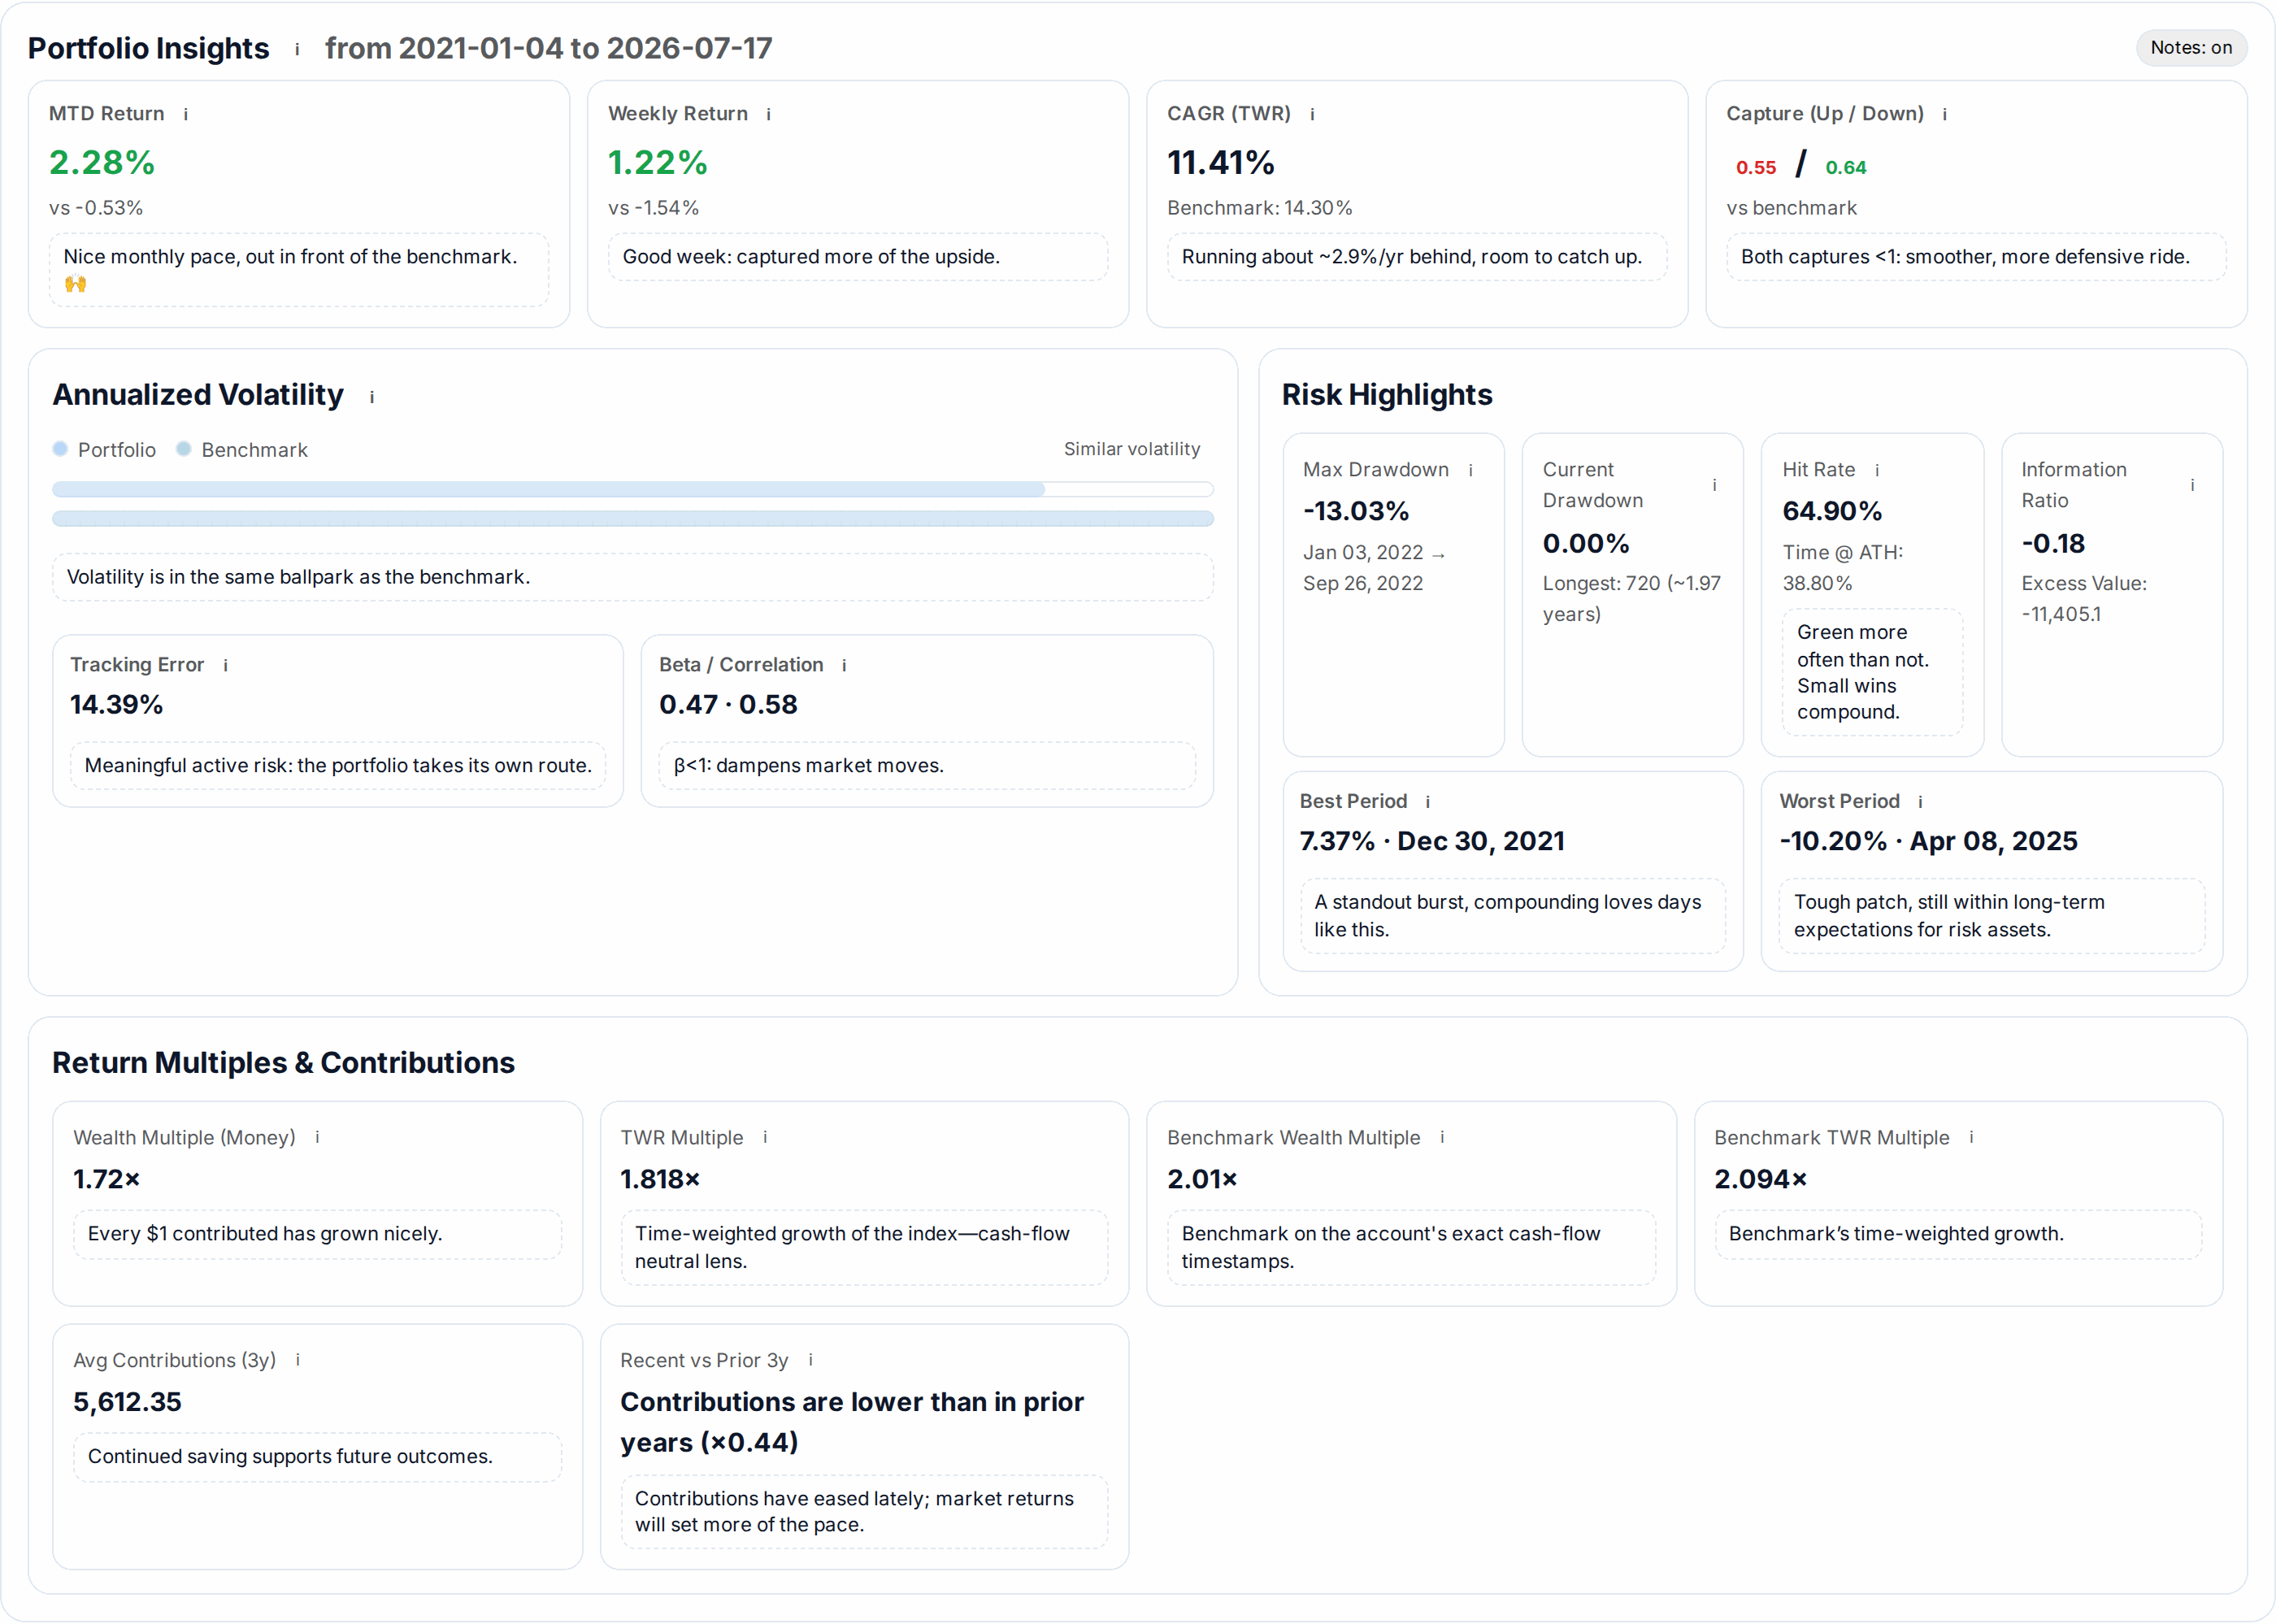
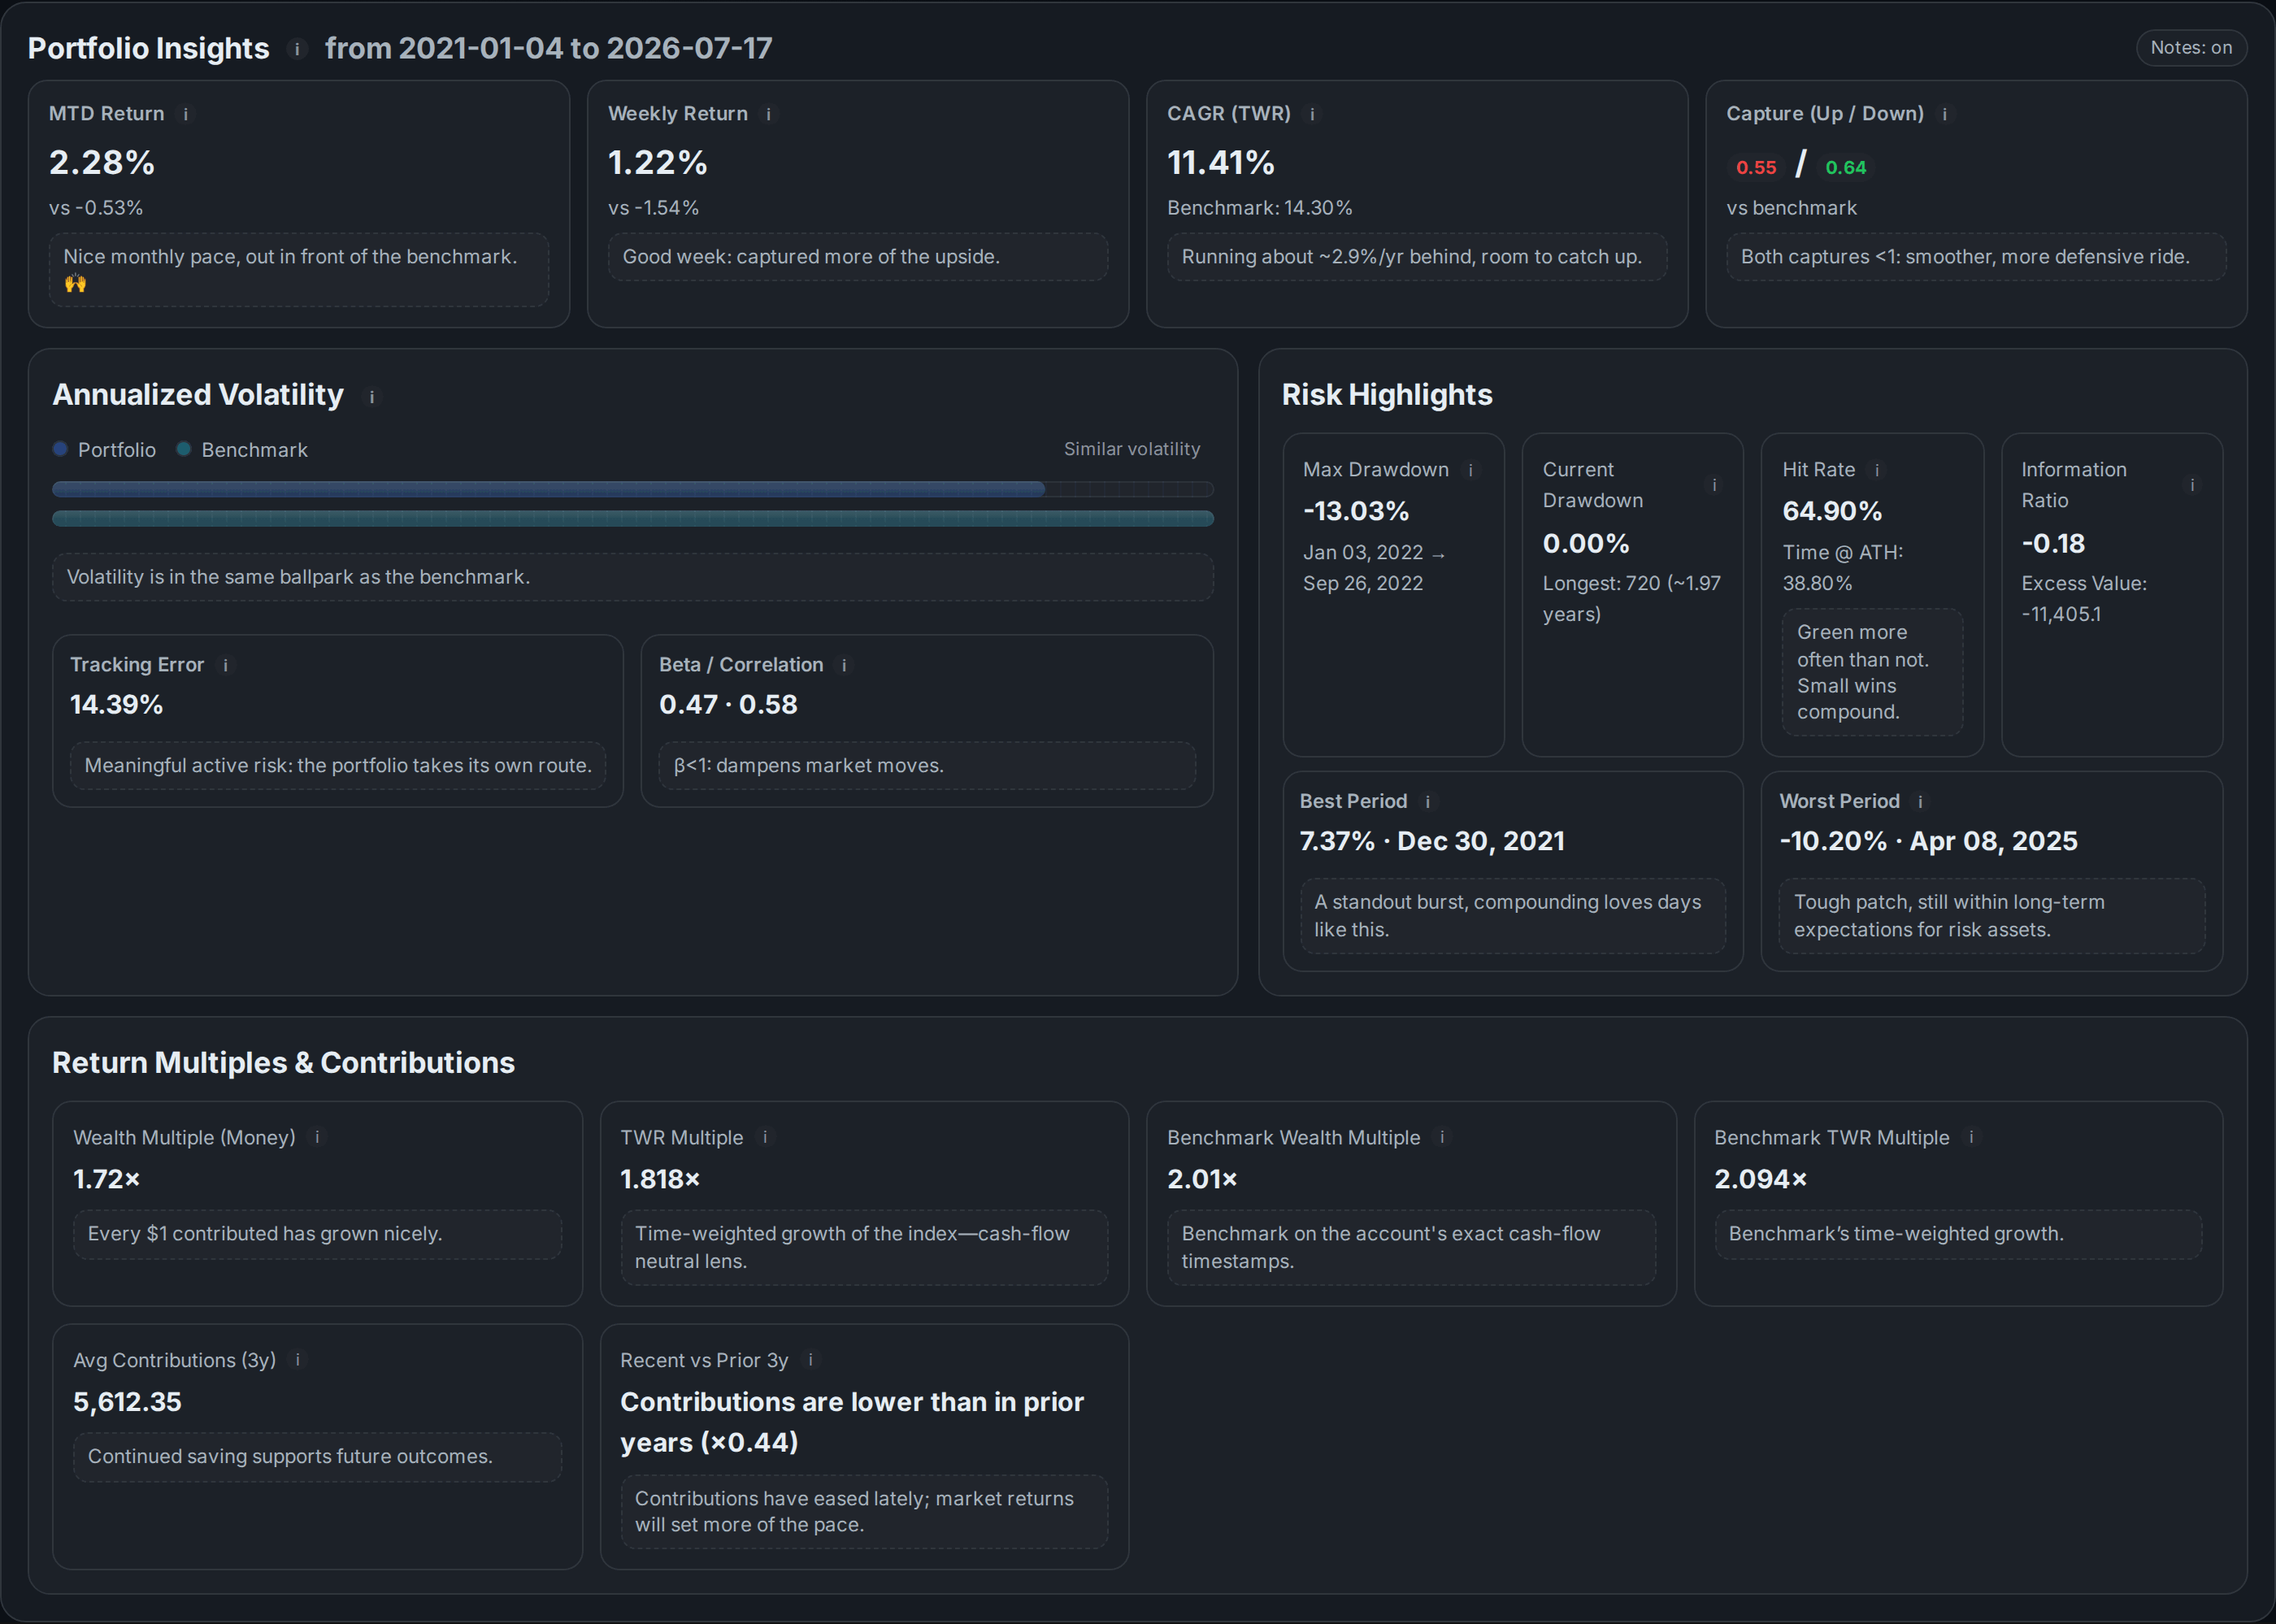
Add every account you hold and see the time-weighted return next to an index, your money-weighted return beside it, and each year's result. No spreadsheet of values on deposit dates to keep.
The return of a portfolio with the effect of deposits and withdrawals removed. It splits the period at every cash flow, works out each piece's return and multiplies them together, so it shows how the investments did, whatever you added or took out.
Split the period at every deposit or withdrawal. For each piece, divide the value just before the next cash flow by the value just after the previous one and subtract 1. Then multiply (1 + each return) together and subtract 1. Up 10%, then down 5% after a deposit: 1.10 × 0.95 − 1 = 4.50%.
Time-weighted return removes the effect of your cash flows and shows how the investments did. Money-weighted return (IRR) counts when and how much you added or withdrew, so it shows how your own money did. From 2022 to 2025 an S&P 500 fund had a TWR of 52.41%, while three investors in it had money-weighted returns of 5.81% to 16.13% a year.
Neither. Use TWR to compare your portfolio with an index or a fund, because it isn't affected by when you added money. Use IRR, the money-weighted return, to see what your savings actually earned, timing included.
Not on its own. The chained TWR covers the whole period. To annualize it, raise (1 + TWR) to the power of 365 divided by the number of days and subtract 1: 52.41% over four years is 11.11% a year. Periods shorter than a year shouldn't be annualized.
Your gain in money depends on how much you had invested at each moment. If you added a lot before a fall, you can lose money in a period with a positive TWR. In a year that went +10% then −5%, with $10,000 added halfway, the TWR is +4.50% but the portfolio ended $50 below the $20,000 put in.
Put each period's return in a column, say B2:B5, and use =PRODUCT(1+B2:B5)-1. Older versions of Excel need it entered with Ctrl+Shift+Enter. For the money-weighted return, use XIRR: enter the starting value and each deposit as negatives, withdrawals and the end value as positives, with the date of each.
Checked on 23 October 2026.
The three investors use the S&P 500 total return index with no fees or taxes; a real fund returns slightly less after its costs. None of it is personal investment advice.