US: expense ratio
The "total annual fund operating expenses" line in the prospectus fee table, gross and net. ETFs and mutual funds report it the same way.
An expense ratio is the yearly fee a mutual fund or ETF charges to run the fund, as a percentage of what you hold. A 0.03% expense ratio costs $3 a year on $10,000. At 0.64%, the 2025 average for actively managed stock mutual funds, the same $10,000 costs $64.
You never get a bill for it. The fund takes the fee out of its own assets a little every day, so the price and the return you see are already after it. That's why it's easy to miss: over 30 years at 7% a year before fees, $10,000 grows to $75,440 in the 0.03% fund and $62,786 in the 0.64% one.
$10,000 in SPY: $10,000 × 0.0945% = $9.45 a year, about 2.6 cents a day.

Pick two funds or type any two expense ratios, then set what you invest and for how long. It shows the fee in dollars this year, everything each fund takes over the years, and how far apart the two balances end up.
The shaded gap is what the higher fee costs: the fees themselves plus the growth that money would have earned.
| After | Fund A | Fund B | Gap |
|---|
Nothing leaves your brokerage account. The fund pays its costs out of the money it manages, so the fee comes off the fund's value before you see it.
About 1/365 of the yearly rate. On $10,000 in SPY at 0.0945%, that's roughly 2.6 cents a day.
The fund's net asset value counts the fees owed as a liability, so the price per share already has them taken off.
The return a fund reports, and the gain you see at your broker, are what's left after the expense ratio. There's no separate line for it.
One fund, four feesVanguard 500 Index Fund sells four share classes of the same portfolio. In 2025 each class's return was lower by about its fee: the 0.14% class made 17.71% and the 0.01% class 17.86%.
Every US fund prospectus has a fee table near the front. Here is The Growth Fund of America's Class A, one of the biggest actively managed stock funds, read line by line.
Most index ETFs have no 12b-1 fee and fold everything into one figure: VOO's whole 0.03% is an eighth of this fund's 12b-1 fee alone.
The gross expense ratio is what it costs to run the fund. The net expense ratio is what you pay after the manager waives part of its fee or pays some costs itself. A fund with no waiver has the same figure for both.
New funds often waive fees to win their first investors. Read the net figure as today's price and the gross one as the price it can go back to, and look for the end date in the fee table's footnotes. Right after it, the prospectus works the fees out in dollars on a hypothetical $10,000 growing 5% a year.
It depends on what the fund does. Here are real funds next to the 2025 averages from the Investment Company Institute. The striped bars are weighted by the money in each fund type; the median is the middle share class.
An S&P 500 or total market fund is a commodity, and 0.03% is easy to find. Index stock mutual funds averaged 0.05% in 2025.
Dividend, income, sector and international ETFs vary more. SCHD charges 0.06%, and JEPI, which sells call options for extra income, 0.35%.
That's the 2025 average for active stock mutual funds. To keep up with a 0.03% index fund, the manager has to earn back the gap in fees, about 0.6 percentage points a year at that average.
Fees have come a long way down: in 1996 the average dollar in a stock mutual fund paid 1.04% a year, against 0.40% in 2025. The simple average share class still charged 1.08% in 2025, because most of the money sits in the cheapest funds.
If you hold several funds, your real cost is the weighted average: each fund's expense ratio times its share of your money. Put in your funds and what each is worth; it starts with an example five-fund portfolio.
The idea is the same everywhere: the yearly running cost as a share of the fund. The name and the document change.
The "total annual fund operating expenses" line in the prospectus fee table, gross and net. ETFs and mutual funds report it the same way.
UCITS funds publish an ongoing charges figure (OCF) or total expense ratio (TER) in their key information document. The EU version of that document also lists the fund's transaction costs on their own line. The Vanguard S&P 500 UCITS ETF (VUSA) has an OCF of 0.07%.
VUSA and VOO track the same S&P 500, at 0.07% and 0.03%. On 10,000 invested that's 7 against 3 a year: both small, and tax and currency usually matter more when you choose between them.
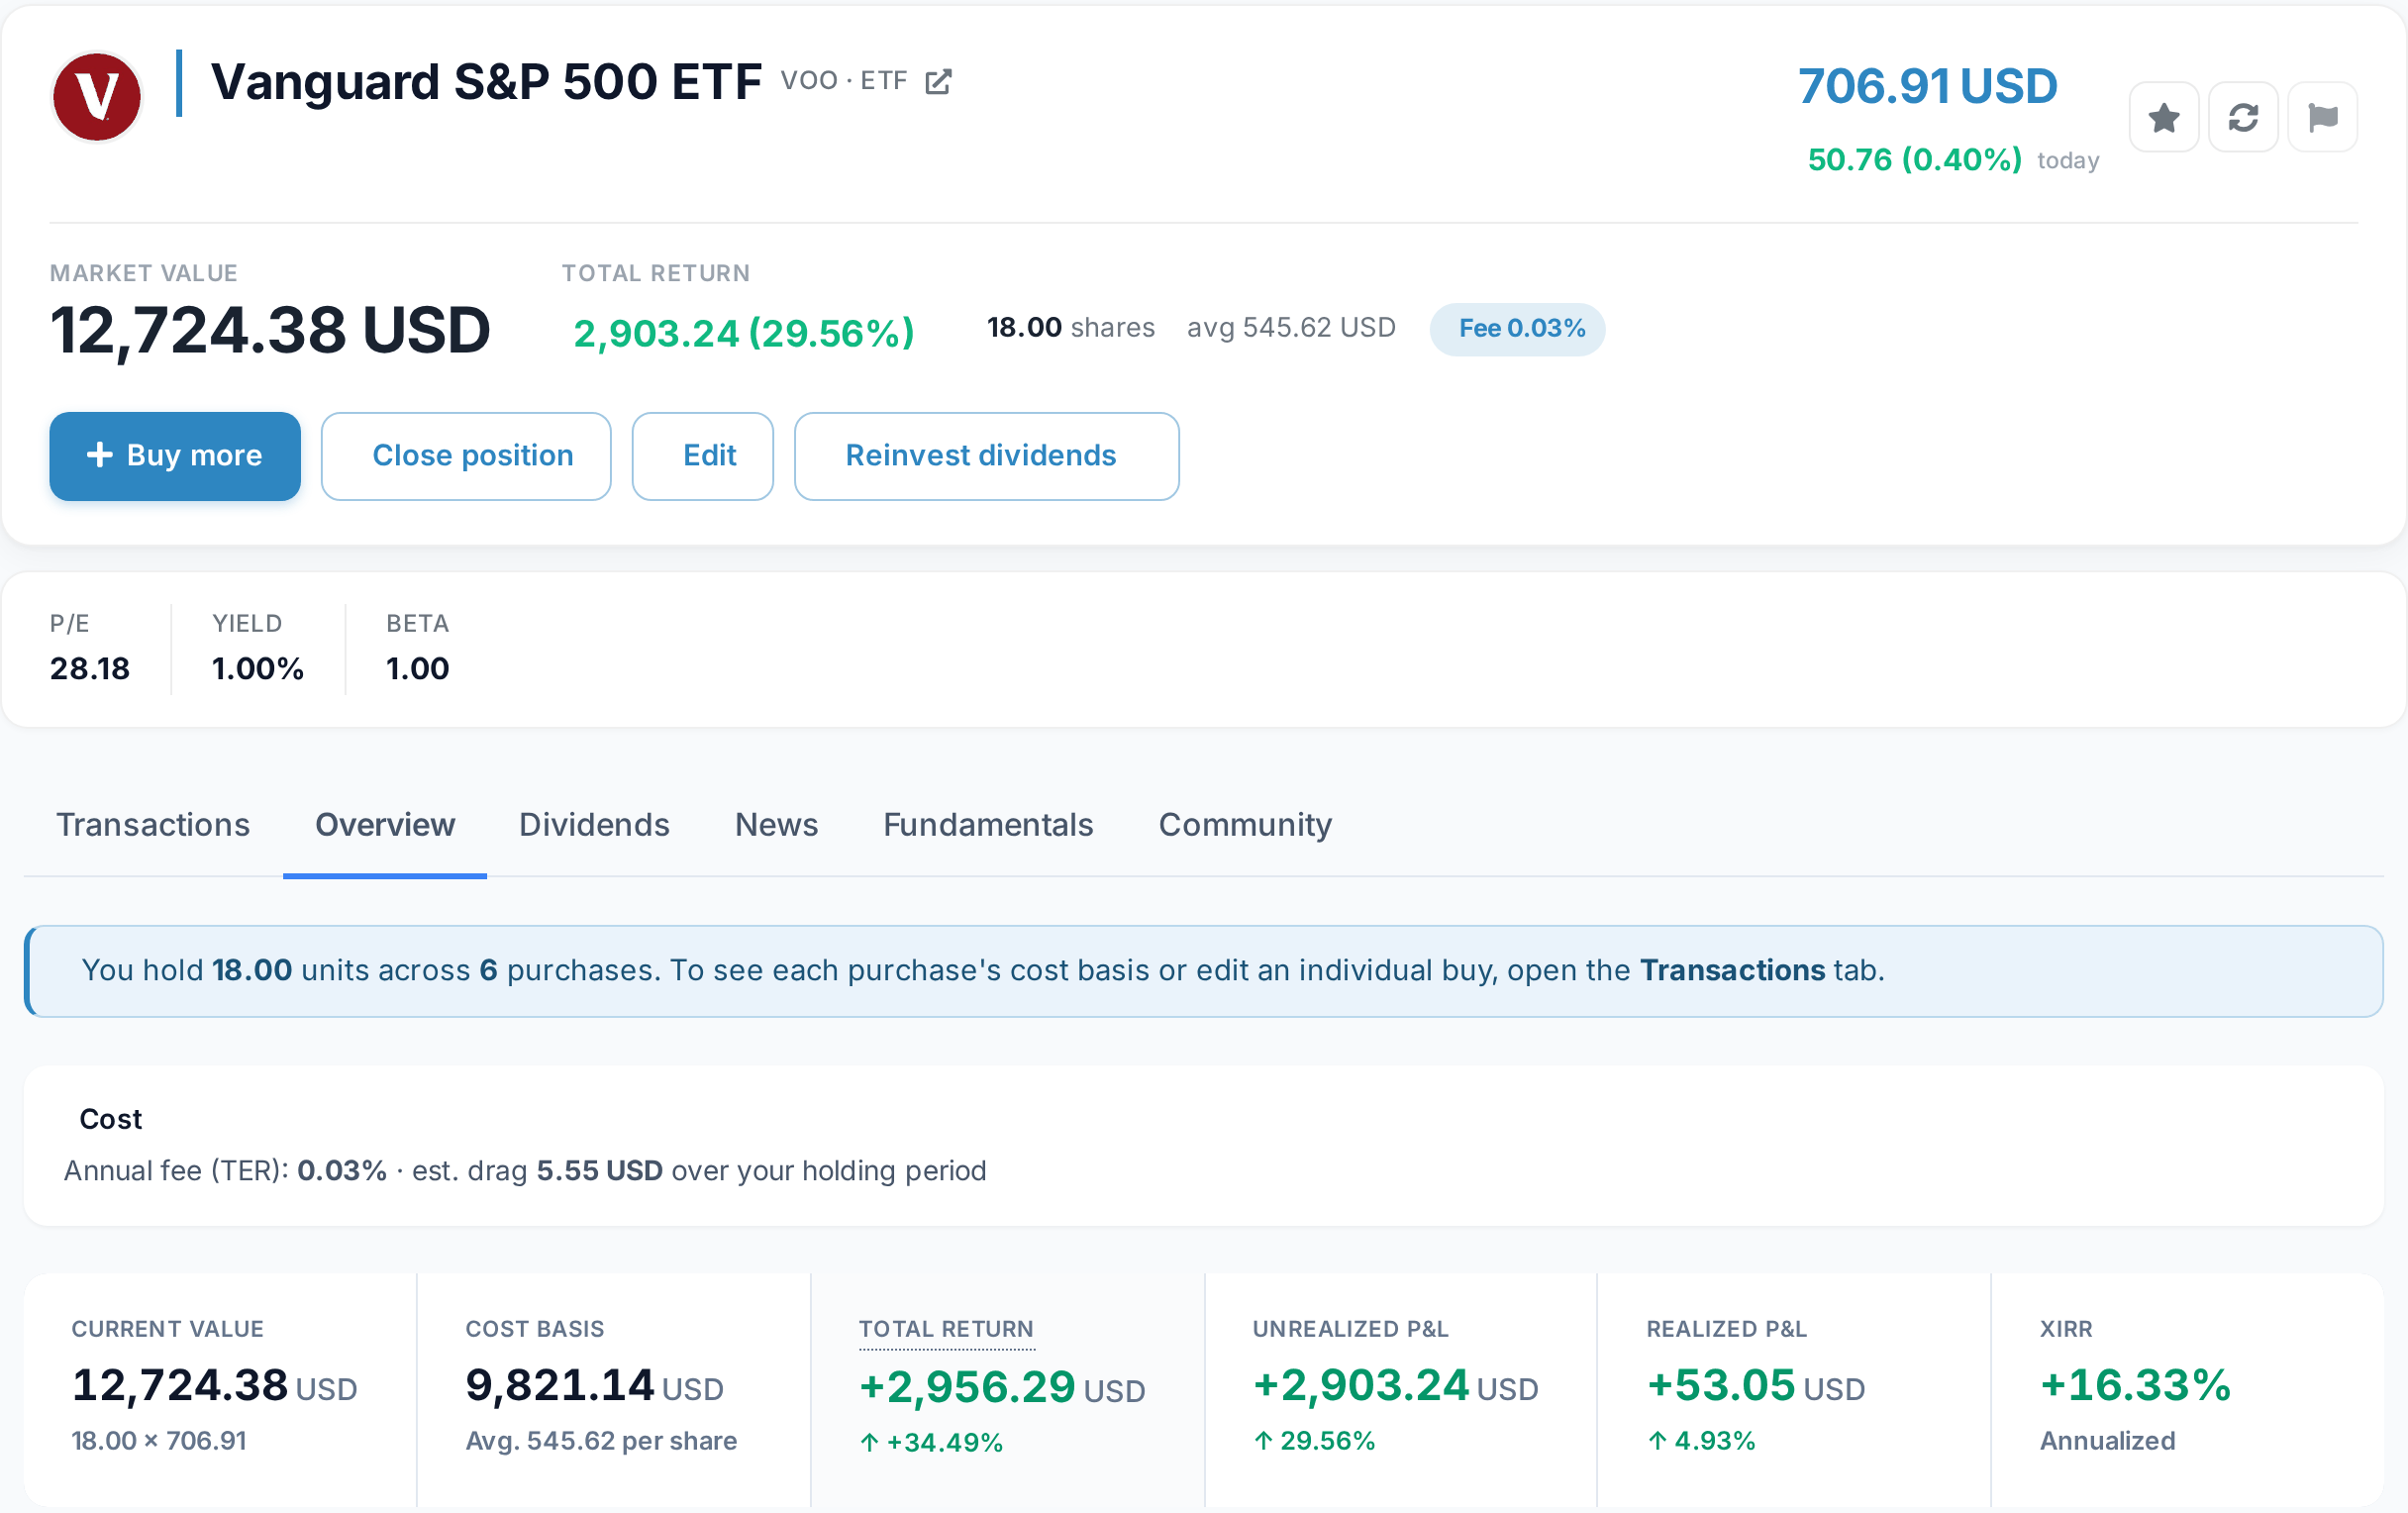
In AllInvestView each holding can carry its fund's annual fee. It shows next to your shares, with an estimate of what the fee has cost you since you bought, and the funds from every broker you use sit in one portfolio.
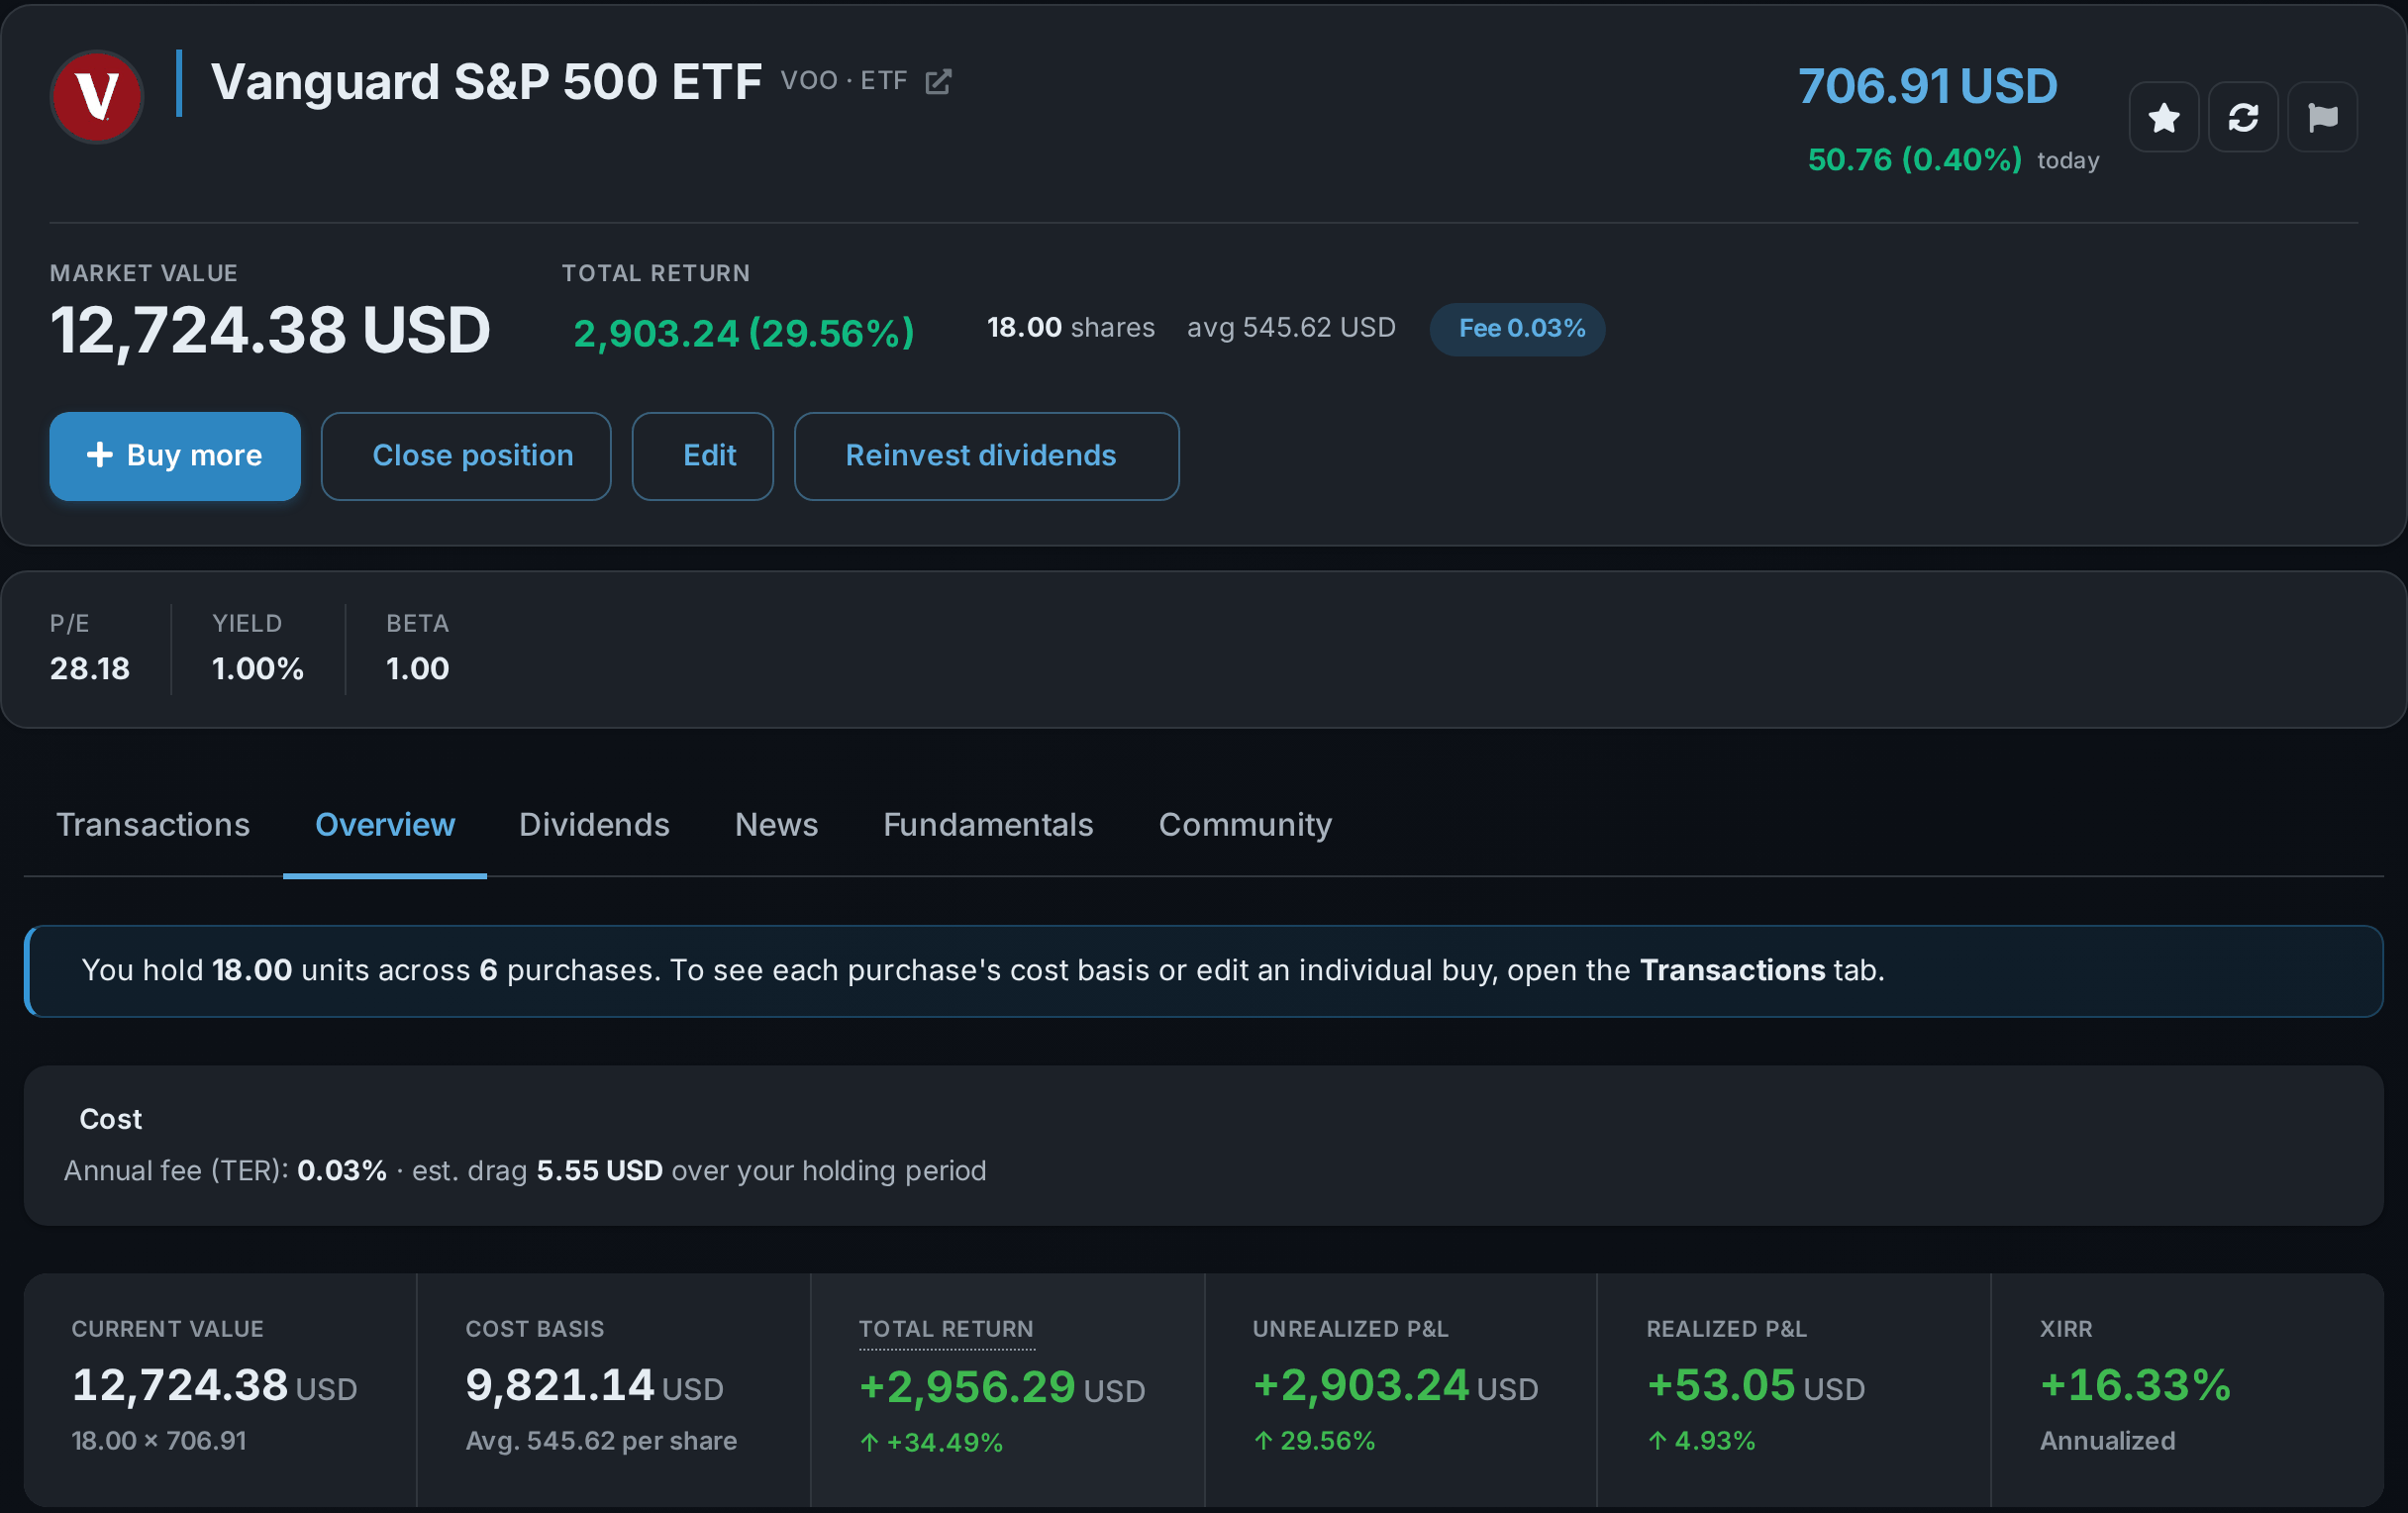
The holding page shows the fund's annual fee (TER) beside your shares and the estimated drag over the time you've held it: $5.55 on 18 shares bought over ten months. Value, cost basis, total return and XIRR sit right below it. To see what your ETFs hold in common before you add another fee, compare them in the free ETF overlap tool.
Compare two ETFs' holdings for free AllInvestView
Mutual funds, ETFs, stocks, bonds and crypto from all your accounts in one portfolio, with total return, dividends, fund fees and tax in the same place.
It's the yearly fee a mutual fund or ETF charges to run the fund, written as a percentage of what you hold. A 0.03% expense ratio costs $3 a year on $10,000; a 0.64% one, the 2025 average for actively managed stock mutual funds, costs $64.
You never get a bill. The fund sets aside a small slice of its assets for fees every day and pays them out of the fund, so the price or NAV you see, and the return the fund reports, are already after the fee. On SPY's 0.0945%, $10,000 costs about 2.6 cents a day.
For a broad stock index fund, 0.10% or less is easy to find: VOO charges 0.03%, and money in index stock mutual funds paid 0.05% on average in 2025. An actively managed stock fund averaged 0.64%, so it has to beat the index by about 0.6 percentage points a year just to match a 0.03% index fund.
Gross is the fund's full cost. Net is what you pay after the manager waives part of its fee or pays some expenses. T. Rowe Price Active Core U.S. Equity ETF (TACU) has a 0.14% gross and 0.00% net expense ratio, with the fee waived until 30 January 2027. When a waiver ends, the net can rise to the gross.
Yes. It's a percentage of the fund's assets, not of its gains, so it's charged in down years too. A smaller fund balance just means a smaller fee in dollars.
Sales charges such as a front-end load (up to 5.75% on The Growth Fund of America's Class A shares), the fund's own trading costs, your broker's commission and the bid-ask spread, and any advisory or platform fee you pay on top. Those can cost more than the expense ratio.
Close. In the UK and Europe, funds publish an ongoing charges figure (OCF) or total expense ratio (TER), which covers the same running costs. The EU version of the key information document also lists transaction costs on their own line. The Vanguard S&P 500 UCITS ETF (VUSA) has an OCF of 0.07%, against 0.03% for VOO, its US sibling.
Checked on 24 October 2026.
Averages are asset-weighted unless the page says otherwise. Fund expense ratios change; check the fund's latest prospectus before you buy. None of this is personal investment advice.