Thin margins, or losing money
Grocers, airlines and carmakers turn over a lot of money and keep little of it. Ford at 0.3 looks cheap and lost money in 2025.
The price-to-sales ratio is a company's market value divided by its revenue for the last year. It tells you how much investors pay for each dollar of sales. Coca-Cola was worth about $301 billion at the end of 2025 and had $47.9 billion of revenue that year, a P/S of 6.3.
The US market as a whole traded at about 3 times sales in January 2026. Grocers and airlines sit under 1, software and chipmakers above 10. A good P/S depends on how much of each dollar of sales the company keeps as profit, so compare it with companies in the same business, never across industries.
Or per share: share price ÷ sales per share. Coca-Cola: $300.7bn ÷ $47.9bn = 6.3.
Enter the market cap and a year of revenue, or the share price and sales per share. Add the profit margin to see the P/E that the P/S implies. It starts with Coca-Cola at the end of 2025.
P/S × 100 ÷ net margin = P/E. The same price-to-sales ratio means a low P/E for a business with fat margins and a high one for a business with thin margins. Gold bars are above 40 times earnings; striped bars are cut short.
Use revenue for the same 12 months the market cap is being compared with: the last four quarters, or the last full year. Quote pages usually show the trailing 12-month figure, so it moves every quarter as new results come in.
There is no single number. Here are 15 well-known companies, from Ford to Palantir, priced on 31 December 2025 against a year of revenue from their annual reports.






Market cap is the 31 December 2025 close times the shares outstanding on the cover of each company's annual report (all share classes). Revenue and net income are for the fiscal year in that report: the year to June 2025 for Microsoft, August 2025 for Costco, September 2025 for Apple, January 2026 for Walmart and Nvidia, and December 2025 for the rest. The dashed line is the whole US market, about 3 times sales. Bars past 25 are cut short: Palantir was at 95.
Grocers, airlines and carmakers turn over a lot of money and keep little of it. Ford at 0.3 looks cheap and lost money in 2025.
Walmart, Costco and Exxon Mobil. Walmart keeps about 3 cents of profit from each dollar of sales, so even 1.2 times sales is over 40 times earnings.
Amazon, Coca-Cola, Meta, Alphabet and Apple. Coca-Cola's 6.3 is backed by a 27% profit margin: 27 cents of every dollar of sales.
Microsoft and Nvidia earn 36 and 56 cents on each dollar of sales. Tesla at 17.8 kept 4 cents, so its price rests on growth investors expect, not on today's profit.
A P/S ratio is only cheap or expensive next to the profit behind it. Walmart at 1.2 and Nvidia at 21.0 were priced at about the same multiple of earnings, around 40 and 38. The useful comparison is a company against its own history and against its closest competitors: Walmart with Costco, Coca-Cola with PepsiCo, Microsoft with other software companies.
US companies in January 2026, from Aswath Damodaran's data at NYU Stern. Each row is the industry's combined market value over its combined revenue, beside its net margin.
Net margin is net income ÷ revenue for the industry as a whole. Cars and trucks sit at 3.34 because Tesla's market value is in the total; Ford and GM on their own trade well under 1. Utilities show why EV/sales matters: their debt takes them from 2.90 to 5.25.
Sales are not profit. A company that keeps 3 cents of each dollar it sells earns far less from its sales than one that keeps 56 cents.
Walmart: 40.6 × 3.07% = 1.25. Nvidia: 37.7 × 55.6% = 21.0. Nearly the same price for each dollar of profit, 17 times apart on sales.
$713 billion of revenue and $21.9 billion of profit. A low P/S because Walmart sells groceries on thin margins, not because the shares were cheap.
$216 billion of revenue and $120 billion of profit. More than half of each dollar of sales ended up as profit, which is why a P/S of 21 was close to Walmart on earnings.
$187 billion of revenue and a loss of $8.2 billion, after about $10.7 billion of charges on its electric vehicle programmes. The lowest P/S here came with no earnings at all.
P/S is most useful when earnings don't help. When a company makes a loss or its earnings swing, as Ford's did, the P/E has nothing to say, and revenue is the steadier number to compare with the price. Pair it with the margin the company has made in the past, or the one it could make, and you are back to a P/E you can judge.
Each one divides the price by something different. Use the one that matches what you want to know.
| Ratio | Divides | Useful when | Misleads when |
|---|---|---|---|
| P/S | Market cap by revenue | Earnings are negative or swing a lot; comparing companies in the same business | Margins differ, or the company has a lot of debt |
| EV/sales | Market cap plus debt minus cash, by revenue | Companies carry very different debt, like utilities and carmakers | Margins differ, the same weakness as P/S |
| P/E | Price by earnings per share | Profits are steady | There is a loss or a one-off charge or gain |
| P/B | Price by book value per share | Valuing banks and insurers, where revenue means little | The value is in brands, software or patents, not on the balance sheet |
| EV/EBITDA | Enterprise value by EBITDA: earnings before interest, tax, depreciation and amortization | Comparing companies with different debt and tax | Heavy spending on equipment is left out |
Market cap counts only the shares. A company with a lot of debt looks cheaper on P/S than it is, because its revenue also has to pay the lenders. EV/sales adds debt and takes off cash: (market cap + debt − cash) ÷ revenue. US utilities go from 2.90 on P/S to 5.25 on EV/sales.
A company growing revenue 30% a year at 20 times sales is at about 15 times next year's sales and 12 the year after, if the price stays put. That is why fast growers carry a high P/S. The forward P/S uses the revenue analysts expect for the next 12 months.
At 10 times sales, a company would need to hand back all its revenue for 10 years, with no costs and no growth, to repay the price. In 2002 Scott McNealy, Sun Microsystems' chief executive, made that point about investors who had paid 10 times revenue for Sun's shares in 2000.
Our stock comparisons put the price-to-sales ratio next to the P/E, forward P/E, price to book and EV/EBITDA, with growth, return on equity, debt and dividends further down.
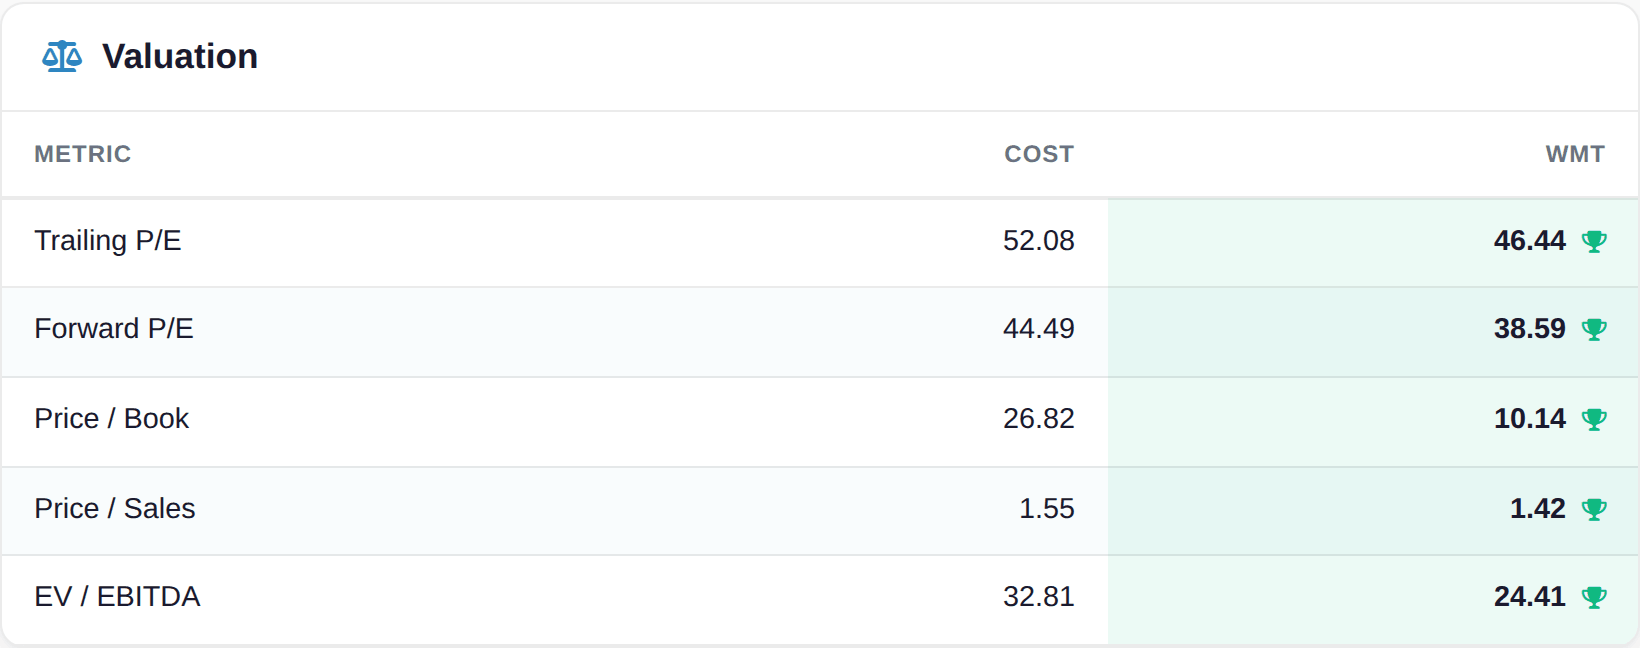
Pick any two stocks and see their valuation ratios in one table, with the lower of each marked. Price / Sales sits beside trailing and forward P/E, price to book and EV/EBITDA, so a low P/S can be checked against earnings straight away. Revenue per share, revenue growth and return on equity are in the same comparison.
Compare Costco and Walmart AllInvestView
All your accounts in one portfolio, with each holding's P/E and price to book on its stock page, side-by-side comparisons that add P/S, and your returns, dividends and tax in the same place.
Divide the company's market value by its revenue for the last 12 months. Coca-Cola was worth about $300.7 billion at the end of 2025 and had $47.9 billion of revenue that year, so its P/S was 6.3. Per share it's the same: the share price divided by revenue per share.
It depends on the industry. In January 2026 the US market as a whole traded at about 3 times sales; grocers were at 0.34, airlines at 0.58, software at 11 and semiconductors at 15.5. A P/S below its competitors' and its own history can be good value, as long as the company's profit margin isn't lower too.
Not on its own. A low P/S often means the company keeps little of each dollar it sells, or is losing money. Ford had the lowest P/S of the 15 companies here, 0.3 at the end of 2025, and lost $8.2 billion that year. Walmart at 1.2 times sales was over 40 times earnings.
P/E compares the price with profit, P/S with revenue. They are linked by the profit margin: P/S equals P/E times the net margin. Nvidia's P/S of 21 at the end of 2025 came with a 55.6% margin, so its P/E was 37.7, close to Walmart's 40.6 at a P/S of 1.2.
P/S uses market cap, the value of the shares. EV/sales uses enterprise value: market cap plus debt minus cash. It is the fairer comparison when companies carry very different debt. US utilities were at 2.90 on P/S and 5.25 on EV/sales in January 2026.
Because a company that makes a loss has no meaningful P/E, but it still has revenue. P/S lets you compare young or loss-making companies, or ones in a bad year, with their competitors. Then ask what profit margin the business could reach, because that decides whether the price makes sense.
Usually trailing: the last four reported quarters, so it changes every time a company reports. A forward P/S uses the revenue analysts expect over the next 12 months. For a company growing fast the forward figure is much lower: at 20 times sales and 30% growth, it's about 15.
Checked on 23 October 2026.
Company ratios are worked from each annual report's revenue and net income and the end-of-2025 share price. None of this is personal investment advice.