=PRODUCT(1+B2:B13)^(12/COUNT(B2:B13))-1Monthly returns as decimals in B2:B13. In Google Sheets wrap it in =ARRAYFORMULA( ). For one year it's the plain total return.
The Sharpe ratio tells you how much return an investment earned above cash for each unit of risk it took, with risk measured as how much its returns swung. A Sharpe of 1 means every 1% of yearly swings came with 1% a year of extra return; 0.5 means half that. Higher is better, as long as you compare the same years.
Over the ten years to September 2026, SPY, the S&P 500 fund, returned 15.2% a year and ARK Innovation (ARKK) 15.9%. ARKK swung two and a half times as much and fell 77% at its worst, so its Sharpe ratio was 0.35 against SPY's 0.84.
Volatility is the standard deviation of the returns, made yearly: × √12 for monthly returns. The risk-free rate is the rate on short government bills over the same period.
 S&P 500 (SPY)
 ARK Innovation (ARKK)Above 1 for ten years
Each dot is a fund, or Berkshire Hathaway's shares, over the ten years from October 2016 to September 2026: its volatility across, its return a year up. The open circle is cash: 2.43% a year, the average 3-month Treasury bill rate. Draw a line from cash to any dot and its slope is that investment's Sharpe ratio. The steeper the line, the more return each point of volatility bought.
Annual return and annual volatility from 120 monthly total returns, dividends reinvested.
The line at 0 is cash. Below it, the investment earned less than the T-bill rate.

ARKK and SPY ended the decade with almost the same return. SPY got there with 15.3% volatility and a worst fall of 23.9%; ARKK with 38.3% and a fall of 77.1% from January 2021 to December 2022. The Sharpe ratio is what tells those two apart. The 60/40 fund (AOR) returned less than either, but swung so much less that its Sharpe, 0.55, beat ARKK's.
Paste returns or prices, one per line, or enter the three numbers if you already have them. It opens with SPY's ten years from the chart above.
SPY in 2025, month by month, with dividends reinvested. Over a single year the annual return is simply the year's return.
| 2025 | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| SPY return | 2.69% | −1.27% | −5.57% | −0.87% | 6.28% | 5.14% | 2.30% | 2.05% | 3.56% | 2.38% | 0.19% | 0.08% |
| 3-month T-bill, a year | 4.21% | 4.22% | 4.20% | 4.21% | 4.25% | 4.23% | 4.25% | 4.12% | 3.92% | 3.82% | 3.78% | 3.59% |
=PRODUCT(1+B2:B13)^(12/COUNT(B2:B13))-1Monthly returns as decimals in B2:B13. In Google Sheets wrap it in =ARRAYFORMULA( ). For one year it's the plain total return.
=STDEV.S(B2:B13)*SQRT(12)The sample standard deviation, made yearly. Google Sheets accepts STDEV.S or STDEV. Use SQRT(52) for weekly returns and SQRT(252) for daily.
=(E2-E3)/E4Annual return in E2, the average risk-free rate in E3 (0.0407 for 2025), the volatility in E4.
You'll often read that 1 is good, 2 very good and 3 excellent. Over a few months or a trading strategy, maybe. Over the ten years an investor might actually hold something, the S&P 500 itself has rarely been above 1. The chart shows SPY's Sharpe over the three and ten years ending each month since 1996.
Monthly total returns against the T-bill rate of the same months.
SPY to 30 September 2026, monthly total returns.
| Period | Return a year | Volatility | Sharpe |
|---|---|---|---|
| 1 year | 15.71% | 13.19% | 0.91 |
| 3 years | 22.76% | 12.43% | 1.48 |
| 5 years | 13.70% | 15.67% | 0.63 |
| 10 years | 15.23% | 15.33% | 0.84 |
| 20 years | 11.11% | 15.28% | 0.62 |
| 30 years | 10.23% | 15.31% | 0.52 |
Over every ten-year window ending from January 2003 to September 2026, SPY's Sharpe had a median of 0.43 and was above 1 in 9% of them. Over three-year windows ending from January 1996, the median was 0.90 and 43% were above 1.
Below 0Earned less than cash. Bonds from 2016 to 2026: BND −0.24, TLT −0.38.
0 to 0.5Paid for the risk, but not by much. Small caps (IWM) and international stocks (VXUS) over the same decade.
0.5 to 1A good result over five years or more. Where the S&P 500 has landed over 10, 20 and 30 years.
1 to 1.5Very good if it lasts. SPY's three-year Sharpe was in this range in 31% of months since 1996, its ten-year Sharpe in 9% since 2003.
Above 1.5Rare over long periods. Check how long the record is and whether the prices are smoothed or estimated before you trust it.
Same fund, same ten years, October 2016 to September 2026. Only the method changes.
| How SPY's Sharpe is measured | Volatility | Sharpe |
|---|---|---|
| Monthly returns, average T-bill rateThe method on this page | 15.33% | 0.84 |
| Weekly returns× √52 | 17.09% | 0.75 |
| Daily returns× √252: daily swings that reverse within the month add volatility | 17.95% | 0.72 |
| Average monthly excess return × 12 instead of compoundingEach month's return minus that month's T-bill, as in Sharpe's 1994 paper | 15.33% | 0.85 |
| Risk-free rate set to 0Some sites skip it; it flatters every fund | 15.33% | 0.99 |
| A monthly Sharpe, not annualizedFine on its own, wrong next to yearly ones: × √12 turns it into 0.85 | 4.43% a month | 0.24 |
The gap between the first row and Sharpe's own method grows with volatility: for ARKK it's 0.35 compounded against 0.51 on average monthly excess returns, because big swings drag a compound return down. None of these is wrong on its own. Compare Sharpe ratios only when they use the same period, the same return frequency and the same risk-free rate.
It squeezes return and risk into one number, so it misses whatever the volatility doesn't capture.

Over the same ten years Bitcoin and SPY have almost the same Sharpe. One fell three-quarters of its value, the other a quarter. Look at the maximum drawdown next to the Sharpe.
Doubling the S&P 500 each day doubled the volatility and nearly doubled the worst fall, yet the Sharpe only slipped from 0.84 to 0.67. The ratio barely shows how much bigger the losses got.
SPY's Sharpe was 1.48 over the three years to September 2026 and 0.52 over thirty. A fund launched in a good stretch can show a high Sharpe until its first bad year. A few years of returns give a rough estimate, too high or too low.
Volatility counts a 20% month up as risk, the same as a 20% month down. For investments with lopsided returns, like options strategies, gold or a single growth stock, the Sortino ratio counts only the months below a target you choose, so it shows the downside on its own.
All four divide a return by a kind of risk. They differ in which return and which risk.
| Ratio | Divides | Use it when |
|---|---|---|
| Sharpe | Return above cash by total volatility | You want one number for a whole portfolio, or to compare funds that would each be most of your money. |
| Sortino | Return above a target by downside deviation only | Returns are lopsided and big up months shouldn't count against it. |
| Treynor | Return above cash by beta | The holding is one piece of a diversified portfolio, where only its market risk is left. |
| Information ratio | Return above a benchmark by tracking error | You're judging a fund manager or a stock picker against the index they're trying to beat. |
A fund's factsheet gives you the fund's Sharpe. Yours depends on the mix you hold across all your accounts.
The Analytics tab puts your portfolio and the index you chose side by side: total and annual return, volatility and Sharpe, worked out from daily returns with the risk-free rate you set. Pick a combined portfolio and it covers the accounts you put in it, at any broker. Each stock and fund you hold with enough price history gets its own Sharpe too, and the efficient frontier marks the highest-Sharpe mix of your holdings it finds.
See the portfolio analyzer AllInvestView
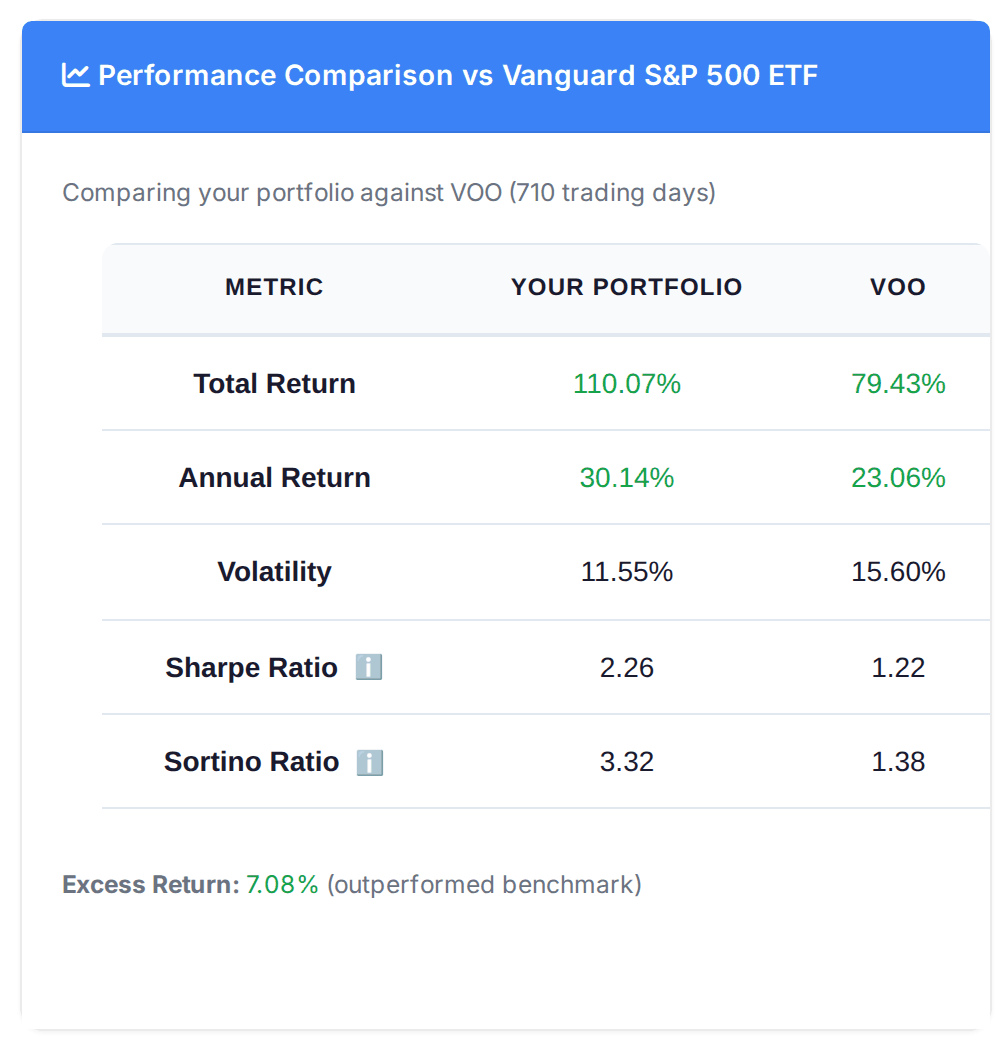
Add every account you hold and see the Sharpe, volatility and returns of your stocks and funds against the index you pick. No spreadsheet of returns to keep up to date.
Over several years, above 0.5 is decent, around 1 is very good and above 1.5 is rare. The S&P 500 (SPY) scored 0.84 over the ten years to September 2026 and 0.52 over thirty. Measured over ten years at each month-end since 2003, it was above 1 only 9% of the time. The rule of thumb that 1 is good and 2 is very good fits short periods better: in a single strong year SPY often scores 1.5 or more.
Sharpe divides by all volatility, so a big up month counts as risk just like a big down month. Sortino divides by downside deviation, which only counts the months that fell short of a target you choose. For options strategies, gold or single stocks with lopsided returns, that shows the downside on its own.
Take the annual return, subtract the risk-free rate for the same period, and divide by the annualized volatility: the standard deviation of the monthly returns × √12. SPY in 2025 returned 17.70%, the T-bill rate averaged 4.07% and its volatility was 10.97%, so (17.70 − 4.07) ÷ 10.97 = 1.24.
It depends on the years you measure. On SPY's monthly total returns to September 2026, against T-bills: 0.91 over 1 year, 1.48 over 3, 0.63 over 5, 0.84 over 10, 0.62 over 20 and 0.52 over 30. Its three-year Sharpe has ranged from −1.12 (to March 2003) to 2.38 (to March 1998).
Yes, whenever the investment earned less than cash over the period. Vanguard's total bond fund (BND) returned 1.18% a year from October 2016 to September 2026, below the 2.43% average T-bill rate, so its Sharpe was −0.24. Don't rank negative Sharpe ratios against each other: dividing a shortfall by more volatility makes the number less negative, which can make the riskier fund look better.
The rate on short government bills in your currency, averaged over the same period as your returns. For US dollars that's the 3-month Treasury bill: 2.43% on average over the ten years to September 2026, 4.07% in 2025. Using 0 flatters the result: SPY's ten-year Sharpe goes from 0.84 to 0.99.
To turn the volatility of monthly returns into a yearly figure. If months are independent, a year's variance is 12 times a month's, so its standard deviation is √12 times as big. Use √52 for weekly returns and √252 for daily ones. Without it you get a monthly Sharpe, which can't sit next to yearly ones: SPY's over the ten years is 0.24 a month, about 0.85 once annualized.
Checked on 28 October 2026.
Returns, volatilities, Sharpe ratios and falls are worked out by AllInvestView from month-end closing prices with dividends reinvested, October 2016 to September 2026 unless a different period is shown; Bitcoin from its month-end US dollar price. Annual return is compounded, volatility is the sample standard deviation of the monthly returns × √12, and the risk-free rate is the average 3-month Treasury bill rate over the same months. The worst fall is measured from a month-end peak to a month-end low. Sharpe ratios measure the past, not the future, and none of this is investment advice.